

When you need financing for home improvements, medical expenses, or education, understanding the fundamental differences between loan types helps you make informed borrowing decisions. The secured vs unsecured loan distinction represents one of the most important dividing lines in consumer lending, affecting everything from interest rates to approval requirements. Whether you're planning a major home renovation or consolidating debt, knowing which loan type aligns with your financial situation and risk tolerance can save you thousands of dollars and protect your assets.
Understanding the Core Difference Between Secured and Unsecured Loans
The primary distinction in the secured vs unsecured loan comparison centers on collateral. A secured loan requires you to pledge an asset as security for the debt, while an unsecured loan relies solely on your promise to repay and your creditworthiness.
What Collateral Means in Practice
Collateral serves as the lender's insurance policy. When you take out a secured loan, you grant the lender a legal claim against a specific asset. If you fail to repay, the lender can seize and sell that asset to recover their losses. Common forms of collateral include:
- Real estate (homes, land, investment properties)
- Vehicles (cars, trucks, motorcycles, RVs)
- Savings accounts or certificates of deposit
- Investment accounts
- Business equipment or inventory
The legal framework governing secured transactions under the Uniform Commercial Code establishes how lenders perfect their security interests and enforce their rights to collateral. This legal structure gives secured lenders priority over unsecured creditors in bankruptcy proceedings.
The Unsecured Loan Structure
Unsecured loans operate without collateral backing. Instead, lenders evaluate your credit history, income, employment stability, and debt-to-income ratio to determine eligibility. Since the lender has no asset to claim if you default, they assume greater risk compared to secured lending.
Personal loans, credit cards, student loans, and medical financing typically fall into the unsecured category. Payday loans are also unsecured products, though they carry significantly higher costs than traditional unsecured personal loans.
Interest Rates and Borrowing Costs
The secured vs unsecured loan debate invariably leads to discussions about cost. The presence or absence of collateral dramatically influences the interest rate you'll pay.
Why Secured Loans Cost Less
Lenders price loans based on risk. Because secured loans give lenders recourse to specific assets, they represent lower risk and therefore command lower interest rates. According to Federal Reserve consumer credit data, secured products like auto loans and mortgages consistently carry rates several percentage points below unsecured alternatives.
| Loan Type | Typical APR Range (2026) | Collateral Required |
|---|---|---|
| Mortgage | 6.5% – 8.0% | Real estate |
| Auto loan | 5.5% – 12.0% | Vehicle |
| Secured personal loan | 8.0% – 15.0% | Varies |
| Unsecured personal loan | 10.0% – 36.0% | None |
| Credit card | 18.0% – 29.0% | None |
These rate differentials compound over time. A $20,000 loan at 8% versus 18% creates a difference of thousands in total interest paid across a five-year term.
The Premium for Unsecured Borrowing
Research from the Federal Reserve Bank of New York examining interest rate patterns shows that unsecured personal loan rates vary widely based on borrower credit profiles. Lenders compensate for the absence of collateral by charging higher rates, particularly for borrowers with lower credit scores or limited credit histories.
For consumers with past credit challenges, unsecured loan rates can reach 25% to 36% APR. However, these products still provide access to credit when building or rebuilding financial standing.
Approval Requirements and Qualification Criteria
The secured vs unsecured loan distinction extends beyond pricing to eligibility standards. Each loan type emphasizes different aspects of your financial profile.
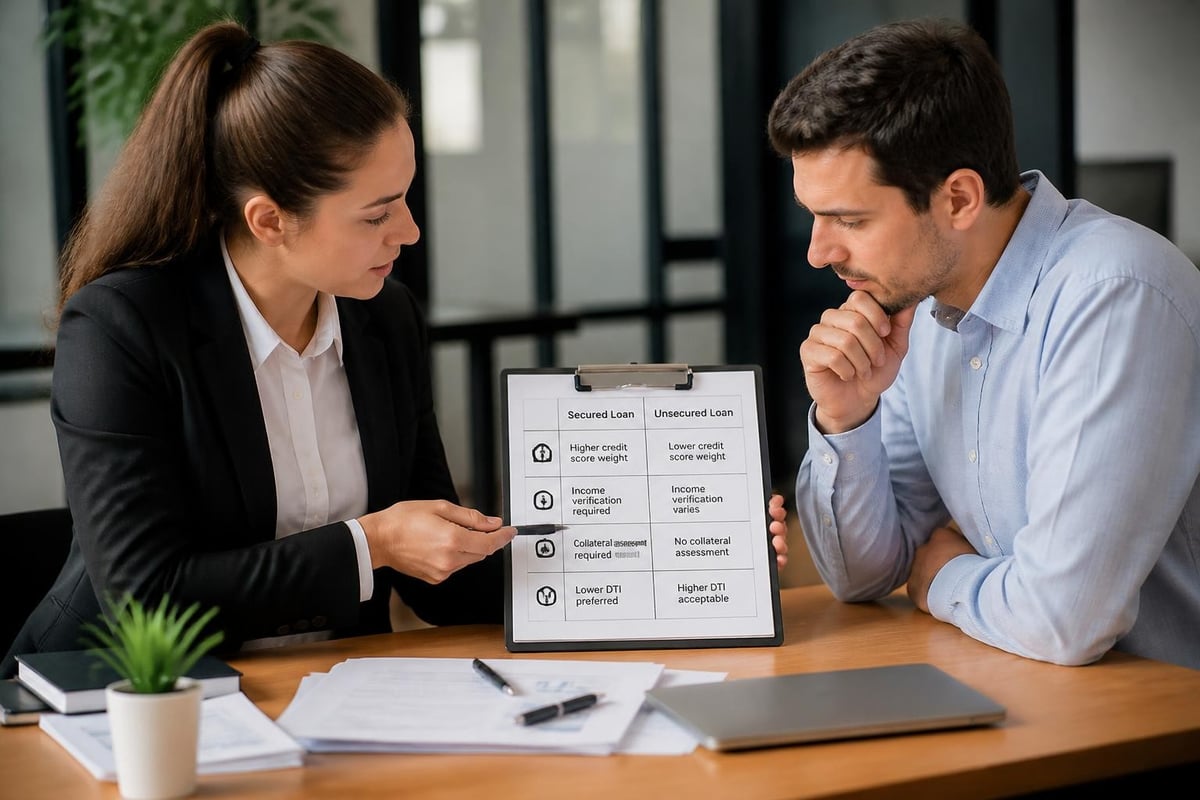
Secured Loan Approval Factors
When applying for a secured loan, lenders evaluate:
- Collateral value: The asset must have sufficient value to secure the loan amount
- Equity position: For homes or vehicles, you typically need existing equity or a down payment
- Credit history: While important, less weight than with unsecured loans
- Debt-to-income ratio: Your monthly obligations relative to gross income
- Income stability: Consistent employment or revenue stream
The distinction between first and second mortgages illustrates how lien priority affects approval. Second mortgages or home equity loans require adequate equity beyond the primary mortgage balance.
Unsecured Loan Qualification Standards
Without collateral to mitigate risk, unsecured lenders scrutinize creditworthiness more heavily:
- Credit score: Typically 620 or higher for approval; 700+ for best rates
- Credit history: Length of credit history and payment patterns
- Income verification: Recent pay stubs, tax returns, or bank statements
- Employment tenure: Stable job history demonstrates repayment ability
- Existing debt obligations: Lower debt-to-income ratios improve approval odds
Consumers with limited credit histories or past financial setbacks may find unsecured loans harder to obtain, though specialized lenders serve this market segment with adjusted terms and pricing.
Loan Amounts and Repayment Terms
The secured vs unsecured loan comparison also reveals differences in borrowing capacity and repayment structures.
Borrowing Limits
Secured loans generally allow larger amounts because the collateral reduces lender risk. Mortgages can reach hundreds of thousands of dollars, while secured personal loans might offer $5,000 to $100,000 depending on collateral value. Auto loans typically cover 80% to 120% of the vehicle's value.
Unsecured personal loans commonly range from $1,000 to $50,000, with most lenders capping amounts at $35,000. Your income, credit profile, and the lender's policies determine your specific limit.
Repayment Structures
| Feature | Secured Loans | Unsecured Loans |
|---|---|---|
| Typical terms | 3-30 years | 1-7 years |
| Monthly payment | Often lower (longer terms) | Generally higher (shorter terms) |
| Prepayment penalties | Sometimes present | Less common |
| Payment flexibility | Fixed or variable rates | Predominantly fixed rates |
Longer repayment periods on secured loans reduce monthly payments but increase total interest paid. Shorter unsecured loan terms create higher payments but build equity faster and reduce interest costs.
Risk Assessment for Borrowers
Understanding risk represents a critical element of the secured vs unsecured loan decision. Each option carries distinct consequences if financial circumstances change.
Secured Loan Risks
The most significant risk with secured debt is asset forfeiture. Defaulting on a mortgage can result in foreclosure, losing your home and damaging your credit for years. Auto loan defaults lead to repossession, potentially leaving you without transportation to work.
Beyond repossession risk, secured loans create:
- Reduced flexibility: Selling collateral requires loan payoff or lender consent
- Underwater positions: Market value declines can leave you owing more than the asset's worth
- Legal complications: Foreclosure or repossession proceedings appear on public records
Unsecured Loan Risks
While unsecured loan defaults won't cost you physical assets, consequences include:
- Severe credit damage: Payment delinquencies remain on credit reports for seven years
- Collection actions: Lenders may sue for judgments and wage garnishment
- Increased future costs: Credit damage raises rates on future borrowing
- Limited discharge options: Student loans particularly resist bankruptcy discharge
Neither option eliminates repayment responsibility. Choosing between secured and unsecured financing requires honest assessment of your repayment confidence and risk tolerance.
Tax Implications and Financial Planning
The secured vs unsecured loan distinction can affect tax treatment and broader financial strategy, though most consumer loans offer limited tax benefits.
Mortgage Interest Deductions
Secured mortgages on primary residences offer potential tax advantages. For tax year 2026, you may deduct interest on mortgage debt up to $750,000 if you itemize deductions. This benefit applies to first mortgages and qualifying home equity loans used for substantial home improvements.
As outlined in Treasury tax policy documentation, the Tax Cuts and Jobs Act limits which home equity debt qualifies for interest deductions. The loan proceeds must be used to buy, build, or substantially improve the home securing the loan.
Unsecured Loan Tax Treatment
Most unsecured consumer loans generate no tax deductions. Personal loan interest for debt consolidation, medical expenses, or general purposes doesn't reduce taxable income. Student loan interest represents an exception, with up to $2,500 potentially deductible regardless of whether you itemize.
Business owners may deduct interest on unsecured business loans as ordinary business expenses, but personal unsecured debt carries no such benefit.
Strategic Applications for Different Financial Goals
Choosing between secured and unsecured financing depends on your specific objectives and circumstances.
When Secured Loans Make Sense
Consider secured financing when you:
- Need substantial funds: Large projects like home renovations often require amounts only available through secured products
- Want lower rates: The collateral-driven rate reduction saves money over time
- Have valuable assets: Existing equity in a home or vehicle provides natural collateral
- Plan long repayment: Extended terms reduce monthly payment pressure
- Seek to build credit: Successfully managing secured debt demonstrates creditworthiness
Home improvement loans secured by your property typically offer better terms than unsecured alternatives. The added home value can also increase your equity position.
When Unsecured Loans Excel
Unsecured financing works better when you:
- Lack collateral: Renters and those without significant assets need non-collateralized options
- Want to preserve assets: Keeping assets unencumbered maintains financial flexibility
- Need quick funding: Unsecured loans often close faster without appraisal requirements
- Borrow smaller amounts: Amounts under $15,000 may not justify collateral procedures
- Prefer simplicity: No property liens or title complications
Medical expenses and education costs often fit unsecured loan profiles. These investments in health and human capital don't generate physical collateral but deliver important personal value.
Regulatory Framework and Consumer Protections
Federal and state regulations distinguish between secured and unsecured consumer lending in terms of disclosure requirements, interest rate caps, and collection practices.
Truth in Lending Act Requirements
The federal Truth in Lending Act requires lenders to disclose the Annual Percentage Rate (APR), finance charges, amount financed, and total payments for both secured and unsecured loans. These standardized disclosures enable comparison shopping across loan types and lenders.
Additional protections apply to secured loans involving primary residences. The Home Ownership and Equity Protection Act provides enhanced disclosures and restricts certain practices for high-cost mortgages.
State-Level Variations
Consumer lending regulations vary significantly by state. Louisiana, Mississippi, Tennessee, and Georgia each maintain distinct frameworks for:
- Maximum interest rates and fees
- Licensing requirements for lenders
- Foreclosure and repossession procedures
- Statute of limitations on debt collection
- Exemptions protecting certain assets from creditors
Understanding your state's specific protections helps you evaluate loan terms and know your rights throughout the borrowing relationship.
Credit Score Impact and Long-Term Effects
The secured vs unsecured loan choice influences how borrowing affects your credit profile, though both types appear on credit reports.
Credit Utilization and Mix
Unsecured revolving credit (like credit cards) factors heavily into credit utilization ratios, which represent 30% of FICO scores. Installment loans, whether secured or unsecured, contribute to credit mix (10% of scores) but don't affect utilization the same way.
According to Experian’s analysis of how different loan types affect credit, successfully managing a mix of secured and unsecured accounts demonstrates credit versatility. This diversity can strengthen your credit profile over time.
Payment History Reporting
Both secured and unsecured lenders report payment activity to credit bureaus. Timely payments build positive history regardless of loan type, while late payments damage scores equally. The secured vs unsecured designation doesn't change how payment performance affects creditworthiness.
However, the consequences of severe delinquency differ. Foreclosure or repossession on secured debt creates distinct negative marks beyond simple late payments, potentially causing steeper score declines than unsecured charge-offs.
Making Your Decision
Evaluating the secured vs unsecured loan question requires analyzing multiple dimensions simultaneously. Create a decision framework addressing:
Financial capacity: Calculate comfortable monthly payments based on income stability and existing obligations. Secured loans may offer lower payments through extended terms, while unsecured loans build equity faster.
Risk tolerance: Honestly assess your comfort with pledging assets. Conservative borrowers may prefer unsecured options despite higher costs, while those confident in repayment ability can leverage secured loan advantages.
Asset availability: Inventory potential collateral and its current value. Adequate home equity or vehicle value makes secured borrowing accessible, while limited assets necessitate unsecured alternatives.
Purpose alignment: Match loan structure to use case. Home improvements naturally align with home equity loans, while medical expenses or debt consolidation often suit unsecured personal loans.
Credit standing: Evaluate your credit profile realistically. Strong credit (720+) unlocks competitive unsecured rates approaching secured loan costs, while rebuilding credit may require accepting higher unsecured rates or pursuing secured options.
Neither secured nor unsecured loans represent universally superior choices. The optimal selection depends on your unique circumstances, goals, and financial profile at the time you need financing.
Understanding the secured vs unsecured loan distinction empowers you to choose financing that matches your needs, risk tolerance, and financial goals. Whether you need funds for home improvements, medical expenses, education, or other important life events, Standard Financial offers both secured and unsecured lending options across Louisiana, Mississippi, Tennessee, and Georgia. Our experienced team helps clients with diverse credit backgrounds find flexible financing solutions tailored to their situations, making the borrowing process straightforward and accessible.

No comment yet, add your voice below!