

Finding the right finance company in Baton Rouge can make all the difference when you need funds for home improvements, medical bills, education expenses, or debt consolidation. Louisiana's capital city offers numerous lending options, but understanding which providers truly serve your needs-especially if you've faced credit challenges-requires careful research. In 2026, consumer lending continues to evolve with more flexible terms, digital applications, and specialized programs designed for borrowers across the credit spectrum. This guide explores what sets Baton Rouge finance companies apart, how to choose the right lender, and what regulatory protections ensure fair treatment throughout your borrowing journey.
Understanding Consumer Lending in Baton Rouge
Baton Rouge's consumer finance landscape reflects Louisiana's broader economic momentum. The city's diverse economy-spanning petrochemicals, healthcare, education, and technology-creates varied lending needs among residents. Louisiana’s strong investment growth in recent years has strengthened the local economy, but individual households still face unexpected expenses that require financing solutions.
A finance company in Baton Rouge typically specializes in personal loans that banks may not prioritize. These lenders understand that credit scores don't tell the complete story of someone's financial responsibility.
Types of Personal Loans Available
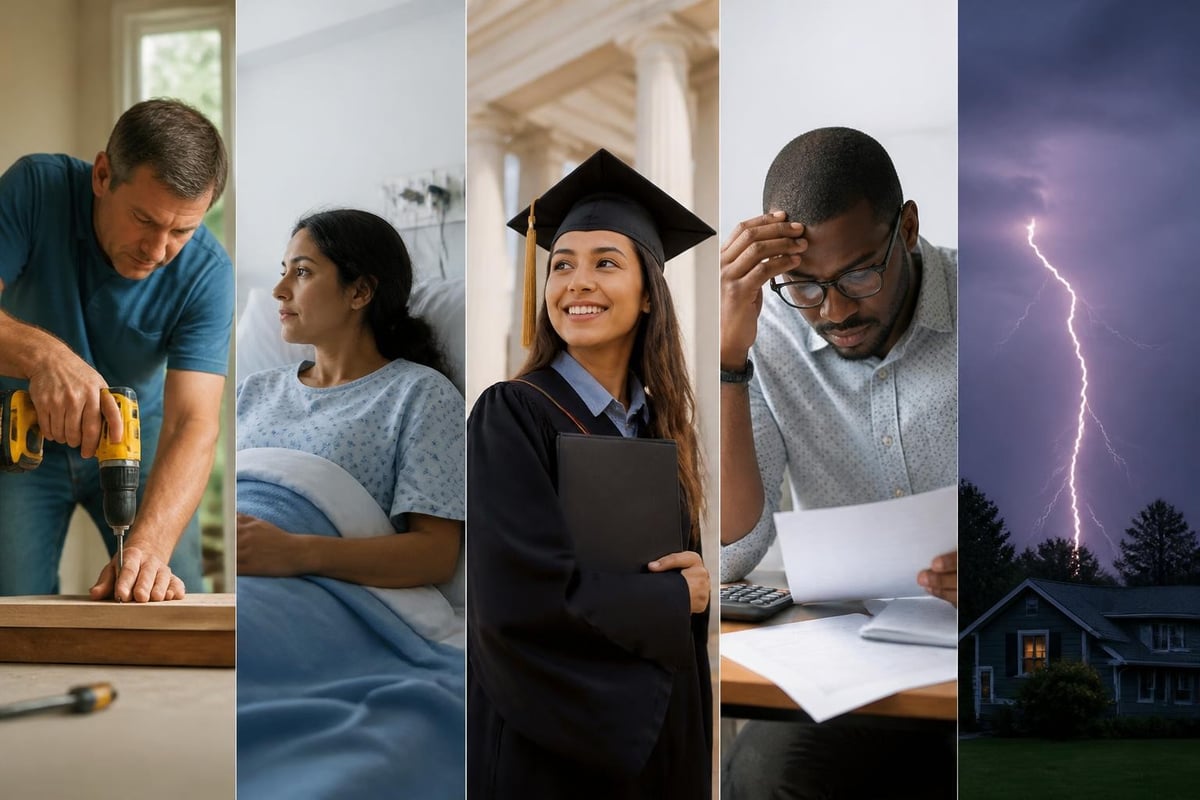
Consumer lenders in Baton Rouge offer several loan categories:
- Home improvement loans for renovations, repairs, roof replacement, HVAC systems, and energy-efficiency upgrades
- Medical expense financing covering procedures, dental work, vision correction, or ongoing treatment costs
- Education loans for tuition, certification programs, trade schools, and continuing education
- Debt consolidation loans that combine multiple high-interest debts into one manageable payment
- Emergency funds for unexpected car repairs, appliance replacement, or urgent household needs
Most finance companies structure these as installment loans with fixed monthly payments over 12 to 60 months. This predictability helps borrowers budget effectively.
How Finance Companies Differ from Traditional Banks
Traditional banks primarily focus on prime borrowers-those with excellent credit scores and substantial income documentation. A finance company in Baton Rouge takes a more comprehensive approach to underwriting.
| Feature | Traditional Banks | Consumer Finance Companies |
|---|---|---|
| Credit requirements | Prime (680+) | Subprime to near-prime (580+) |
| Application process | Extensive documentation | Streamlined, flexible verification |
| Approval speed | 5-10 business days | Often same-day or next-day |
| Relationship focus | Transaction-based | Long-term customer relationships |
| Loan purposes | General, often unsecured | Specific needs, flexible collateral |
| Refinancing options | Limited | Extensive, built-in flexibility |
This structure means finance companies serve borrowers who may have experienced past credit issues, job changes, medical debt, or other challenges that don't reflect their current ability to repay.
The Regulatory Framework Protecting Borrowers
Louisiana maintains robust oversight of consumer lenders through the Office of Financial Institutions (OFI). The 2025 annual report on non-depository lenders shows that state regulators actively monitor lending practices, interest rates, and consumer complaints to ensure fair treatment.
Key protections include:
- Maximum interest rate caps on various loan types
- Required disclosure of all fees and charges before loan signing
- Cooling-off periods for certain loan products
- Complaint resolution procedures through OFI
- Regular examinations of licensed lenders
Any reputable finance company in Baton Rouge holds current Louisiana licenses and complies with both state and federal lending regulations. Borrowers should always verify a lender's license status before signing any agreements.
Federal Oversight and Consumer Rights
Beyond state regulation, federal agencies provide additional layers of protection. The Consumer Financial Protection Bureau (CFPB) enforces truth-in-lending laws and investigates predatory practices. Recent CFPB guidance on small-business lending reflects broader regulatory trends toward transparency and fair access across all lending sectors.
The Federal Reserve monitors regional economic conditions that affect lending. Their Beige Book reports for the St. Louis Fed region provide insights into local credit demand, employment trends, and economic factors that influence both lenders and borrowers in Baton Rouge.
Choosing the Right Finance Company
Selecting a finance company in Baton Rouge requires evaluating several critical factors beyond just the interest rate. While rate matters, the overall borrowing experience and lender reliability deserve equal consideration.
Essential Evaluation Criteria
1. Transparency and Communication
The best lenders explain every term clearly before you sign. They provide written estimates, detail all fees, and answer questions patiently. Red flags include pressure to sign quickly, vague answers about rates, or unwillingness to provide written terms for review.
2. Flexibility in Loan Terms
Life circumstances change. Quality finance companies offer:
- Refinancing options if your financial situation improves
- Payment date flexibility to align with your pay schedule
- Hardship programs for temporary setbacks
- Early payoff without penalties
3. Local Presence and Accessibility
Branch offices in Baton Rouge mean face-to-face service when you need it. While digital applications offer convenience, having a local office provides accountability and easier problem resolution.
4. Track Record and Reputation
Research the lender's history through:
- Better Business Bureau ratings and complaint patterns
- Online reviews from verified borrowers
- Years in operation and community involvement
- OFI complaint records (available through public records requests)
Understanding Total Loan Costs
When comparing offers from different finance companies, calculate the total cost over the loan's life:
| Loan Details | Lender A | Lender B | Lender C |
|---|---|---|---|
| Loan amount | $5,000 | $5,000 | $5,000 |
| Interest rate (APR) | 24.99% | 22.50% | 26.00% |
| Term | 36 months | 48 months | 36 months |
| Monthly payment | $201 | $147 | $206 |
| Total repayment | $7,236 | $7,056 | $7,416 |
| Origination fee | $150 | $0 | $200 |
| Total cost | $7,386 | $7,056 | $7,616 |
Lender B offers the best total cost despite a longer term, though Lender A provides faster debt freedom. Your choice depends on whether you prioritize lower monthly payments or faster payoff.
Navigating the Application Process
Modern finance companies have streamlined applications while maintaining thorough underwriting. Understanding what to expect removes uncertainty and speeds approval.
Required Documentation
Most Baton Rouge lenders request:
- Proof of identity: Driver's license or state-issued ID
- Proof of income: Recent pay stubs, tax returns, or bank statements
- Residence verification: Utility bill, lease agreement, or mortgage statement
- Employment confirmation: Contact information for your employer
- References: Personal or professional contacts (typically 2-3)
Self-employed borrowers may need additional documentation like business bank statements or 1099 forms from the past two years.
The Approval Timeline
Day 1: Application submission
Complete the application online or in-branch. Many finance companies in Baton Rouge offer same-day preliminary decisions.
Day 1-2: Verification
The lender confirms employment, income, and references. Quick responses from your employer and references accelerate this phase.
Day 2-3: Final approval and loan documents
Once verified, you receive final terms and loan agreements. Review carefully before signing.
Day 3-5: Funding
After signing, funds typically arrive via direct deposit within 24-48 hours or by check within 3-5 business days.
Refinancing and Long-Term Relationship Benefits
A significant advantage of working with an established finance company in Baton Rouge is access to refinancing as your financial situation improves. Many lenders proactively reach out when you qualify for better terms.
When Refinancing Makes Sense
Consider refinancing when:
- Your credit score has increased by 50+ points since your original loan
- You've built six months of on-time payment history
- Interest rates have decreased in the broader market
- You need to extend terms temporarily due to income changes
- You want to consolidate additional debt into one payment
Refinancing typically involves a new loan that pays off your existing balance. The new loan carries improved terms-lower interest, reduced payments, or both.
Building Credit Through Responsible Borrowing
Every on-time payment to your finance company reports to major credit bureaus, helping rebuild or establish credit. This creates a positive cycle: better credit leads to refinancing opportunities, which further improves your financial position.
Strategic credit-building steps:
- Set up automatic payments to ensure you never miss due dates
- Pay slightly more than the minimum when possible to reduce principal faster
- Monitor your credit reports quarterly for accuracy
- Maintain communication with your lender if challenges arise
Economic Factors Affecting Baton Rouge Lending
The local economy significantly influences lending availability and terms. Baton Rouge's diverse economic base provides stability, but certain sectors impact consumer finance more directly.
Industry Influences on Lending Demand
Petrochemical sector fluctuations affect thousands of households in the Baton Rouge area. When energy prices rise, local employment and wages strengthen, reducing loan demand for emergencies while increasing home improvement borrowing. Conversely, industry downturns increase demand for bridge loans and debt consolidation.
Healthcare and education sectors-anchored by institutions like Our Lady of the Lake Regional Medical Center and Louisiana State University-provide employment stability. These sectors generate steady demand for predictable financing needs like education loans and planned medical procedures.
Market Competition and Consumer Benefits
Baton Rouge's lending market includes both national finance companies and regional specialists. This competition benefits consumers through:
- More competitive interest rates as lenders vie for borrowers
- Innovation in application processes and customer service
- Expanded product offerings tailored to specific needs
- Better refinancing programs to retain customers
The local banking market structure shows deposit concentration and lending patterns that influence how finance companies position their services.
Special Circumstances and Niche Lending
Finance companies in Baton Rouge recognize that borrowers face unique situations requiring customized solutions beyond standard personal loans.
Lending for Credit-Challenged Borrowers
Past credit issues don't permanently disqualify you from financing. Reputable lenders consider:
- Recent payment history: The past 12-24 months matter more than old accounts
- Income stability: Consistent employment demonstrates repayment ability
- Reasonable debt-to-income ratios: Total monthly debts under 45-50% of gross income
- Explanations for past issues: Medical emergencies, job loss, or divorce provide context
These lenders structure loans with appropriate safeguards while offering genuine opportunities for borrowers rebuilding their financial lives.
Seasonal and Emergency Lending
Certain times of year create predictable financing needs:
| Season | Common Loan Purposes | Typical Amounts |
|---|---|---|
| Summer | Home improvements, vacation expenses | $3,000-$10,000 |
| Fall | Back-to-school costs, HVAC repairs | $1,500-$5,000 |
| Winter | Holiday expenses, heating system repairs | $2,000-$7,500 |
| Spring | Tax-time debt consolidation, home repairs | $4,000-$12,000 |
| Year-round | Medical emergencies, car repairs | $1,000-$8,000 |
Understanding these patterns helps borrowers plan ahead and potentially secure better terms by borrowing during lower-demand periods.
Technology and the Modern Lending Experience
The finance company in Baton Rouge of 2026 looks different from even five years ago. Technology has transformed how lenders and borrowers interact while maintaining the personal touch that local companies provide.
Digital Application Advantages
Mobile-first platforms let you apply from anywhere, upload documents via smartphone camera, and track application status in real-time. Most Baton Rouge finance companies now offer apps that provide:
- Instant pre-qualification without hard credit pulls
- Secure document upload and storage
- Payment management and scheduling
- Direct messaging with loan officers
- Refinancing eligibility notifications
Maintaining Personal Service
Despite digital convenience, successful finance companies balance technology with human interaction. Critical moments-explaining loan terms, discussing hardship options, or planning refinancing-benefit from personal conversation with knowledgeable staff who understand Baton Rouge's economic landscape.
Branch offices serve as community hubs where borrowers build relationships with specific loan officers who remember their circumstances and proactively suggest solutions.
Regulatory Compliance and Industry Standards
Legitimate finance companies embrace regulation as a mark of credibility. Understanding the regulatory environment helps borrowers recognize compliant lenders and avoid predatory operators.
State Licensing Requirements
Louisiana requires consumer finance companies to obtain licenses through the Office of Financial Institutions. Licensed lenders must:
- Maintain minimum net worth requirements
- Submit to regular examinations
- File annual reports detailing loan volumes, rates, and complaints
- Post bonds to protect consumers
- Employ qualified managers with clean regulatory records
The detailed reporting in Louisiana’s annual non-depository lender report demonstrates the state's commitment to transparency and consumer protection.
Federal Lending Regulations
Federal rules supplement state oversight. The Truth in Lending Act requires clear disclosure of APR, finance charges, and payment schedules. The Equal Credit Opportunity Act prohibits discrimination based on race, religion, national origin, sex, marital status, age, or receipt of public assistance.
Recent federal rulemaking affecting small-business lending reflects broader regulatory trends toward data collection, transparency, and fair access that influence consumer lending practices as well.
Community Impact and Local Economic Development
Finance companies contribute to Baton Rouge's economic health beyond individual loans. Their lending activity supports local businesses, employment, and community development initiatives.
Supporting Small Business Growth
While primarily focused on consumer lending, many finance companies indirectly support small businesses by financing entrepreneurs' personal needs. A medical professional financing continuing education or a contractor funding home office improvements uses consumer loans to build business capacity.
The U.S. Small Business Administration’s Louisiana office coordinates various programs that sometimes intersect with consumer lending, particularly for sole proprietors and independent contractors who blur the line between personal and business finance.
Reinvestment in Local Communities
Established finance companies in Baton Rouge often participate in community development through:
- Financial literacy programs teaching budgeting, credit management, and borrowing basics
- Partnership with nonprofits addressing housing, education, and economic mobility
- Sponsorship of community events supporting local culture and connection
- Employment opportunities providing career paths for local residents
These contributions strengthen the entire community while building the lender's reputation and customer relationships.
Making Your Finance Decision
Armed with comprehensive knowledge about finance companies in Baton Rouge, you can make informed borrowing decisions that align with your financial goals and circumstances.
Final Checklist Before Borrowing
Before signing loan documents, verify:
- You understand the total cost, including all fees and interest
- The monthly payment fits comfortably within your budget
- The lender holds valid Louisiana licenses
- You've compared at least three lenders' offers
- You know the refinancing and early payoff terms
- You've read all fine print and asked questions about unclear terms
- The lender has explained hardship options if your circumstances change
Questions to Ask Your Lender
Don't hesitate to request clarity on:
- What is the APR, and how is it calculated?
- Are there any circumstances where my rate could increase?
- What fees apply at origination, during the loan, and at payoff?
- How soon can I refinance, and what triggers eligibility?
- What happens if I miss a payment or face financial hardship?
- How do you report to credit bureaus?
- Can I change my payment date if my work schedule changes?
Reputable finance companies welcome these questions and provide clear, patient answers.
Choosing the right finance company in Baton Rouge empowers you to address immediate financial needs while building a stronger credit foundation for the future. Whether you're planning a home renovation, covering unexpected medical costs, or consolidating debt, working with a lender who understands Louisiana's unique economic landscape and offers flexible, transparent terms makes all the difference. Standard Financial has served Louisiana residents for years with personal loans designed for real life-including options for those rebuilding credit-and multiple branch locations ensure you receive the personalized service and flexible solutions you deserve.

No comment yet, add your voice below!