

Understanding your rights and obligations under repossession laws in Louisiana is essential whether you're a borrower facing financial difficulties or simply want to know what protections exist when financing a vehicle or other personal property. Louisiana follows a unique civil law system influenced by its French legal heritage, which affects how creditors can reclaim collateral when borrowers default on loans. The state permits self-help repossession under specific conditions while maintaining important consumer protections that prevent aggressive collection tactics. This comprehensive guide examines the legal framework governing repossessions, the procedures creditors must follow, borrower rights during the process, and what happens after property is reclaimed.
Louisiana's Legal Framework for Repossessions
Repossession laws in Louisiana derive from multiple sources, including the Louisiana Commercial Laws, the Louisiana Civil Code, and specific administrative regulations that govern how repossession agencies operate. The state's approach allows secured creditors to reclaim collateral without obtaining a court order, provided they follow strict procedural requirements and avoid breaching the peace.
The Louisiana Motor Vehicle Commission oversees laws and regulations affecting vehicle sales financing and repossession practices through the Motor Vehicle Sales Finance Act. This regulatory framework establishes baseline requirements for creditors and their agents.
Licensing Requirements for Repossession Agents
Louisiana mandates that repossession agencies and individual agents obtain proper licensing before conducting any repossession activities. The Office of Financial Institutions administers the licensing program and maintains rules governing agent conduct, ensuring that only qualified professionals handle these sensitive transactions.
Licensed agents must meet specific criteria:
- Pass background checks with no disqualifying criminal convictions
- Maintain liability insurance coverage
- Complete required training on Louisiana repossession statutes
- Renew licenses annually and report any changes in business structure
- Comply with continuing education requirements
The licensing system protects consumers by establishing professional standards and providing a mechanism for complaints against agents who violate regulations. Borrowers can verify an agent's credentials and file grievances with the Office of Financial Institutions if improper conduct occurs during a repossession.
Self-Help Repossession and Breach of Peace
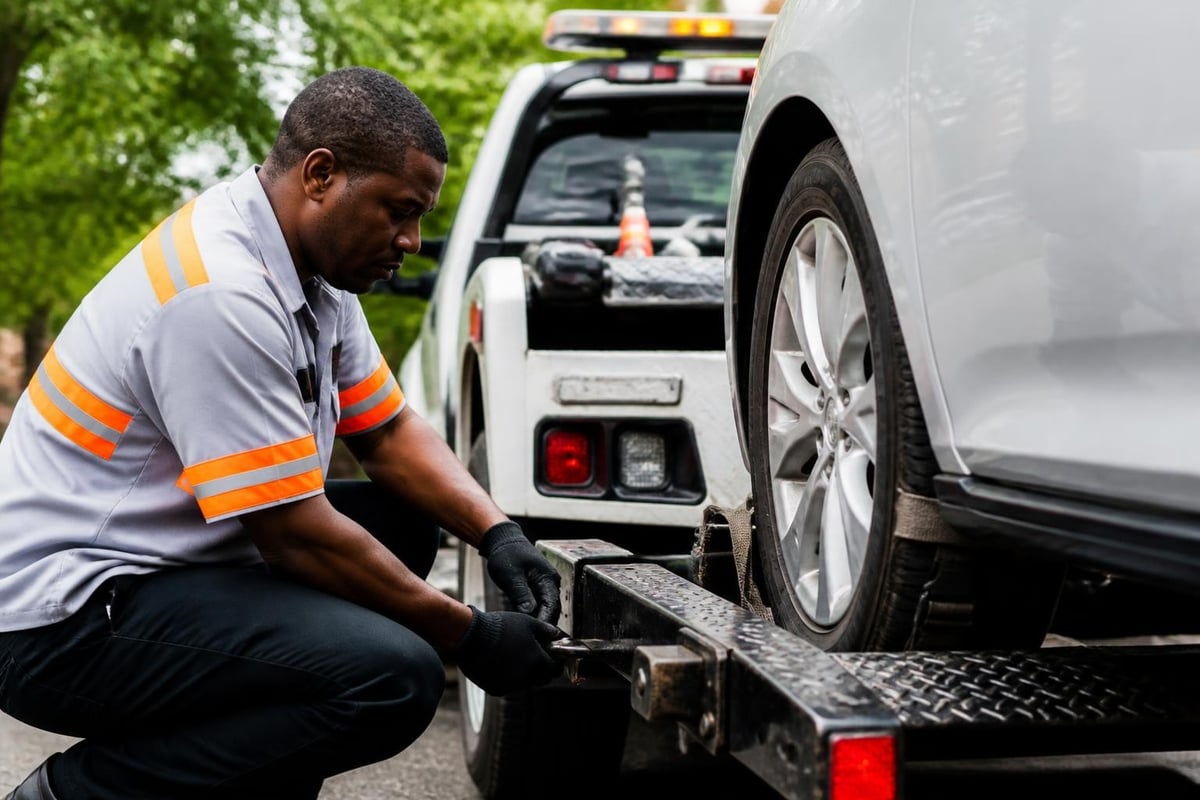
Louisiana law permits creditors to use self-help repossession, meaning they can reclaim collateral without filing a lawsuit or obtaining a court judgment. This expedited remedy exists when the security agreement specifically grants the creditor this right upon default. However, this powerful tool comes with significant limitations designed to prevent violent confrontations and protect borrower dignity.
What Constitutes Breach of Peace
The most critical restriction on self-help repossession is the prohibition against breaching the peace. While Louisiana statutes don't provide an exhaustive definition, courts have established that certain actions automatically violate this standard:
| Prohibited Actions | Permissible Actions |
|---|---|
| Using physical force or threats | Taking vehicle from public parking |
| Breaking into locked garages | Repossessing from open driveway |
| Ignoring verbal objections from debtor | Proceeding when no one present |
| Trespassing on clearly marked property | Accessing property without barriers |
| Creating public disturbances | Working quietly during reasonable hours |
When a borrower verbally objects to the repossession in real-time, agents must immediately cease their efforts. Continuing despite objections constitutes a breach of peace, even if no physical altercation occurs. This protection ensures borrowers can prevent repossession simply by being present and expressing refusal.
The consequences for breaching the peace are severe. Creditors lose their right to claim deficiency balances (the difference between what the borrower owes and what the vehicle sells for), and borrowers may sue for damages, including emotional distress and punitive damages in egregious cases.
Notice Requirements and Default Procedures
Repossession laws in Louisiana establish specific notice requirements that creditors must satisfy before and after reclaiming property. These notifications serve multiple purposes: they give borrowers opportunities to cure defaults, ensure transparency in the disposition process, and protect borrowers from unfair surprise.
Pre-Repossession Considerations
While Louisiana doesn't require creditors to provide advance warning before repossessing property, the original loan or security agreement often contains contractual notice provisions. Borrowers should carefully review their financing documents to understand what notifications they're entitled to receive.
Most consumer loan agreements include:
- Definition of default (typically missed payments, insurance lapses, or other breaches)
- Grace periods before default is declared
- Right to cure provisions allowing borrowers to bring accounts current
- Notice timelines the creditor commits to follow
Even without contractual requirements, responsible lenders typically contact borrowers multiple times before initiating repossession. These communications attempt to arrange payment plans, discuss hardship options, or negotiate voluntary surrender to avoid repossession costs.
Post-Repossession Notice Requirements
After taking possession of collateral, Louisiana law mandates that creditors provide written notice before selling the property. This notification must include:
- Description of the repossessed property
- Amount needed to redeem the property (total debt plus repossession costs)
- Statement of borrower's right to redeem before sale
- Information about the planned disposition method and timeline
- Creditor's contact information for questions or redemption
The notice must be sent to the borrower's last known address with sufficient time before the sale. Typically, creditors must wait at least 10 days after providing notice before selling the collateral, though specific timeframes may vary based on the type of property and financing agreement terms.
Borrower Rights During and After Repossession
Understanding your rights under repossession laws in Louisiana empowers you to protect yourself and potentially recover your property. The law provides several important protections that prevent creditors from taking unfair advantage during financial hardship.
Right to Redeem Property
Louisiana grants borrowers the absolute right to redeem repossessed property before it's sold. Redemption means paying the full amount owed, including:
- Entire remaining loan balance (not just past-due payments)
- Accrued interest and late fees
- Repossession costs and storage fees
- Legal fees if specified in the security agreement
This right continues until the moment the creditor sells the collateral. While redemption requires significant funds, it allows borrowers who experience temporary financial setbacks to recover their property. Some borrowers arrange personal loans from family members, refinance with new lenders, or access emergency funds to redeem valuable vehicles.
Personal Property Return
When creditors repossess vehicles, Louisiana law requires them to inventory and return all personal property found inside. This includes:
- Electronic devices and accessories
- Work tools and equipment
- Clothing and personal items
- Documents and identification
- Child safety seats
Creditors cannot hold personal property hostage or charge fees for its return. They must establish reasonable procedures for borrowers to reclaim belongings, typically allowing retrieval during business hours at the storage facility. Items considered fixtures or improvements to the vehicle (custom stereo systems permanently installed, for example) may be treated differently than loose personal property.
Disposition of Repossessed Property
After the redemption period expires, creditors must dispose of repossessed property in a commercially reasonable manner. This requirement protects borrowers from arbitrary sales that maximize deficiency balances. The Louisiana Administrative Code establishes specific rules governing repossession agent conduct and disposition procedures.
Commercial Reasonableness Standard
Commercial reasonableness encompasses several factors courts examine when disputes arise:
-
Sale Method: Creditors may use public auctions or private sales. Public auctions typically occur at regular intervals with multiple vehicles, while private sales involve negotiating with dealers or individual buyers.
-
Sale Price: The amount received must reflect fair market value. Selling significantly below market rates may indicate the disposition wasn't commercially reasonable.
-
Sale Timing: Waiting too long or rushing the sale may violate reasonableness standards. Creditors should sell within a reasonable timeframe that balances depreciation concerns against finding fair market prices.
-
Marketing Efforts: For private sales, creditors should make reasonable efforts to find buyers and obtain competitive offers.
Deficiency Balances and Surplus Refunds
After selling repossessed property, creditors calculate whether a deficiency or surplus exists:
Deficiency: When sale proceeds don't cover the remaining debt plus repossession costs, the borrower typically remains liable for the shortfall. Louisiana law allows creditors to pursue deficiency judgments through court proceedings.
Surplus: If sale proceeds exceed the total debt and costs, creditors must return the excess to the borrower. This rarely occurs but represents an important protection when collateral values exceed loan balances.
| Scenario | Remaining Balance | Sale Price | Costs | Result |
|---|---|---|---|---|
| Deficiency Example | $12,000 | $8,500 | $1,200 | Borrower owes $4,700 |
| Surplus Example | $8,000 | $11,500 | $900 | Borrower receives $2,600 |
| Break-Even Example | $10,000 | $10,500 | $500 | No further obligation |
Special Considerations for Vehicle Repossessions
Vehicles represent the most commonly repossessed collateral in Louisiana, and several specific rules apply to automobile financing. Understanding these particulars helps borrowers with car loans protect their rights and make informed decisions during financial challenges.
Certificate of Title Issues
Louisiana vehicle titles include lien notations showing secured creditors. When creditors repossess and sell vehicles, they must properly transfer ownership by:
- Obtaining the certificate of title if held by the debtor
- Completing lien release documentation after full satisfaction
- Transferring title to the new buyer with proper signatures
- Providing documentation to the Louisiana Office of Motor Vehicles
Borrowers who have fully paid loans should ensure lien releases are filed with the OMV. Failure to remove satisfied liens can cause problems when selling or refinancing vehicles.
Impact on Credit Reports
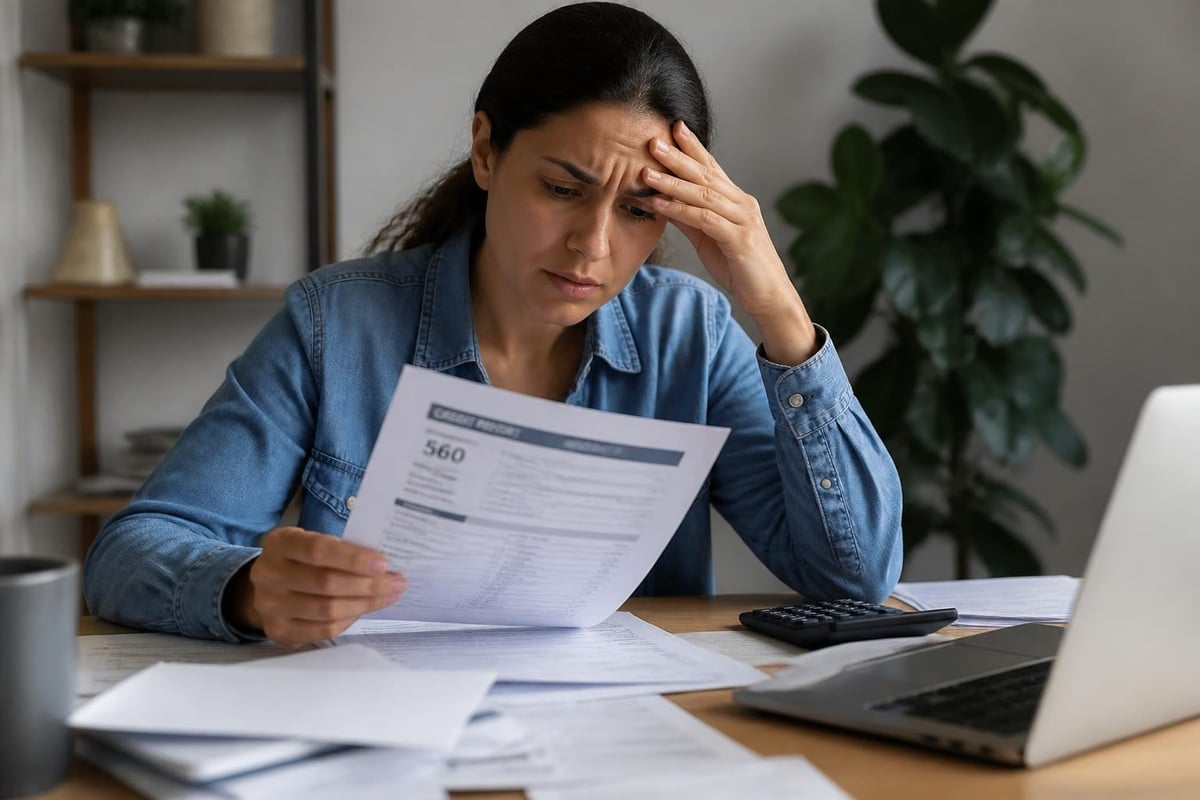
Vehicle repossession creates significant negative marks on credit reports that affect future borrowing ability. The impact includes:
- Initial default notation when payments become seriously delinquent
- Repossession entry showing the creditor reclaimed collateral
- Deficiency balance reported as a charged-off debt if unpaid
- Potential collection account entries if deficiency is sold
These entries remain on credit reports for seven years from the original delinquency date. The combined effect can reduce credit scores by 100 points or more, making it difficult to obtain favorable financing terms for years afterward.
Prohibited Practices and Consumer Protections
Repossession laws in Louisiana prohibit various aggressive tactics that some disreputable creditors or agents might attempt. Knowing these prohibited practices helps borrowers identify violations and seek appropriate remedies.
Illegal Repossession Tactics
State regulations and federal consumer protection oversight establish clear boundaries for repossession conduct:
Physical Intimidation: Agents cannot use force, threats, or intimidation to complete repossessions. This includes aggressive verbal confrontations, blocking borrowers from accessing their vehicles, or creating fear of physical harm.
Property Damage: Repossession agents must exercise reasonable care to avoid damaging collateral or other property. Breaking gates, damaging garage doors, or creating property destruction exposes creditors to liability.
Privacy Violations: Agents cannot enter homes without permission or misrepresent their identity to gain access to property. Deceptive practices violate Louisiana consumer protection laws.
Harassment of Third Parties: Discussing the debt or repossession with neighbors, employers, or family members beyond locating the borrower violates privacy protections. Agents should conduct operations discreetly.
Legal Remedies for Violations
Borrowers who experience illegal repossession practices have several avenues for relief:
- Actual Damages: Compensation for financial losses, property damage, and out-of-pocket expenses
- Statutory Damages: Specific penalty amounts established by consumer protection laws
- Emotional Distress: Compensation for anxiety, humiliation, and psychological harm from wrongful conduct
- Punitive Damages: Additional penalties designed to punish egregious violations and deter future misconduct
- Attorney Fees: Recovery of legal costs when successfully proving violations
Borrowers should document violations through photographs, witness statements, and contemporaneous notes. Consulting with consumer protection attorneys helps evaluate whether pursuing legal action is worthwhile based on the specific circumstances.
Alternatives to Repossession
Before repossession occurs, borrowers have several options that may preserve their property and protect their credit standing. Proactive communication with creditors often produces better outcomes than avoiding contact and waiting for repossession.
Voluntary Surrender
Voluntarily returning collateral to the creditor before forced repossession offers several advantages:
- Eliminates repossession agent fees (typically $300-$800)
- Reduces storage and administrative costs
- May demonstrate good faith to creditors
- Provides control over timing and circumstances
However, voluntary surrender doesn't eliminate deficiency liability. Borrowers remain responsible for the difference between sale proceeds and the outstanding debt. The credit impact is also similar to involuntary repossession, though some lenders note the voluntary nature in their reporting.
Loan Modification and Refinancing
Many creditors prefer working with borrowers to restructure loans rather than pursuing costly repossessions. Possible modifications include:
- Payment Extensions: Temporarily reducing payment amounts and extending the loan term
- Deferment Programs: Postponing payments for 30-90 days during hardship periods
- Principal Reduction: Rarely offered but possible in some circumstances
- Interest Rate Adjustments: Lowering rates to make payments more affordable
Refinancing with a new lender represents another option, particularly for borrowers who've built equity or improved their credit since the original loan. New loans with better terms can pay off problematic existing financing.
Selling the Collateral
If possible, selling collateral privately before repossession often generates higher prices than creditor sales. Borrowers can:
- List vehicles on private marketplaces at competitive prices
- Pay off the loan balance from sale proceeds
- Retain any surplus after satisfying the debt
- Avoid repossession marks on credit reports
This approach requires creditor cooperation since lienholders must release titles for sales to proceed. Most creditors accommodate private sales when borrowers demonstrate serious intent and realistic pricing.
Filing Complaints and Seeking Assistance
When borrowers encounter problems with repossession processes or believe agents violated regulations, Louisiana provides formal complaint mechanisms and assistance resources.
State Regulatory Complaints
The Office of Financial Institutions accepts complaints against licensed repossession agencies and agents. The complaint process includes:
- Submitting detailed written descriptions of alleged violations
- Providing documentation, photographs, or witness statements
- Cooperating with OFI investigators during review
- Receiving determinations about whether violations occurred
The OFI can impose sanctions including license suspension, fines, or revocation for serious or repeated violations. While regulatory action doesn't directly compensate borrowers, it creates official records useful in civil litigation.
Legal Assistance Resources
Borrowers facing repossession challenges should consider:
- Legal Aid Organizations: Nonprofit groups providing free or low-cost assistance to qualifying individuals
- Consumer Protection Attorneys: Lawyers specializing in creditor misconduct and debt collection violations
- Credit Counseling Agencies: HUD-approved counselors helping develop debt management plans
- State Bar Referral Services: Programs connecting borrowers with attorneys offering initial consultations
Early intervention produces better outcomes. Waiting until after repossession occurs limits available options and remedies.
Understanding Your Security Agreement
The foundation of repossession laws in Louisiana rests on the security agreement borrowers sign when obtaining financing. These contracts establish the creditor's rights to collateral and define default triggers. Understanding agreement terms helps borrowers avoid unintentional defaults and recognize when creditors exceed their authority.
Key Security Agreement Provisions
Typical security agreements contain several critical sections:
Default Definition: Specifies what constitutes breach of the agreement beyond missed payments. Common default triggers include:
- Failing to maintain required insurance coverage
- Using collateral for illegal purposes
- Moving collateral out of state without permission
- Filing bankruptcy (automatic stay complicates but doesn't prevent eventual repossession)
- Providing false information on loan applications
Acceleration Clauses: Provisions allowing creditors to declare the entire remaining balance immediately due upon default. Without acceleration, creditors could only demand past-due amounts.
Right to Cure: Some agreements provide specific timeframes for borrowers to remedy defaults before creditors exercise repossession rights. These cure periods offer valuable opportunities to avoid collateral loss.
Cost Recovery: Language establishing borrower responsibility for repossession costs, storage fees, legal expenses, and sale preparation charges. Understanding these provisions helps estimate total redemption costs.
Understanding repossession laws in Louisiana empowers borrowers to protect their rights while recognizing creditor remedies when financial challenges arise. The state's balanced approach permits self-help repossession while maintaining important consumer protections through breach of peace prohibitions, notice requirements, and commercially reasonable disposition standards. If you're facing financial difficulties and need flexible financing solutions to avoid repossession or manage existing debt, Standard Financial offers personalized loan options designed for Louisiana residents, including those with past credit challenges. Contact our experienced team today to explore refinancing opportunities that can help you maintain your financial stability.

No comment yet, add your voice below!