

When unexpected financial challenges arise, understanding your options can make the difference between temporary hardship and long-term financial damage. One solution that has helped millions of Americans navigate difficult times is loan forbearance. Whether you're facing medical expenses, job loss, or other economic pressures, knowing what is loan forbearance and how it works empowers you to make informed decisions about your financial future. This comprehensive guide explains everything you need to know about forbearance programs, from basic definitions to practical considerations for borrowers across Louisiana, Mississippi, Tennessee, and Georgia.
Understanding the Fundamentals of Loan Forbearance
Loan forbearance is a temporary relief option that allows borrowers to reduce or pause their monthly loan payments for a specific period. Unlike loan forgiveness, which eliminates debt entirely, forbearance simply postpones payment obligations. The unpaid balance doesn't disappear; instead, it's deferred to a later date, often through extended repayment terms or added payments at the end of the forbearance period.
How Forbearance Differs from Other Relief Options
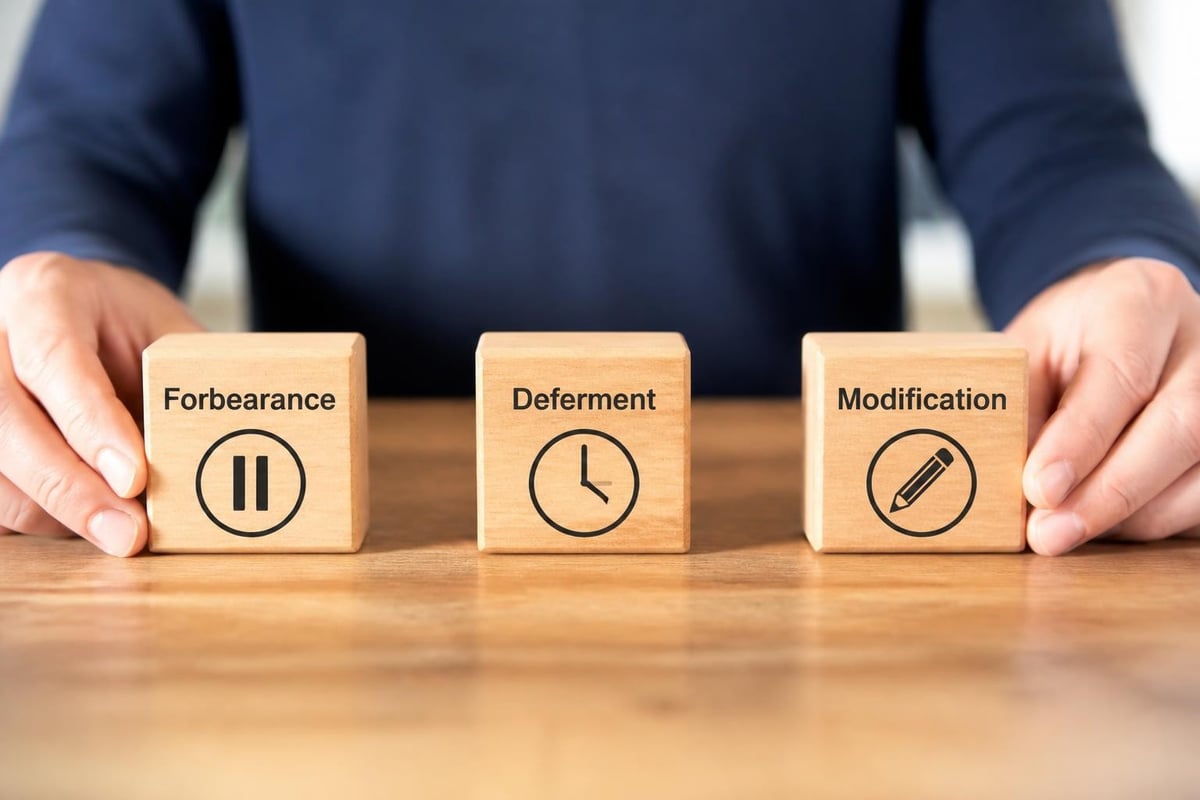
Many borrowers confuse forbearance with similar programs, but key distinctions exist. Deferment typically applies to student loans and may pause both payments and interest accrual under certain conditions. Modification permanently changes loan terms, such as interest rates or payment schedules. Forbearance, by contrast, provides temporary relief without permanently altering the original loan agreement.
The Consumer Financial Protection Bureau provides detailed guidance on mortgage forbearance, explaining borrower rights and servicer obligations. Understanding these distinctions helps you choose the most appropriate relief option for your situation.
The Mechanics of How Forbearance Works
When you enter forbearance, your lender agrees not to pursue collection activities or report missed payments as delinquent during the forbearance period. However, interest typically continues to accrue on most loans, increasing the total amount you'll eventually repay. The specific terms vary by loan type and lender.
For mortgage forbearance, servicers may offer several repayment structures:
- Lump sum repayment: Pay all missed payments at once when forbearance ends
- Repayment plan: Add a portion of missed payments to regular monthly bills
- Loan modification: Extend the loan term or adjust interest rates permanently
- Payment deferral: Move missed payments to the end of the loan term
Personal loan forbearance arrangements often mirror these structures, though terms may be more flexible with private lenders. The key is establishing clear expectations before entering any forbearance agreement.
Types of Loans Eligible for Forbearance
Not all loans qualify for forbearance, and eligibility requirements vary significantly by loan type. Understanding which programs apply to your specific debt helps you navigate the application process more effectively.
Mortgage Forbearance Programs
Mortgage forbearance became widely known during the COVID-19 pandemic, but programs existed long before. FHA loans, VA loans, and conventional mortgages backed by Fannie Mae or Freddie Mac all offer forbearance options, though specific terms differ.
HUD’s loss mitigation programs provide comprehensive resources for FHA borrowers facing hardship. These government-backed programs often include more generous terms than private mortgages, including extended forbearance periods and flexible repayment options.
The Fannie Mae servicing guide details specific procedures servicers must follow when granting forbearance. Borrowers with Fannie Mae loans benefit from standardized processes and clear documentation requirements.
| Loan Type | Typical Forbearance Period | Interest During Forbearance | Repayment Options |
|---|---|---|---|
| FHA Mortgage | Up to 12 months | Continues to accrue | Deferral, modification, repayment plan |
| Conventional Mortgage | 3-12 months | Continues to accrue | Lump sum, repayment plan, modification |
| Federal Student Loan | Typically 12 months | Varies by loan type | Added to principal or capitalized |
| Private Student Loan | Varies by lender | Usually accrues | Lender-specific terms |
| Personal Loan | Varies by lender | Usually accrues | Negotiated case-by-case |
Student Loan Forbearance Considerations
Federal student loans offer both mandatory and discretionary forbearance. Mandatory forbearance must be granted if you meet specific criteria, such as serving in a medical residency or teaching. Discretionary forbearance depends on your lender's approval and typically applies during financial hardship.
Federal Student Aid provides guidance on preparing for payments, especially relevant as borrowers transition from pandemic-era relief programs. Understanding forbearance as part of broader repayment strategies helps student loan borrowers manage long-term obligations.
Private student loans operate under different rules, with forbearance terms determined by individual lenders rather than federal regulations. These programs often have stricter qualification requirements and shorter forbearance periods.
Personal Loan Forbearance Options
Personal loans for home improvements, medical expenses, or education may qualify for forbearance through private lenders. Unlike government-backed mortgages or federal student loans, these agreements are typically negotiated directly with the lender. Standard Financial and other consumer lenders may offer hardship programs that function similarly to forbearance, providing temporary payment relief for qualified borrowers.
The flexibility of personal loan forbearance can be both an advantage and a challenge. While lenders may customize solutions to individual circumstances, terms vary widely, and documentation requirements differ by institution.
The Application Process and Requirements
Obtaining forbearance requires proactive communication with your lender or loan servicer. Waiting until you've already missed payments can complicate the process and potentially damage your credit.
Steps to Request Forbearance
- Contact your servicer immediately when you anticipate payment difficulties. Early communication demonstrates good faith and may preserve more options.
- Document your hardship with supporting materials such as termination letters, medical bills, or other evidence of financial difficulty.
- Submit a formal request following your lender's specific procedures. Some require online applications, while others accept phone requests.
- Review the agreement carefully before signing. Understand the forbearance period length, interest accrual terms, and repayment expectations.
- Maintain regular communication throughout the forbearance period to stay informed about upcoming obligations.
Documentation and Eligibility Criteria
Lenders typically require proof of hardship before granting forbearance. Common qualifying circumstances include:
- Sudden job loss or significant income reduction
- Medical emergencies or disability
- Natural disasters affecting your property or employment
- Military deployment or active duty service
- Death of a primary wage earner
Supporting documentation strengthens your application. Pay stubs, termination notices, medical bills, and bank statements help verify your financial situation and demonstrate genuine hardship rather than simple unwillingness to pay.
Timing and Strategic Considerations
The optimal time to request forbearance is before you miss any payments. Once an account becomes delinquent, your options may narrow, and credit damage may already be occurring. Proactive communication signals responsible financial behavior and often results in more favorable terms.
Consider whether forbearance truly serves your long-term interests. If your financial difficulty is temporary and you'll resume income soon, forbearance may be ideal. However, if your hardship appears long-term, exploring loan modification or other permanent solutions might prove more beneficial.
Financial Impact and Credit Implications
Understanding what is loan forbearance means grasping both its immediate benefits and potential long-term consequences. The relief it provides comes with trade-offs that borrowers must carefully evaluate.
Credit Reporting and Score Effects
Under normal circumstances, properly executed forbearance should not negatively impact your credit score. Experian explains how forbearance affects credit, noting that lenders typically report forbearance accounts as current, provided you comply with agreed terms.
CARES Act protections established important precedents for forbearance reporting, requiring servicers to maintain the account status that existed before forbearance. Even as pandemic-specific programs end, many lenders continue similar reporting practices for borrowers in approved forbearance programs.
However, beware of potential pitfalls:
- Forbearance may appear on credit reports even without negative marks
- Some lenders may view forbearance history negatively when evaluating new credit applications
- Missing payments before or after forbearance will damage credit scores
- Improper documentation can result in delinquency reporting
Interest Accrual and Total Repayment Costs
Most forbearance programs allow interest to continue accruing during the payment pause. This means your total loan balance increases, even though you're making no payments. Capitalization compounds this effect when unpaid interest is added to your principal balance, causing you to pay interest on interest.
For a $200,000 mortgage at 6% interest in 12-month forbearance, approximately $12,000 in interest would accrue. If capitalized, this increases your principal to $212,000, raising both your monthly payment and total interest paid over the loan's life.
Tax and Legal Considerations
Certain forbearance arrangements may trigger tax consequences. IRS guidance on mortgage modifications addresses safe harbors and reporting requirements when forbearance leads to principal reduction or debt forgiveness. While most simple forbearance agreements have no immediate tax impact, borrowers should consult tax professionals if their forbearance includes debt cancellation provisions.
Legal protections vary by loan type. Government-backed mortgages include specific borrower rights during forbearance, while private loans depend on contract terms and state law. Understanding your rights prevents servicer abuses and ensures proper implementation of forbearance terms.
Alternatives and Complementary Strategies
Forbearance isn't always the best solution for financial hardship. Evaluating alternatives ensures you choose the most effective strategy for your specific situation.
Income-Driven Repayment Plans
For federal student loans, income-driven repayment (IDR) plans may provide more sustainable long-term relief than forbearance. These plans cap monthly payments at a percentage of discretionary income and may lead to forgiveness after 20-25 years. Unlike forbearance, qualifying payments under IDR plans count toward forgiveness programs.
Federal Reserve research on student loan payments analyzes how forbearance affected household finances and spending patterns, providing valuable context for borrowers weighing payment strategies.
Loan Modification Programs
Permanent modifications change loan terms to create affordable payments without temporary relief periods. Modifications might reduce interest rates, extend loan terms, or convert variable rates to fixed rates. While qualification requirements are often stricter than forbearance, modifications provide long-term stability.
Homeowners struggling with mortgage payments should explore modification options through their servicer. FHA and other government programs offer specific modification tracks designed for borrowers who can't afford current payments but can sustain reduced obligations.
Refinancing Opportunities
When interest rates drop or credit improves, refinancing can lower monthly payments permanently. Unlike forbearance, refinancing doesn't create future repayment obligations or accrued interest. However, refinancing requires credit approval and may include closing costs or fees.
Personal loan borrowers may find refinancing particularly valuable if their credit has improved since origination. Lower rates or extended terms can significantly reduce monthly obligations while avoiding the deferred payment structure of forbearance.
Hardship Programs and Payment Plans
Many lenders offer hardship programs distinct from formal forbearance. These might include temporary interest rate reductions, fee waivers, or partial payment arrangements. While less comprehensive than full forbearance, hardship programs may better suit mild financial difficulties.
| Strategy | Best For | Credit Impact | Long-term Cost |
|---|---|---|---|
| Forbearance | Temporary hardship, expected income recovery | Minimal if properly managed | Higher due to interest accrual |
| Modification | Permanent payment reduction needs | May initially lower score | Potentially lower overall |
| Refinancing | Improved credit or lower rates available | Temporary inquiry impact | Potentially much lower |
| Income-Driven Repayment | Federal student loans, fluctuating income | None | Depends on forgiveness eligibility |
Regional Considerations for Southeastern Borrowers
Borrowers in Louisiana, Mississippi, Tennessee, and Georgia face unique economic conditions that influence forbearance decisions. Regional employment patterns, disaster risks, and state-specific regulations all affect how forbearance programs work in practice.
Natural Disaster Protections
Hurricane risks in Louisiana and Mississippi mean many homeowners periodically need disaster-related forbearance. Federal mortgage programs typically provide automatic forbearance eligibility for borrowers in declared disaster areas. Understanding these protections before disasters strike helps homeowners respond quickly when needed.
Storm-related damage may also affect personal loan payments, especially for home improvement loans financing property repairs. Lenders familiar with regional disaster patterns often maintain specialized forbearance programs for affected borrowers.
Economic Factors Affecting Forbearance
Brookings Institution research on household finances examines how relief programs including forbearance affected family balance sheets across different regions. Southeastern states showed varied recovery patterns, influencing optimal forbearance strategies for local borrowers.
Industry concentration matters too. Regions heavily dependent on tourism, energy, or manufacturing may experience coordinated economic downturns affecting multiple borrowers simultaneously. Understanding local economic trends helps lenders and borrowers anticipate forbearance needs.
State Regulations and Consumer Protections
While federal law governs most mortgage and student loan forbearance, state regulations affect personal loans and consumer lending. Georgia, Tennessee, Louisiana, and Mississippi each maintain distinct consumer protection statutes that may influence forbearance availability and terms.
State banking regulations also determine licensing requirements for lenders, which can affect the range of forbearance programs available. Working with established local lenders like Standard Financial ensures compliance with all applicable state and federal requirements.
Making Forbearance Work for Your Financial Future
Understanding what is loan forbearance provides the foundation, but successfully using it requires strategic planning and disciplined execution. Borrowers who approach forbearance thoughtfully maximize its benefits while minimizing long-term costs.
Creating a Post-Forbearance Plan
Before entering forbearance, develop a realistic plan for resuming payments. Calculate projected income, evaluate budget adjustments, and confirm your ability to handle the repayment structure. Wishful thinking causes many borrowers to accept repayment terms they ultimately can't sustain.
Consider these planning factors:
- Will your income return to pre-hardship levels or remain reduced?
- Can you adjust expenses to accommodate higher post-forbearance payments?
- Should you request loan modification instead if long-term income reduction is likely?
- What emergency fund can you build during forbearance to prevent future hardship?
Communication and Documentation Best Practices
Maintain detailed records of all forbearance communications. Save emails, note phone conversations with dates and representative names, and retain copies of all forbearance agreements. Documentation protects you if disputes arise about payment obligations or credit reporting.
Request written confirmation of all forbearance terms before the program begins. Verbal agreements provide inadequate protection if servicer errors occur or account transfers happen during forbearance.
Monitoring Your Credit and Accounts
Even when forbearance shouldn't hurt credit, monitoring ensures proper reporting. Check credit reports monthly during forbearance to catch errors quickly. Dispute inaccuracies immediately rather than waiting until you need new credit.
Verify that your servicer correctly records forbearance status and that no late payment marks appear during the protected period. Proactive monitoring prevents credit damage that might take months or years to repair.
Evaluating Forbearance Success
As your forbearance period ends, honestly assess whether it achieved its intended purpose. Did your financial situation improve sufficiently to resume payments? Did the temporary relief provide breathing room to restructure finances and build emergency savings?
If circumstances haven't improved adequately, communicate with your lender before forbearance ends. Extension requests or transitions to alternative programs work better when requested proactively rather than after missing the first post-forbearance payment.
Understanding what is loan forbearance and how to use it strategically can help you navigate financial challenges without derailing your long-term goals. Whether you're managing a temporary setback or need time to restructure your finances, forbearance offers valuable breathing room when used appropriately. If you're experiencing financial hardship and need guidance on forbearance or other relief options, Standard Financial offers personalized solutions across Louisiana, Mississippi, Tennessee, and Georgia, including flexible payment arrangements designed to help you maintain financial stability during difficult times.

No comment yet, add your voice below!