

Car insurance represents a significant expense for most households across Louisiana, Mississippi, Tennessee, and Georgia. Whether you're managing a tight budget or simply looking to optimize your monthly expenses, understanding how to lower your car insurance can free up funds for other financial priorities. The good news is that with the right strategies and knowledge, most drivers can reduce their premiums without sacrificing essential coverage. This comprehensive guide explores proven methods to cut your insurance costs while maintaining the protection you need on the road.
Understanding What Drives Your Premium
Insurance companies evaluate dozens of factors when calculating your rate. Your age, driving history, credit score, vehicle type, and location all play critical roles in determining what you pay each month. Understanding these variables helps you identify which areas offer the most opportunity for savings.
Key rating factors include:
- Driving record and claims history
- Annual mileage and commute distance
- Vehicle make, model, and safety features
- Coverage limits and deductible amounts
- Credit-based insurance score
- Geographic location and garaging address
The true cost of auto insurance varies significantly by state, with factors like state regulations, accident rates, and weather patterns affecting regional pricing. Drivers in metropolitan areas typically pay more than those in rural communities due to higher accident frequency and theft rates.
The Impact of Your Driving Record
Your driving history remains the single most influential factor under your control. Even one at-fault accident or moving violation can increase your premium by 20 to 40 percent for three to five years. Maintaining a clean record represents the foundation of how to lower your car insurance over time.
Shopping and Comparing Quotes Strategically
Most drivers leave money on the table by staying with the same carrier year after year. Insurance companies adjust their rates differently based on market conditions, risk models, and competitive positioning. What was the best rate three years ago may no longer be competitive today.
| Shopping Strategy | Potential Savings | Time Investment |
|---|---|---|
| Compare 3-5 carriers annually | 15-30% | 2-3 hours |
| Review policy every 6 months | 10-20% | 30 minutes |
| Use independent agents | 20-35% | 1-2 hours |
| Bundle home and auto | 15-25% | 1 hour |
Request quotes from at least three to five different insurers every year. Many consumers discover savings of several hundred dollars simply by switching carriers. The National Association of Insurance Commissioners provides consumer guidance on what to verify when comparing policies to ensure you're making apples-to-apples comparisons.
Timing Your Shopping
Insurance rates fluctuate throughout the year based on various factors. Shopping 15 to 30 days before your renewal date gives you time to compare without a coverage gap. Avoid waiting until the last minute, as rushed decisions often lead to overpaying.
Best times to shop:
- 30 days before renewal
- After paying off a vehicle loan
- When moving to a new address
- Following major life changes (marriage, retirement)
- After improving your credit score
Maximizing Available Discounts
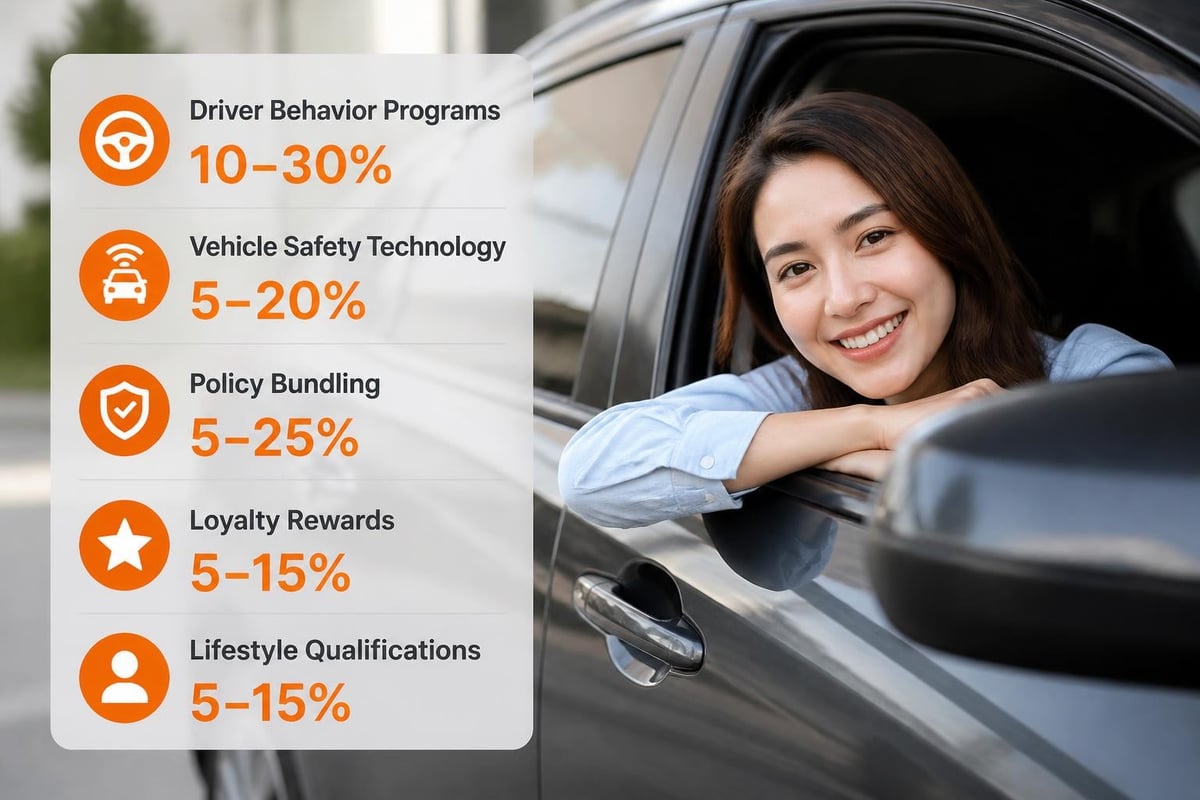
Understanding how to lower your car insurance requires knowing which discounts you qualify for and ensuring they're applied to your policy. The average driver qualifies for five to seven discounts but only receives credit for two to three.
Common discounts include good driver, multi-policy, multi-vehicle, good student, defensive driving, low mileage, paperless billing, pay-in-full, occupation-based, alumni associations, and safety features. Each carrier weights these differently, which is why comparison shopping matters so much.
Safety and Technology Discounts
Modern vehicles equipped with advanced safety features often qualify for meaningful discounts. Research from the Insurance Institute for Highway Safety shows that driver assistance features reduce claim frequency, which insurers reward with lower rates.
Anti-lock brakes, electronic stability control, forward collision warning, automatic emergency braking, blind spot monitoring, and lane departure warning all contribute to safer driving and potential premium reductions. When purchasing your next vehicle, consider how safety features affect long-term insurance costs.
Adjusting Your Coverage and Deductibles
One of the most direct ways to lower your premium involves reassessing your coverage levels and deductible amounts. While maintaining adequate protection is essential, many drivers carry more coverage than they need based on their current financial situation.
Deductible Strategy
Raising your deductible from $250 to $500 typically reduces your premium by 15 to 30 percent. Increasing it to $1,000 can cut costs by 30 to 40 percent. The key is ensuring you can comfortably afford the higher out-of-pocket expense if you need to file a claim.
| Deductible Amount | Annual Premium | Savings vs. $250 | Break-Even Period |
|---|---|---|---|
| $250 | $1,800 | Baseline | N/A |
| $500 | $1,440 | $360 (20%) | 8 months |
| $1,000 | $1,170 | $630 (35%) | 14 months |
| $2,000 | $990 | $810 (45%) | 26 months |
Build an emergency fund to cover your deductible before making this change. This ensures you won't need to seek emergency financing if an accident occurs. For many Standard Financial customers managing debt or working to improve their financial position, balancing deductible levels with emergency savings represents a critical decision.
Coverage for Older Vehicles
If you're driving an older vehicle worth less than $3,000 to $4,000, dropping collision and comprehensive coverage often makes financial sense. Consumer Reports recommends evaluating whether the annual premium plus deductible exceeds the vehicle's value.
Calculate your car's actual cash value using resources like Kelley Blue Book or NADA Guides. If the combined annual cost of collision and comprehensive coverage plus your deductible approaches or exceeds this value, liability-only coverage may be more economical.
Leveraging Usage-Based and Telematics Programs
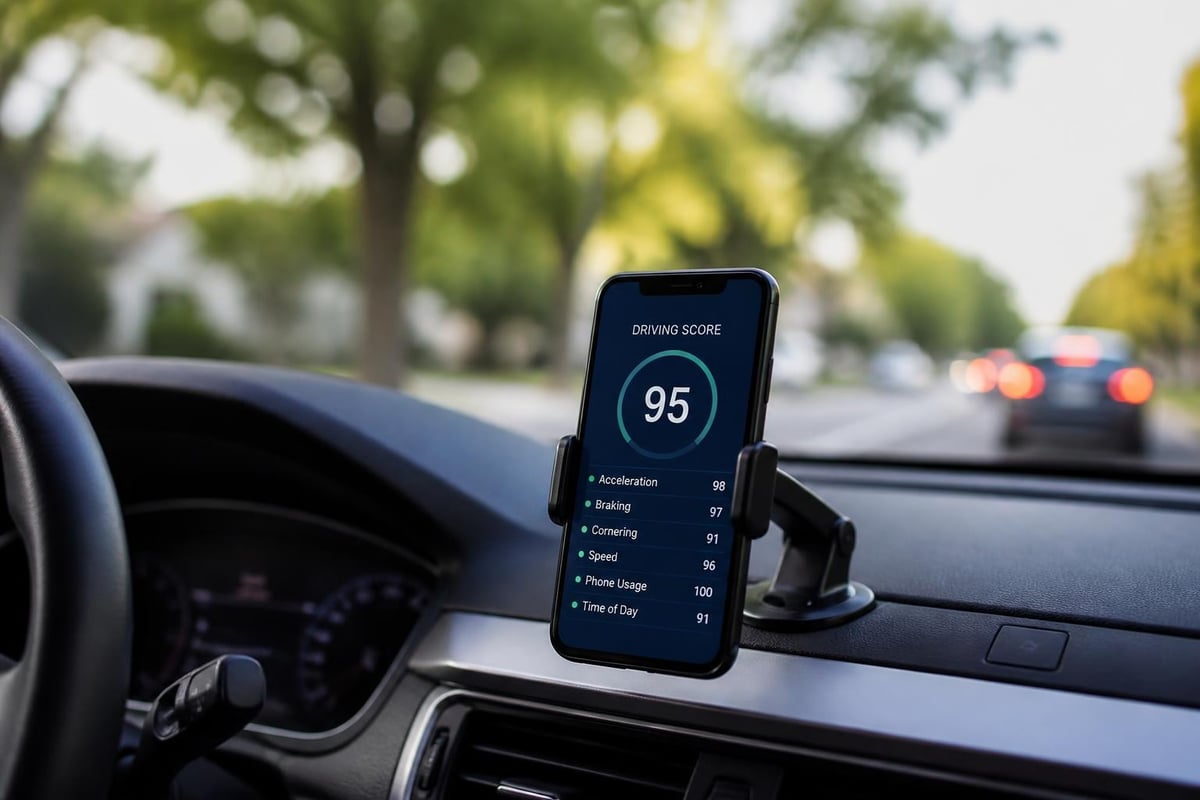
Modern technology enables insurers to base rates on actual driving behavior rather than statistical profiles. Usage-based insurance programs monitor your driving habits through smartphone apps or plug-in devices, offering discounts for safe driving patterns.
Monitored behaviors include:
- Hard braking frequency
- Rapid acceleration
- Cornering speed
- Time of day driving
- Total miles driven
- Phone use while driving
Good drivers typically save 10 to 30 percent through these programs, with some exceptional drivers earning discounts up to 40 percent. The initial enrollment often provides a small discount just for participating, making it risk-free to try.
Low Mileage Programs
If you drive fewer than 7,500 to 10,000 miles annually, low-mileage programs can deliver significant savings. Working from home, using public transportation, or living close to work all qualify you for these discounts. Some insurers now offer pay-per-mile policies where your premium directly correlates to actual miles driven.
Improving Your Credit and Payment Methods
In most states, insurance companies use credit-based insurance scores to help determine premiums. This score differs from your traditional credit score but draws from similar information. Improving your overall credit health can significantly impact how to lower your car insurance costs.
Credit Impact
Studies show drivers with excellent credit pay 50 to 70 percent less than those with poor credit, all other factors being equal. Focus on paying bills on time, reducing credit utilization, and addressing errors on your credit report.
Steps to improve insurance scoring:
- Pay all bills by the due date
- Keep credit card balances below 30% of limits
- Maintain a mix of credit types
- Avoid opening unnecessary new accounts
- Review credit reports for errors annually
For Standard Financial customers working to rebuild credit, each improvement in your credit profile can translate to lower insurance costs over time. The compound effect of better credit touches multiple areas of your financial life.
Payment Method Savings
Many insurers offer discounts for paying your premium in full rather than monthly installments. While this requires more cash upfront, the savings typically range from 5 to 10 percent annually. Automatic payments and paperless billing can add another 2 to 5 percent in combined discounts.
Bundling Policies and Group Affiliations
Multi-policy discounts remain one of the easiest ways to reduce your insurance costs. Combining your auto insurance with homeowners, renters, or umbrella policies with the same carrier typically generates 15 to 25 percent savings on the auto portion.
Additional bundling opportunities:
- Insuring multiple vehicles on one policy
- Adding teenage drivers to existing policies
- Combining life and auto insurance
- Motorcycle or RV coverage with auto
Professional associations, alumni groups, employers, and membership organizations frequently negotiate group rates with insurance carriers. Check whether your employer, university, or professional organization offers insurance programs. These group rates sometimes beat standard pricing by 10 to 15 percent.
Reducing Risk Through Strategic Choices
The decisions you make about where you live, what you drive, and how you use your vehicle all influence your rates. While you can't change everything, understanding these factors helps you make informed choices when opportunities arise.
Vehicle Selection
When purchasing your next car, research insurance costs before making a final decision. Vehicles with high theft rates, expensive repair costs, or powerful engines cost more to insure. Family sedans and minivans typically carry lower premiums than sports cars or luxury SUVs.
According to Highway Loss Data Institute research, vehicles equipped with crash-avoidance features reduce insurance claims. Factoring in long-term insurance savings can justify choosing models with advanced safety technology.
Garaging Location
Where you park your vehicle overnight affects your rate. A garaged vehicle in a low-crime neighborhood costs less to insure than street parking in a high-theft area. If you have access to off-street parking or a garage, ensure your insurer knows and credits you appropriately.
Moving to a different neighborhood or city can significantly impact premiums. Before relocating, request quotes using your new address to understand how geography affects your costs across Louisiana, Mississippi, Tennessee, and Georgia.
Maintaining Continuous Coverage
Allowing your insurance to lapse, even briefly, triggers higher rates when you reinstate coverage. Insurance companies view gaps as high-risk behavior, sometimes increasing premiums by 20 to 50 percent. Maintaining continuous coverage demonstrates responsibility and keeps your rates stable.
If you're storing a vehicle long-term or not driving temporarily, consider comprehensive-only coverage rather than canceling entirely. This protects against theft and damage while costing far less than full coverage and prevents a gap in your insurance history.
Life Changes That Affect Rates
Major life events often create opportunities to lower your premium. Getting married, retiring, completing college, or having children can all trigger discounts or rate reductions. Contact your insurer when these changes occur rather than waiting for renewal.
| Life Event | Typical Rate Impact | Action Required |
|---|---|---|
| Marriage | 5-15% decrease | Provide marriage certificate |
| Retirement | 10-20% decrease | Update occupation status |
| Good student (teen) | 15-25% decrease | Submit transcripts/GPA proof |
| Moving to suburbs | 10-30% decrease | Update garaging address |
| Paying off vehicle | 5-10% decrease | Drop required coverage levels |
Reviewing and Optimizing Annually
Learning how to lower your car insurance isn't a one-time task. The insurance landscape, your personal situation, and available discounts all evolve continuously. Schedule an annual review of your policy to ensure you're maximizing every opportunity.
Annual review checklist:
- Shop at least three competing carriers
- Verify all applicable discounts are applied
- Reassess coverage levels for older vehicles
- Update mileage estimates if driving patterns changed
- Review deductible amounts against emergency savings
- Confirm garaging address and vehicle use accuracy
- Check for new safety feature discounts
- Ask about loyalty or tenure-based discounts
Work with your insurance agent or company representative to walk through your policy line by line. Many discounts require you to ask rather than being automatically applied. NerdWallet’s comprehensive guide provides additional strategies for maximizing savings through active policy management.
Understanding State Requirements and Minimum Coverage
Each state mandates minimum liability coverage levels, but these minimums rarely provide adequate protection for most drivers. In Louisiana, Mississippi, Tennessee, and Georgia, understanding state requirements helps you balance legal compliance with financial protection.
While carrying only minimum coverage reduces your premium, it exposes you to significant financial risk if you cause a serious accident. Consider your assets, income, and potential liability when selecting coverage limits. The few hundred dollars saved on premiums could cost tens of thousands in an underinsured accident.
Umbrella Policy Considerations
For drivers with significant assets or income, an umbrella policy provides additional liability coverage beyond auto insurance limits. These policies cost surprisingly little (often $200 to $400 annually for $1 million in coverage) and protect your financial future. While this adds to total insurance costs, it prevents catastrophic financial loss.
Taking control of your car insurance costs requires understanding the factors that drive your premium and actively pursuing every available savings opportunity. By shopping regularly, maximizing discounts, adjusting coverage strategically, and maintaining good credit and driving habits, most drivers can reduce their annual insurance expenses by hundreds or even thousands of dollars. Those savings can help address other financial priorities, whether paying down debt, building emergency savings, or investing in your future. If you're working to improve your overall financial situation and need flexible financing options to consolidate debt or handle unexpected expenses, Standard Financial offers personalized lending solutions across Louisiana, Mississippi, Tennessee, and Georgia, with a commitment to helping clients achieve their financial goals regardless of past credit challenges.

No comment yet, add your voice below!