

Purchasing a recreational vehicle represents a significant investment for families and adventurers across the Southeast and beyond. Whether you're considering a Class A motorhome for cross-country travel or a modest travel trailer for weekend getaways, understanding your financing options is essential. A loan for an RV functions differently from traditional auto loans in several important ways, including term length, interest rates, and collateral considerations. With the right preparation and knowledge of lending structures, you can secure financing that fits your budget while protecting your financial future.
Understanding RV Loan Basics
A loan for an RV typically carries longer repayment terms than standard vehicle financing, often ranging from 10 to 20 years depending on the purchase price and lender requirements. This extended timeline reflects the substantial cost of recreational vehicles, which can range from $10,000 for used travel trailers to well over $300,000 for luxury motorhomes.
Lenders classify RV loans in different categories based on the vehicle type. Motorized RVs including Class A, B, and C vehicles are generally treated as specialized vehicle loans, while towable trailers and fifth wheels may be financed through chattel loans. The distinction matters because it affects interest rates, down payment requirements, and potential tax benefits.
Key Factors Affecting RV Loan Approval
Credit score remains the most significant factor in securing favorable loan terms. Borrowers with scores above 700 typically qualify for the lowest interest rates, while those with challenged credit histories may still obtain approval with higher rates or larger down payments. Many lenders, including those specializing in consumer lending, work with borrowers across the credit spectrum.
Important approval considerations include:
- Debt-to-income ratio below 43% preferred by most lenders
- Employment stability and verifiable income sources
- Down payment amount (typically 10-20% of purchase price)
- Age and condition of the RV being financed
- Intended use (full-time residence versus recreational)
The vehicle's value directly impacts loan availability. Lenders may hesitate to finance older RVs, particularly those over 10-15 years old, due to depreciation concerns and increased maintenance risks.
Choosing Between Secured and Unsecured RV Financing
Most RV purchases involve secured loans where the vehicle itself serves as collateral. This arrangement typically offers lower interest rates compared to unsecured personal loans because the lender maintains the right to repossess the RV if payments cease. According to research on vehicle lending practices, understanding your obligations and risks is crucial before signing any financing agreement.
Secured RV loans require comprehensive insurance coverage throughout the loan term. Your lender will mandate collision and comprehensive coverage to protect their investment, which adds to your monthly ownership costs. For detailed information about coverage requirements, RV insurance options explain the various protection levels available.
Unsecured Personal Loans for Smaller RVs
For less expensive RVs or travel trailers under $25,000, unsecured personal loans may provide a viable alternative. These loans don't use the RV as collateral, which means faster approval processes and no risk of repossession. However, they come with trade-offs.
| Feature | Secured RV Loan | Unsecured Personal Loan |
|---|---|---|
| Interest Rate | 4-9% typical | 8-18% typical |
| Loan Term | 10-20 years | 2-7 years |
| Down Payment | Usually required | Often not required |
| Insurance Requirement | Comprehensive mandatory | Optional |
| Approval Speed | 3-7 days | 1-3 days |
The shorter terms and higher rates on unsecured loans result in larger monthly payments, but you'll pay less total interest over the loan's lifetime. This option works well for buyers with strong credit who want to avoid the complexity of secured financing.
New Versus Used RV Financing
The condition and age of your chosen recreational vehicle significantly affects financing terms. New RVs typically qualify for the best interest rates because they hold value better and come with manufacturer warranties. According to RV shipment data, industry production trends influence both pricing and availability, which directly impact financing opportunities.
Used RV loans generally carry interest rates 1-3 percentage points higher than new vehicle financing. Lenders view older RVs as higher risk due to potential mechanical issues and faster depreciation. Many financial institutions limit used RV financing to vehicles less than 10 years old.
Dealer Financing Versus Independent Lenders
RV dealerships often partner with multiple lenders to offer on-site financing, which provides convenience but may not deliver the best rates. Understanding consumer protection rules helps buyers navigate dealer financing offers and recognize potential issues before committing.
Comparing your options requires:
- Obtaining pre-approval from your bank or credit union
- Requesting dealer financing quotes from at least two lenders
- Comparing APRs, loan terms, and total interest paid
- Reading all documentation carefully before signing
- Verifying there are no prepayment penalties
Independent lenders and consumer finance companies may offer more flexibility for borrowers with credit challenges. These institutions often consider factors beyond credit scores, including employment history and overall financial stability.
Calculating Your RV Loan Costs
Understanding the true cost of a loan for an RV extends beyond the monthly payment. The total amount you'll repay includes principal, interest, insurance, registration fees, and maintenance reserves. Creating a comprehensive budget prevents financial strain and ensures you can enjoy your RV without stress.
Monthly Payment Factors
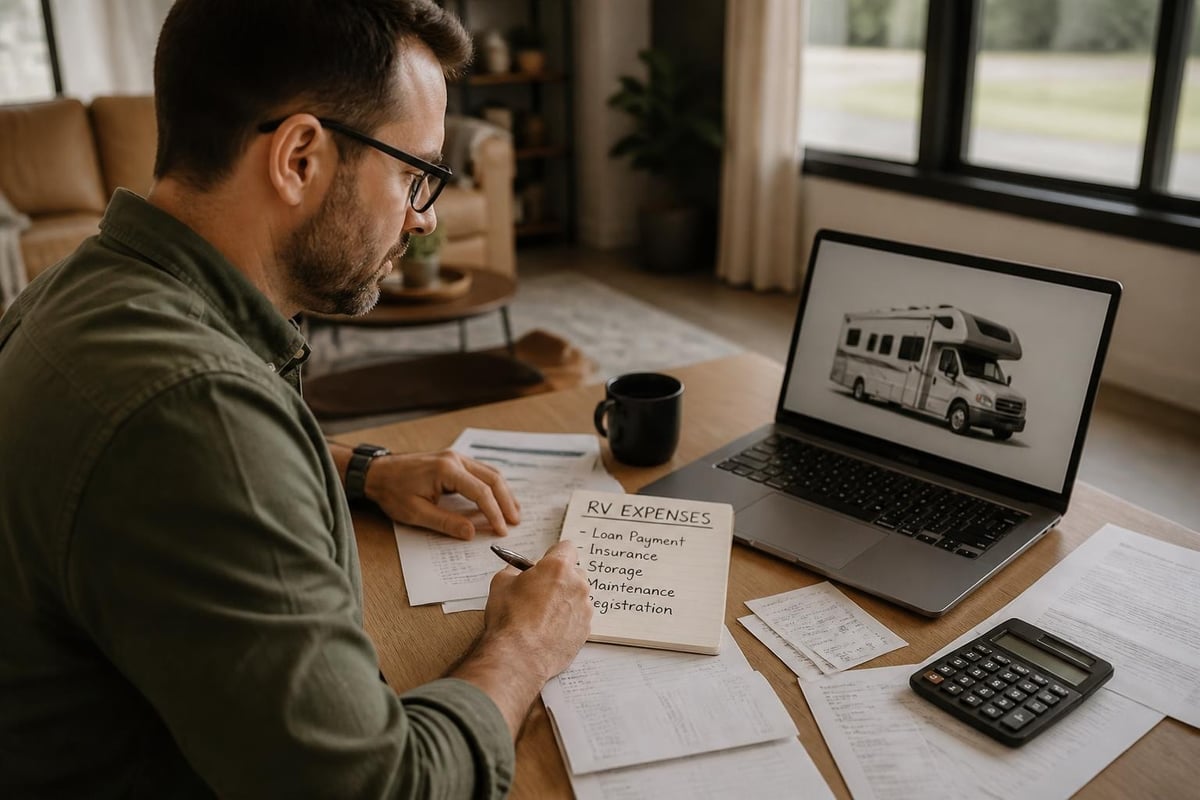
A $50,000 RV financed at 6.5% interest over 15 years results in a monthly payment of approximately $435. The same loan over 10 years increases the payment to $569 but saves over $11,000 in total interest. Using online calculators helps visualize how different terms affect both monthly budgets and long-term costs.
Additional monthly expenses typically include:
- Insurance premiums: $100-$300 depending on coverage and RV value
- Storage fees: $50-$200 if not stored at home
- Maintenance reserve: $50-$150 for routine service and repairs
- Registration and licensing: varies by state, typically annual
These supplementary costs can add $200-$800 to your monthly RV ownership expenses beyond the loan payment itself. Factoring these into your budget prevents surprises and ensures sustainable ownership.
Tax Implications and Deductions
One unique advantage of RV financing involves potential tax deductions. If your recreational vehicle qualifies as a second home under IRS guidelines, the interest paid on your loan may be tax-deductible. The IRS guidance on home classifications explains specific requirements, including that the RV must have sleeping, cooking, and toilet facilities.
This deduction applies only to loans secured by the RV as collateral and requires itemizing deductions on your tax return. Given recent increases to standard deduction amounts, consult a tax professional to determine if itemizing benefits your specific situation. The potential savings can be substantial, particularly for higher-income borrowers in elevated tax brackets.
Documentation Requirements
To claim RV loan interest as a deduction, maintain careful records including loan statements, proof of payment, and documentation that the RV qualifies as a dwelling. Your lender should provide Form 1098 if the loan meets IRS requirements for reportable mortgage interest.
Finding the Right Loan Term
Selecting an appropriate loan term for an RV balances monthly affordability with total interest costs. While 20-year terms minimize monthly payments, they result in paying significantly more interest over the loan's life. Conversely, shorter terms build equity faster but require larger monthly commitments.
| Loan Term | $60,000 @ 7% APR | Monthly Payment | Total Interest Paid |
|---|---|---|---|
| 10 years | $697 | $83,640 | $23,640 |
| 15 years | $539 | $97,020 | $37,020 |
| 20 years | $465 | $111,600 | $51,600 |
The difference between a 10-year and 20-year term amounts to nearly $28,000 in additional interest. However, the monthly payment flexibility of longer terms helps many buyers qualify for financing and maintain comfortable budgets for other expenses.
Refinancing Opportunities
As your financial situation improves or interest rates decline, refinancing your RV loan can reduce monthly payments or shorten the loan term. Most lenders allow refinancing after 12-24 months of on-time payments. This strategy works particularly well for borrowers who initially secured financing with challenged credit but have since improved their scores.
Special Considerations for Full-Time RVers
If you plan to live in your RV full-time, financing options and requirements may differ from recreational use. Some lenders offer specialized programs for full-timers, recognizing that these buyers need larger, more durable units. For comprehensive guidance on selecting an appropriate RV, Consumer Reports’ motorhome guide provides independent analysis of various models and ownership considerations.
Full-time living typically requires Class A motorhomes or large fifth wheels, with purchase prices often exceeding $100,000. These higher loan amounts may necessitate larger down payments and more stringent income verification. However, the ability to treat the RV as your primary residence opens additional tax benefits and financing structures.
Documentation for Full-Timer Loans
Lenders may request additional documentation proving full-time status, including:
- Termination of traditional housing lease or mortgage
- Domicile establishment in an RV-friendly state
- Mail forwarding service registration
- Enhanced insurance coverage for full-time dwelling use
- Larger emergency fund or cash reserves
These requirements protect both borrower and lender by ensuring the buyer can sustain full-time RV living financially.
Improving Your Chances of Approval
Borrowers with credit challenges can take specific steps to improve approval odds for a loan for an RV. Many consumer lenders evaluate applicants holistically rather than relying solely on credit scores. This approach considers your complete financial picture, including income stability, existing debt obligations, and demonstrated responsibility.
Actionable steps to strengthen your application:
- Pay down existing revolving debt to improve utilization ratios
- Correct any errors on credit reports before applying
- Gather documentation of steady employment and income
- Save a larger down payment to reduce loan-to-value ratio
- Consider a co-signer with stronger credit if appropriate
Transparency with lenders about past credit issues often works in your favor. Explaining circumstances that led to previous financial difficulties, particularly if they were temporary or beyond your control, helps underwriters understand your full situation.
Understanding Loan-to-Value Ratios
Lenders use loan-to-value (LTV) ratios to assess risk on secured RV loans. This calculation divides the loan amount by the RV's appraised value. Lower LTV ratios indicate less risk for lenders and typically result in better interest rates for borrowers.
Most lenders prefer LTV ratios below 80% for RV financing. For a $40,000 RV, this means financing no more than $32,000 and providing at least $8,000 as a down payment. Exceeding 80% LTV is possible but usually requires higher interest rates or additional approval criteria.
How LTV Affects Interest Rates
The relationship between LTV and interest rates follows a predictable pattern. Every 10% increase in LTV above 80% may add 0.5-1.0% to your interest rate. On a $50,000 loan over 15 years, even a 0.5% rate increase adds approximately $2,000 in total interest costs.
For buyers comparing financing structures similar to manufactured housing, understanding LTV standards across different collateral types provides useful context for RV loan expectations.
Preparing for the Application Process
Gathering documentation before applying for a loan for an RV accelerates approval and demonstrates financial preparedness. Lenders require specific information to verify your identity, income, employment, and creditworthiness. Having these materials ready streamlines the process significantly.
Essential documents typically include:
- Government-issued photo identification
- Recent pay stubs or income verification (last 2-3 months)
- Previous year's tax returns for self-employed applicants
- Bank statements showing cash reserves
- Information about the specific RV you intend to purchase
- Proof of residence (utility bills or lease agreement)
Self-employed borrowers face additional documentation requirements, including profit and loss statements and business bank account records. Preparing these materials in advance prevents delays during underwriting.
Comparing Lender Options
Not all lenders offer RV financing, and those that do vary significantly in their terms, rates, and borrower requirements. Evaluating multiple options ensures you secure the most favorable terms for your situation. When considering the RV buying process, financing represents just one component of a comprehensive purchase strategy.
National banks, regional credit unions, specialized RV lenders, and consumer finance companies each bring different strengths to the market. Credit unions often provide competitive rates for members, while consumer lenders may show greater flexibility for applicants with credit challenges.
Questions to Ask Potential Lenders
Before committing to any loan, obtain clear answers to these critical questions:
- What is the exact APR, including all fees and charges?
- Are there prepayment penalties if I pay off the loan early?
- What insurance coverage levels are required?
- How long does the approval process typically take?
- What happens if I need to defer a payment due to emergency?
Understanding these details prevents surprises and helps you select the lender whose policies align best with your financial circumstances and risk tolerance.
Protecting Yourself During RV Financing
Consumer protection extends throughout the RV financing process. Understanding your rights and recognizing common pitfalls helps you avoid predatory lending practices and unfavorable terms. Federal regulations require clear disclosure of loan terms, and you have the right to shop for better rates even after receiving initial approval.
Never sign financing documents you don't fully understand. Requesting time to review paperwork or having an attorney examine complex contracts protects your interests. Legitimate lenders appreciate informed borrowers and willingly answer questions about terms and conditions.
Red Flags in RV Financing Offers
Be cautious of lenders or dealers who:
- Pressure you to sign documents immediately without review time
- Refuse to provide written loan terms before signing
- Offer "guaranteed approval" regardless of credit history
- Suggest misrepresenting income or employment information
- Add unexpected fees not disclosed during initial discussions
These warning signs indicate potentially predatory practices that could result in unfavorable terms or even fraud. Walking away from suspicious offers protects your financial wellbeing.
Securing a loan for an RV requires careful planning, comparison shopping, and realistic budgeting that accounts for all ownership costs. By understanding how term length, interest rates, and down payments affect your total investment, you can make informed decisions that support both your adventure goals and long-term financial health. Standard Financial offers flexible financing solutions for consumers across Louisiana, Mississippi, Tennessee, and Georgia, including those rebuilding their credit. Contact a branch office today to explore personalized loan options that fit your RV ownership dreams and budget.

No comment yet, add your voice below!