

Credit inquiries play a significant role in your financial profile, yet many consumers remain uncertain about how many is acceptable. If you're planning to apply for a personal loan, refinance existing debt, or seek financing for home improvements or medical expenses, understanding how many credit inquiries is too many can help you protect your credit score while still accessing the funds you need. The answer depends on several factors, including the type of inquiries, the timeframe in which they occur, and your overall credit profile.
Understanding Credit Inquiry Types
Before addressing how many credit inquiries is too many, it's essential to distinguish between the two main categories of credit checks. Each type affects your credit differently and serves distinct purposes in the lending ecosystem.
Hard Inquiries and Their Impact
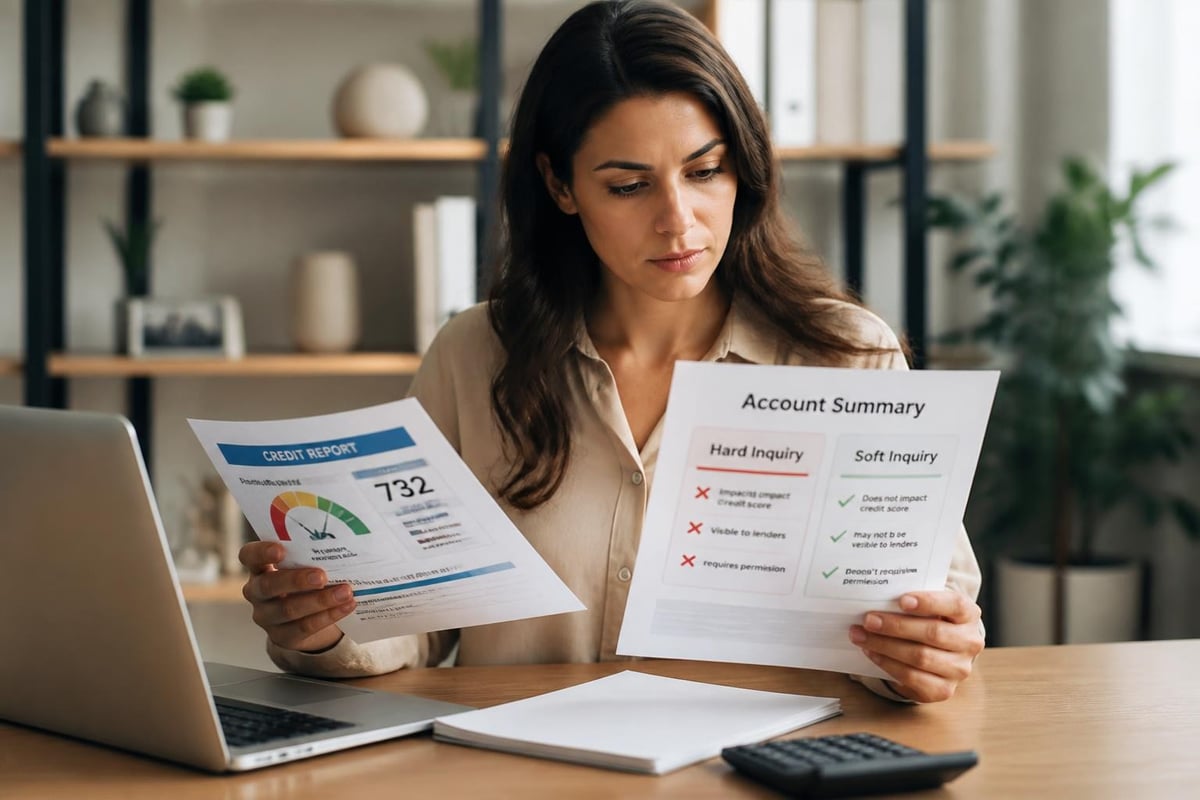
Hard inquiries occur when a lender reviews your credit report to make a lending decision after you've applied for credit. These include applications for personal loans, credit cards, auto financing, mortgages, and other credit products. Hard inquiries remain on your credit report for up to two years, though their impact on your credit score typically diminishes after the first year.
Each hard inquiry can reduce your credit score by approximately three to five points, though the exact impact varies based on your overall credit profile. Consumers with thin credit files or shorter credit histories often experience more significant point reductions than those with established credit histories.
Soft Inquiries and Credit Monitoring
Soft inquiries happen when you check your own credit, when lenders pre-approve you for offers, or when employers conduct background checks. These credit checks have no effect on your credit score and can occur without your explicit permission in some cases. You can check your own credit as often as you'd like through various monitoring services without any negative consequences.
The Threshold Question: Defining "Too Many"
Determining how many credit inquiries is too many requires examining both quantitative guidelines and qualitative context. Lenders and credit scoring models evaluate inquiry frequency as one indicator of credit risk.
Industry Standards and Benchmarks
Most financial experts agree that six or more hard inquiries within a 12-month period raises red flags for lenders. According to FICO® scoring methodology, multiple inquiries can signal financial distress or overextension, suggesting you're desperately seeking credit or taking on more debt than you can manage.
However, the "too many" threshold isn't absolute. Consider these benchmarks:
- 1-2 inquiries per year: Generally considered safe and normal credit-seeking behavior
- 3-4 inquiries per year: Acceptable, especially if clustered within rate-shopping windows
- 5-6 inquiries per year: Beginning to raise concerns among some lenders
- 7+ inquiries per year: Often viewed as high-risk behavior indicating financial stress
Context Matters More Than Numbers
The context surrounding your inquiries matters significantly. Two borrowers with identical inquiry counts may present vastly different risk profiles. A consumer with four inquiries spread across 12 months while maintaining perfect payment history appears far less risky than someone with four inquiries in one month alongside recent late payments.
| Factor | Lower Risk Profile | Higher Risk Profile |
|---|---|---|
| Timing | Inquiries spread across 12 months | Multiple inquiries within days/weeks |
| Purpose | Rate shopping for single purchase | Applications across various credit types |
| Credit History | Established history, good payment record | Thin file or recent negative marks |
| Account Opening | One or two new accounts | Multiple new accounts opened |
Rate Shopping and Special Protections
Credit scoring models recognize that savvy consumers shop for the best rates when making major purchases. This reality has led to built-in protections that address the question of how many credit inquiries is too many when you're comparison shopping.
The Shopping Window Concept
FICO® and VantageScore credit scoring models treat multiple inquiries for the same type of loan within a specific timeframe as a single inquiry. For mortgages, auto loans, and student loans, inquiries within a 14 to 45-day window (depending on the scoring model version) count as one inquiry. This protection allows you to compare offers from multiple lenders without severely damaging your credit score.
For example, if you're seeking financing for home improvements through Standard Financial and want to compare rates with other lenders, submitting applications within a two-week period typically results in minimal score impact. The scoring model recognizes you're making one borrowing decision, not seeking multiple new credit lines.
Exceptions to Shopping Window Rules
Not all credit applications receive shopping window treatment. Credit card inquiries are typically counted individually, regardless of timing. This means applying for three credit cards in one week results in three separate inquiries affecting your score. Personal loans fall into a gray area, with some newer scoring models offering limited shopping window protection.
How Inquiries Factor Into Credit Scores
Understanding the weight of inquiries in credit scoring algorithms helps contextualize how many credit inquiries is too many for your specific situation.
The 10% Factor in FICO® Scores
Inquiries and new credit accounts together comprise approximately 10% of your FICO® Score. This category, called "new credit," is the smallest of the five scoring factors. For comparison:
- Payment history: 35%
- Amounts owed: 30%
- Length of credit history: 15%
- Credit mix: 10%
- New credit (including inquiries): 10%
While 10% may seem minor, those points matter significantly when you're on the cusp of a better interest rate tier or loan approval threshold. A 15-point drop from excessive inquiries could move you from "good" to "fair" credit territory.
Inquiry Impact Over Time
The scoring impact of hard inquiries diminishes progressively. Recent CFPB data on inquiry activity shows that while inquiries remain visible for 24 months, most scoring models only consider inquiries from the past 12 months when calculating your score. After one year, that inquiry from your medical loan application likely has zero ongoing impact, even though it remains on your report.
Warning Signs You've Reached "Too Many"
Several indicators suggest you've crossed the threshold and accumulated too many credit inquiries for your financial health.
Loan Application Denials
If lenders cite "too many recent inquiries" as a reason for denial, you've definitively reached "too many" for that particular lender's risk tolerance. Different lenders maintain varying thresholds, but denial based on inquiry volume alone signals you should pause before submitting additional applications.
Declining Credit Score Trends
Monitor your credit score monthly through free services or your credit card provider. If you notice a steady downward trend correlating with credit applications, you're likely experiencing inquiry-related score suppression. According to Bankrate’s analysis, consumers with already-lower scores tend to experience more significant drops from each additional inquiry.
Reduced Pre-Approval Offers
A sudden decrease in pre-approved credit offers may indicate that creditors view your inquiry activity as concerning. Lenders use inquiry data to identify potentially risky borrowers even before you apply, adjusting their marketing accordingly.
Strategic Approaches to Managing Inquiries
Knowing how many credit inquiries is too many enables you to develop strategies that balance your need for credit access with score protection.
Timing Your Applications Wisely
Plan major credit applications strategically rather than applying impulsively. If you need financing for both home improvements and medical expenses, consider whether you can consolidate these needs into a single personal loan rather than pursuing separate credit products. Standard Financial's flexible financing options often allow borrowers to address multiple financial needs through one application.
Best practices for application timing:
- Research lenders thoroughly before applying
- Use pre-qualification tools when available (soft inquiries only)
- Consolidate rate shopping into narrow time windows
- Space out applications for different credit types by several months
- Avoid applying for credit within 6-12 months before a major purchase like a home
Building Credit Resilience
Your existing credit profile determines how much damage inquiries can inflict. Consumers with scores above 750 and diverse, well-managed credit accounts can typically withstand more inquiries than those with scores below 650 or limited credit histories.
Strengthen your credit foundation through:
- Consistent on-time payments: This 35% scoring factor outweighs inquiry impact
- Low credit utilization: Keeping balances below 30% of limits
- Account age preservation: Avoiding unnecessary account closures
- Credit mix diversity: Maintaining both revolving and installment accounts
Special Considerations for Borrowers With Credit Challenges
For consumers rebuilding credit or those with past credit issues, the question of how many credit inquiries is too many requires additional nuance. Standard Financial specializes in working with clients across the credit spectrum, including those recovering from financial setbacks.
Higher Vulnerability to Inquiry Impact
Borrowers with credit scores below 650 experience disproportionate score drops from hard inquiries. While someone with a 780 score might lose three points from an inquiry, a borrower at 620 could lose eight to ten points from the same pull. This disparity means those who most need credit access must exercise greater caution with applications.
The Catch-22 of Credit Building
Credit-challenged borrowers often face a paradox: they need new credit to rebuild their scores, but the inquiries from seeking that credit temporarily lower their scores further. The solution lies in being highly selective about applications and focusing on lenders who specialize in working with non-prime borrowers.
| Approach | Impact on Inquiries | Credit Building Effectiveness |
|---|---|---|
| Multiple card applications | High inquiry count | Risky, often counterproductive |
| Secured credit card | Single inquiry | Moderate, steady building |
| Credit-builder loan | Single inquiry | Excellent, demonstrates installment history |
| Personal loan from specialist lender | Single inquiry | Good, addresses immediate needs |
When Inquiries Reflect Legitimate Credit Errors
Not all inquiries on your credit report are legitimate. FTC research on credit reporting accuracy has documented cases where unauthorized inquiries appear on consumer reports due to identity theft, clerical errors, or lender mistakes.
Disputing Inaccurate Inquiries
If you notice hard inquiries you didn't authorize, you have the right to dispute them with the credit bureaus. Consumer Reports research on credit report accuracy found that inquiry-related errors are among the issues consumers successfully dispute most frequently.
Submit disputes in writing to each bureau reporting the unauthorized inquiry, providing documentation that you didn't apply for credit with that lender. The bureau must investigate within 30 days and remove inquiries they cannot verify.
Identity Theft and Inquiry Monitoring
An unexpected spike in hard inquiries often serves as an early warning sign of identity theft. If your credit report suddenly shows multiple inquiries from lenders you've never contacted, especially for credit types you wouldn't typically seek, take immediate action:
- File an identity theft report with the FTC
- Place fraud alerts on your credit reports
- Contact each lender showing inquiries to report the fraud
- Monitor your reports closely for new unauthorized activity
- Consider a credit freeze to prevent new account openings
Inquiry Impact Across Different Lending Products
The tolerance for how many credit inquiries is too many varies significantly by the type of credit you're seeking and the lender's risk assessment approach.
Mortgage Lending Standards
Mortgage lenders typically scrutinize inquiry history more intensely than other creditors because of the loan size and duration. However, they also understand rate shopping is standard practice. Expect mortgage underwriters to ask about recent inquiries, particularly those that resulted in new accounts not reflected in your debt-to-income calculations.
Auto Financing Flexibility
Auto lenders generally show more flexibility regarding recent inquiries, especially when they occurred within recognized shopping windows. The existence of these protections reflects industry acknowledgment that car buyers routinely compare dealer financing, manufacturer incentives, and third-party loans.
Personal Loan Considerations
Personal loan lenders vary widely in their inquiry sensitivity. Some online lenders approve applicants with numerous recent inquiries, while traditional banks may decline based on three or four inquiries in six months. Lenders specializing in consumers with credit challenges, like Standard Financial, evaluate inquiry patterns within the broader context of your financial situation rather than applying rigid thresholds.
Long-Term Inquiry Strategy and Credit Health
Managing inquiries effectively requires viewing credit decisions through a long-term lens rather than seeking short-term convenience at the expense of your credit profile.
The Two-Year Perspective
Since inquiries remain visible for two years, consider how today's application will appear on your credit report when you need financing 12 or 18 months from now. If you anticipate major credit needs like buying a home or starting a business, minimize non-essential inquiries in the preceding 12 months.
Creating a Credit Application Plan
Develop a personal policy for credit applications that aligns with your financial goals:
- Define your needs clearly: Distinguish between necessary credit and wants
- Set inquiry limits: Perhaps no more than three hard pulls per year outside of specific shopping windows
- Use pre-qualification: Take advantage of soft-pull tools to gauge approval odds
- Space applications strategically: Allow several months between unrelated credit applications
- Track your inquiries: Review your credit reports quarterly to monitor inquiry accumulation
The question of how many credit inquiries is too many ultimately depends on your individual circumstances, credit goals, and the specific lenders you approach. While general guidelines suggest six or more inquiries in 12 months raises concerns, context matters enormously. Smart consumers balance their need for credit access with strategic inquiry management, understanding that protecting their credit score requires thoughtful planning rather than reactive applications.
Managing credit inquiries strategically protects your financial options while ensuring you can access necessary financing when life demands it. Whether you need funds for medical expenses, home improvements, or education, understanding inquiry thresholds helps you make informed decisions. Standard Financial works with clients across Louisiana, Mississippi, Tennessee, and Georgia to provide flexible financing solutions, even for those with past credit challenges, helping you achieve your goals while building long-term financial health.

No comment yet, add your voice below!