

When your beloved pet needs surgery, the emotional stress is often compounded by financial concerns. Veterinary surgical procedures can range from a few hundred dollars for minor interventions to several thousand for complex operations. Understanding your financing options before an emergency arises helps you make informed decisions quickly when your pet's health is at stake. Whether you're facing an unexpected injury or planning for a necessary procedure, knowing how to secure a loan for pet surgery can mean the difference between immediate treatment and delayed care.
Understanding the Cost of Veterinary Surgery
Veterinary surgical costs vary significantly based on the procedure's complexity, your location, and the level of specialty care required. Routine procedures such as spay or neuter operations typically cost between $200 and $500, while emergency surgeries for conditions like bloat, foreign body removal, or trauma can exceed $3,000 to $7,000.
Orthopedic surgeries, such as ACL repairs or hip replacements, frequently range from $1,500 to $6,000 per procedure. Cancer surgeries and oncological treatments represent some of the highest expenses, often requiring not just the initial operation but follow-up care, chemotherapy, or radiation. Research on treatment options and costs shows that comprehensive cancer care can easily reach $10,000 or more.
Factors That Influence Surgical Costs
Several variables impact the final bill for your pet's surgery:
- Geographic location: Urban veterinary practices and specialty hospitals typically charge more than rural general practitioners
- Specialist vs. general veterinarian: Board-certified surgeons command premium fees for their expertise
- Emergency timing: After-hours, weekend, and holiday procedures often carry surcharges of 50-100%
- Pre-operative testing: Blood work, imaging (X-rays, ultrasounds, CT scans), and consultations add to the baseline cost
- Post-operative care: Hospitalization, pain management, antibiotics, and follow-up visits extend expenses beyond the surgery itself
Understanding these cost drivers helps you budget appropriately and communicate effectively with your veterinarian about necessary versus optional components of care.
Pet Insurance Coverage and Limitations
Pet insurance has grown substantially in recent years, yet penetration remains relatively low. According to industry data from NAPHIA, only a small percentage of American pets are insured, leaving most owners responsible for full out-of-pocket expenses when surgery becomes necessary.
For those with coverage, understanding policy limitations is crucial. Most pet insurance policies operate on a reimbursement model, meaning you pay the veterinary bill upfront and file a claim afterward. This creates an immediate cash-flow challenge even when you have insurance.
| Coverage Aspect | Typical Terms | Financial Impact |
|---|---|---|
| Deductible | $250-$1,000 annually | Must pay before reimbursement begins |
| Reimbursement rate | 70-90% of covered costs | You pay 10-30% plus non-covered items |
| Annual maximum | $5,000-unlimited | Caps total yearly reimbursement |
| Waiting periods | 14 days for illness, 6 months for orthopedic | Pre-existing conditions excluded |
Even with insurance, you often need immediate financing to bridge the gap between paying the veterinary hospital and receiving your reimbursement check weeks later.
Personal Loan Options for Pet Surgery
A loan for pet surgery through a personal loan product offers several advantages over specialized veterinary financing. Personal loans provide a lump sum you can use for any purpose, giving you flexibility to cover not just the surgery but also pre-operative testing, medications, and follow-up care.
Secured vs. Unsecured Personal Loans
Unsecured personal loans don't require collateral, making them accessible if you don't own property or prefer not to risk assets. Lenders evaluate your creditworthiness based on income, employment history, and credit score. Interest rates typically range from 6% to 36%, depending on your credit profile.
Secured personal loans use collateral such as a vehicle, savings account, or other valuable property to guarantee the loan. Because the lender's risk is reduced, secured loans often carry lower interest rates and may be available to borrowers with less-than-perfect credit histories.
For residents of Louisiana, Mississippi, Tennessee, and Georgia, regional lenders often provide more flexible terms than large national banks, particularly for borrowers who have experienced past credit challenges.
Application Process and Timeline
Most personal loan applications can be completed in 30 minutes or less. You'll need to provide:
- Proof of identity: Driver's license or state ID
- Income verification: Recent pay stubs, tax returns, or bank statements
- Employment information: Current employer contact details and length of employment
- Credit authorization: Permission for the lender to check your credit history
Many lenders can provide approval decisions within 24 hours, with funds disbursed to your account in 1-3 business days. This timeline makes personal loans viable even for urgent surgical needs.
Medical Credit Cards and Veterinary Payment Plans
Specialized medical financing products have become commonplace in veterinary practices. These options deserve careful consideration, as they operate differently from traditional loans.
How Medical Credit Cards Work
Promotional medical credit cards often advertise "interest-free" periods of 6, 12, or 24 months. However, the CFPB has documented significant consumer risks associated with deferred-interest financing plans.
Deferred-interest mechanics mean that if you don't pay the entire balance before the promotional period ends, interest is charged retroactively from the original purchase date at rates frequently exceeding 26.99% APR. A $3,000 surgery financed at 27% APR can accumulate over $1,600 in backdated interest if you miss the deadline by even one day.
In-House Payment Plans
Some veterinary practices offer direct payment plans without involving third-party lenders. These arrangements vary widely:
- Down payment requirements: Typically 25-50% due at time of service
- Payment duration: Usually 3-6 months for the balance
- Interest and fees: Some practices charge no interest; others assess finance charges
- Approval criteria: Based on practice's internal evaluation rather than formal credit check
Research published in peer-reviewed veterinary literature indicates that financial barriers remain a significant obstacle to accessing veterinary care, prompting many practices to develop more flexible payment solutions.
Alternative Financing Sources and Assistance Programs
Before committing to a loan for pet surgery, explore programs that might reduce your overall financial burden.
Nonprofit Assistance Organizations
Several national and regional nonprofits provide grants or financial assistance for veterinary care:
- The Pet Fund offers grants for non-basic, non-urgent care, including many surgical procedures
- American Humane Second Chance Grants support urgent medical care for animals in specific circumstances
- Breed-specific rescue organizations often maintain emergency medical funds for their particular breeds
- Local animal welfare organizations may offer voucher programs or subsidized care
Application processes for these programs require documentation of financial need and veterinary estimates. Processing times vary, making them better suited for planned procedures than true emergencies.
Veterinary School Teaching Hospitals
Veterinary teaching hospitals at major universities provide high-quality care at reduced costs. Students perform procedures under the direct supervision of board-certified specialists, offering you access to advanced expertise while contributing to veterinary education.
Wait times for non-emergency procedures can extend several weeks, and you'll need to travel to the university location. However, savings of 30-50% compared to private specialty practices make this option worth investigating for planned surgeries.
Comparing Your Financing Options
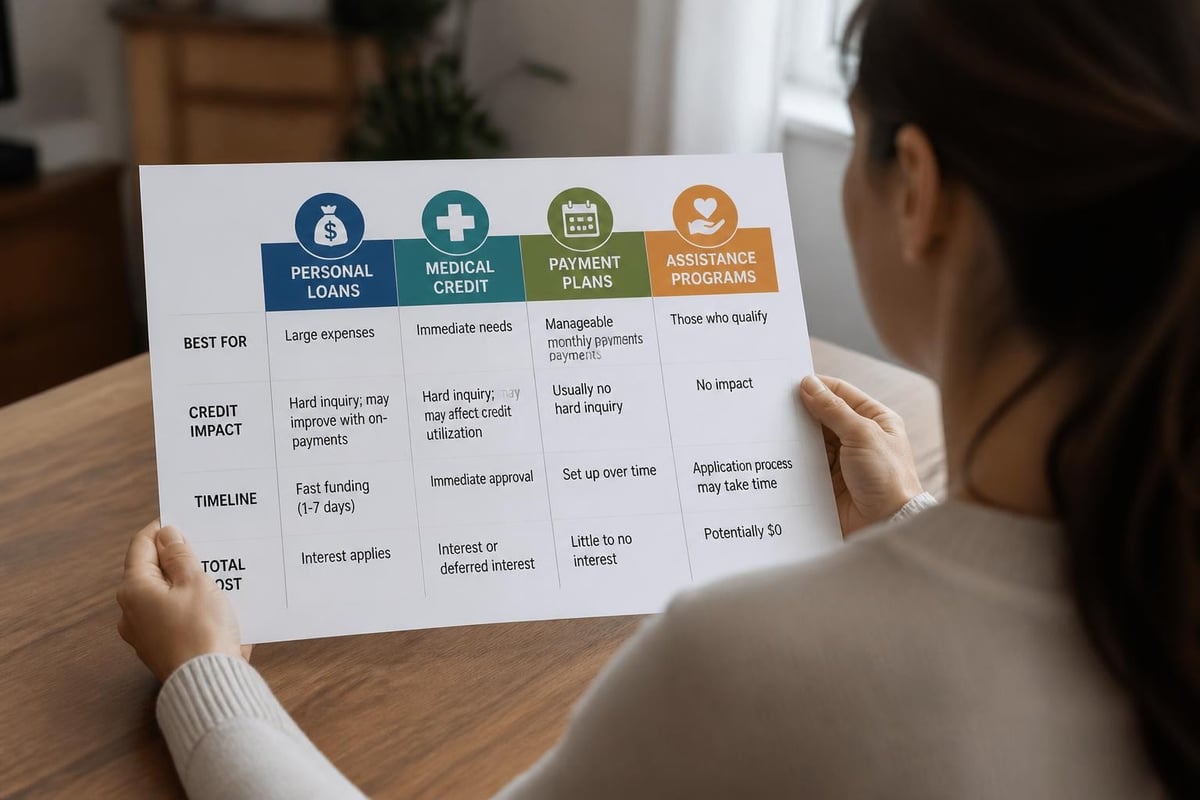
Choosing the right financing method depends on your specific situation, credit profile, and the urgency of your pet's medical need.
| Financing Type | Best For | Typical Terms | Key Advantage | Main Drawback |
|---|---|---|---|---|
| Personal loan | Good-excellent credit, flexible use | 2-7 years, 6-36% APR | Fixed payments, no retroactive interest | Credit check required |
| Medical credit card | Ability to pay within promo period | 0% for 6-24 months (then 27%+) | No interest if paid off | Deferred interest risk |
| Veterinary payment plan | Existing client, smaller amounts | 3-6 months, varies | No credit check, direct relationship | Limited availability, high down payment |
| Credit card | Immediate need, rewards value | Revolving, 15-25% APR | Instant access, potential rewards | High ongoing interest |
| Assistance program | Financial hardship, planned surgery | Grant or subsidy | Reduced cost or free | Limited availability, long wait |
Building Your Financial Strategy
Creating a proactive financial plan for pet healthcare reduces stress when surgical needs arise unexpectedly.
Emergency Pet Fund
Financial advisors recommend maintaining an emergency fund covering 3-6 months of expenses. Applying this principle to pet ownership means setting aside funds specifically for veterinary emergencies.
Start with a modest goal of $500 and build toward $2,000-$3,000 over time. Even small monthly contributions of $50-$100 create a meaningful buffer that can reduce the amount you need to borrow or eliminate borrowing entirely for minor procedures.
Preventive Care Investment
Regular wellness visits, vaccinations, and preventive treatments reduce the likelihood of expensive emergency surgeries. Dental cleanings prevent periodontal disease that can require surgical intervention. Parasite prevention avoids complications from heartworm or tick-borne illnesses.
While preventive care requires ongoing expenditure, it costs substantially less than emergency surgical treatment for preventable conditions.
Working With Your Veterinarian on Cost
Open communication with your veterinary provider helps you navigate financial constraints while ensuring your pet receives necessary care. Research on veterinary care practices shows that many veterinarians are willing to discuss cost-effective approaches when clients are transparent about budget limitations.
Questions to Ask Your Veterinarian
- What is the medical necessity timeline? Distinguishing between urgent and elective procedures affects your financing strategy
- Are there alternative treatment approaches? Some conditions offer both surgical and medical management options
- Can the procedure be staged? Breaking complex treatments into phases spreads costs over time
- Which components are essential versus optimal? Understanding the spectrum of care helps you prioritize spending
- Do you offer payment plans or work with specific lenders? Some practices have established relationships with financing companies
Many veterinarians appreciate clients who engage proactively in cost discussions rather than simply declining necessary care due to price concerns.
Credit Considerations When Applying for a Loan
Your credit profile significantly impacts the loan terms you'll receive for pet surgery financing.
Credit Score Ranges and Loan Availability
Excellent credit (720+): Qualifies for the lowest interest rates, typically 6-12% APR, with loan amounts up to $50,000 and terms extending to seven years.
Good credit (680-719): Access to competitive rates in the 10-18% range with favorable terms from most lenders.
Fair credit (640-679): Personal loans remain available but at higher rates, usually 16-24% APR, sometimes with shorter repayment periods or smaller loan amounts.
Poor credit (below 640): Traditional lenders may decline applications, but specialized consumer lenders focusing on flexible financing for clients with past credit issues provide alternatives, albeit at premium rates.
Impact on Your Credit Report
Applying for a loan for pet surgery generates a hard inquiry on your credit report, which can temporarily reduce your score by 5-10 points. Multiple applications within a short period (14-45 days, depending on the scoring model) typically count as a single inquiry when comparison shopping.
Once approved, the new loan appears as an installment account. Making consistent on-time payments builds positive payment history, the most important factor in credit scoring. Conversely, missed or late payments damage your credit significantly and may incur late fees.
Managing Loan Repayment Successfully
Securing financing solves the immediate problem of paying for surgery, but successful repayment requires planning.
Budgeting for Monthly Payments
Before accepting loan terms, calculate how the monthly payment fits within your existing budget. The 28/36 rule suggests housing costs shouldn't exceed 28% of gross income, while total debt payments should stay under 36%.
If a $200 monthly payment on a three-year, $6,000 loan strains your budget, consider:
- Extending the repayment term to reduce monthly payments (though this increases total interest paid)
- Borrowing a smaller amount and using savings or assistance programs to cover the gap
- Exploring secured loan options that may offer lower rates and more flexible terms
Accelerated Payoff Strategies
Paying off your loan faster than required saves interest and frees up monthly cash flow sooner. Strategies include:
- Biweekly payments: Splitting your monthly payment in half and paying every two weeks results in 26 half-payments (13 full payments) annually instead of 12
- Windfall application: Direct tax refunds, bonuses, or other unexpected income toward principal reduction
- Round-up method: Rounding monthly payments to the next $50 or $100 increment adds extra principal without feeling burdensome
Always verify your loan has no prepayment penalties before implementing accelerated payoff plans.
Regional Considerations for Southern States
Residents of Louisiana, Mississippi, Tennessee, and Georgia face specific considerations when seeking a loan for pet surgery.
Access to Veterinary Specialty Care
The southeastern United States has growing access to veterinary specialty care, with major centers in New Orleans, Memphis, Nashville, Atlanta, and Jackson offering advanced surgical capabilities. However, rural areas may require travel to metropolitan areas for complex procedures.
Travel costs, hotel stays, and time away from work add to the total expense of surgical care, making comprehensive financing coverage important. Local assistance resources, though this example is from Virginia, serve as a model for finding regional programs that can supplement your financing.
Economic Factors Affecting Lending
Regional economic conditions influence both veterinary costs and lending environments. Cost of living variations mean surgical procedures in Atlanta may carry different price points than comparable services in rural Mississippi.
Local and regional lenders familiar with southeastern economic patterns often provide more nuanced underwriting than national banks, potentially offering better terms for borrowers with non-traditional employment or past credit challenges common in areas still recovering from economic disruptions.
Making an Informed Decision
Selecting the right financing for your pet's surgery requires evaluating multiple factors simultaneously: the medical urgency, your credit profile, available assistance programs, and long-term financial impact.
Decision Framework
Start by determining your immediate financial capacity. What can you pay upfront from savings or emergency funds? This establishes the amount you need to finance.
Next, assess the timeline urgency. Life-threatening conditions requiring immediate surgery demand fast-funding solutions like personal loans or credit cards. Planned procedures allow time to apply for assistance programs or save additional funds.
Evaluate your creditworthiness honestly. Checking your credit score before applying helps you anticipate likely terms and identify lenders most appropriate for your profile.
Finally, calculate total cost across different options. A 12-month interest-free medical credit card looks attractive, but if there's risk you won't pay it off completely, a five-year personal loan at 15% APR may cost less overall than retroactive interest at 27%.
Understanding your options for financing veterinary surgery ensures your pet receives necessary care without creating overwhelming financial stress. Whether you choose a personal loan, payment plan, or combination of assistance programs and financing, the key is acting promptly while making informed decisions. If you're located in Louisiana, Mississippi, Tennessee, or Georgia and need flexible financing for your pet's surgery, Standard Financial offers personal loans designed to help families manage unexpected expenses, with options available even if you've faced credit challenges in the past.

No comment yet, add your voice below!