

Building or rebuilding credit can feel like an impossible challenge, especially when most financial institutions require good credit just to get started. If you've struggled with past credit issues, have no credit history, or are recovering from financial setbacks, you might wonder how you can prove your creditworthiness. This is where credit builder loans offer a unique solution designed specifically for people in your situation, providing a pathway to establish positive credit history even when traditional lending options remain out of reach.
Understanding Credit Builder Loans
When asking "what is a credit builder loan," it's essential to recognize that these products work differently from traditional loans. Unlike conventional personal loans where you receive funds upfront and repay over time, a credit builder loan reverses this process entirely. The lender holds your loan amount in a locked savings account while you make monthly payments. Only after completing all payments do you receive access to the funds.
This structure benefits both parties involved. Lenders minimize risk because they hold the money throughout the repayment period, while borrowers demonstrate creditworthiness through consistent on-time payments. Each monthly payment gets reported to the major credit bureaus-Experian, Equifax, and TransUnion-creating a positive payment history that gradually builds your credit profile.
The Mechanics Behind Credit Builder Loans
Financial institutions typically offer credit builder loans in amounts ranging from $300 to $3,000, with repayment terms spanning 6 to 24 months. When you're approved, the lender deposits the loan amount into a certificate of deposit (CD) or secured savings account in your name. You cannot access these funds until you've satisfied the loan terms completely.
Your monthly payment includes both principal and interest, just like traditional loans. Interest rates vary considerably, generally falling between 6% and 16% APR, depending on the lender and your location. Some credit unions and community development financial institutions (CDFIs) offer particularly competitive rates for members.
Benefits of Credit Builder Loans for Consumers
The primary advantage addresses exactly what is a credit builder loan designed to accomplish: establishing verifiable credit history. For individuals with thin credit files or no credit history whatsoever, building credit from scratch requires strategic action. Credit builder loans provide that structured approach.
Key advantages include:
- Accessible approval requirements – Most lenders focus on your ability to make payments rather than existing credit scores
- Dual benefit structure – You build credit while simultaneously creating savings
- Forced savings discipline – Automatic payments help develop consistent financial habits
- Credit mix improvement – Adding an installment loan diversifies your credit profile
- Predictable costs – Fixed payments and terms eliminate surprises
Beyond credit building, these loans serve as forced savings mechanisms. Once you've completed payments, you receive the principal back, minus interest and any fees. For many borrowers, this represents their first substantial emergency fund or savings cushion.
Impact on Credit Scores
Understanding what is a credit builder loan involves recognizing how it affects your credit scores. Payment history constitutes 35% of your FICO score, making it the single most influential factor. According to research on credit score components, consistent on-time payments create the foundation for strong credit.
When you maintain perfect payment history on a credit builder loan, you're demonstrating reliability to future lenders. The loan also affects your credit mix (10% of your score) by adding an installment loan, particularly valuable if you only have revolving credit accounts or no accounts at all.
| Credit Score Factor | Weight | How Credit Builder Loans Help |
|---|---|---|
| Payment History | 35% | Every on-time payment reported positively |
| Credit Utilization | 30% | Not directly affected (installment loan) |
| Credit History Length | 15% | Begins establishing account age |
| Credit Mix | 10% | Adds installment loan diversity |
| New Credit | 10% | One hard inquiry at application |
However, late or missed payments damage your credit significantly. The same reporting that helps you when paying on time hurts you when you miss payments. This makes budgeting for your monthly payment absolutely critical before committing to a credit builder loan.
Costs and Considerations
While credit builder loans offer clear benefits, you must understand the associated costs to determine whether they fit your financial situation. Interest charges represent the most obvious expense, but several other fees may apply depending on your lender's policies.
Fee Structure Breakdown
Common costs include:
- Interest charges – Calculated on the loan amount throughout the repayment period
- Administrative fees – One-time setup charges ranging from $0 to $50
- Late payment fees – Penalties for missing payment deadlines, typically $15 to $30
- Early payoff fees – Some lenders charge for paying off loans ahead of schedule
- Account maintenance fees – Monthly charges that some institutions assess
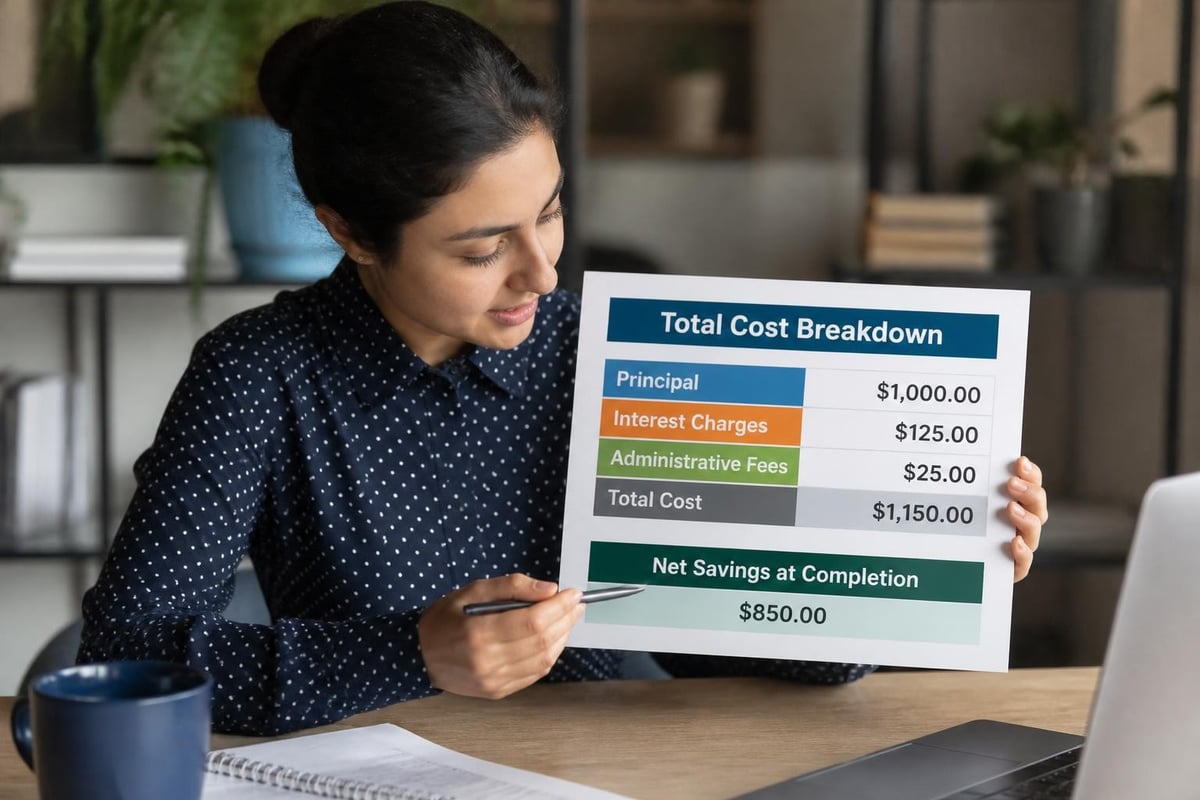
When evaluating what is a credit builder loan worth to you financially, calculate the total cost. For example, a $1,000 loan at 12% APR over 12 months costs approximately $66 in interest. If the lender charges a $25 administrative fee, your total cost reaches $91 to build credit and save $1,000. That's a reasonable trade-off for many borrowers, especially those with limited alternatives.
Comparing Credit Builder Options
Not all credit builder loans offer the same value proposition. Community development financial institutions and credit unions frequently provide better terms than traditional banks or online lenders. Consumer protection guidance emphasizes the importance of reviewing all disclosures carefully before committing.
Credit unions serving Louisiana, Mississippi, Tennessee, and Georgia often feature particularly competitive rates and minimal fees for members. Building a relationship with a local credit union can provide long-term benefits beyond just the credit builder loan itself.
Eligibility Requirements and Application Process
Unlike traditional loans, what is a credit builder loan's eligibility focuses less on credit history and more on current financial capacity. Most lenders require proof that you can afford the monthly payment without defaulting.
Typical requirements include:
- Valid government-issued identification
- Social Security number or Individual Taxpayer Identification Number
- Proof of income (pay stubs, bank statements, or tax returns)
- Active checking or savings account
- Minimum age of 18 years
- Residence in the lender's service area
The application process typically takes 15 to 30 minutes and may be completed online, by phone, or in person at branch locations. Some lenders provide instant decisions, while others review applications within one to three business days.
What Happens After Approval
Once approved, you'll sign a loan agreement detailing the terms, payment schedule, interest rate, and any applicable fees. The lender then deposits the loan amount into a secured account and provides you with payment instructions. Most institutions offer multiple payment methods including automatic bank transfers, online payments, phone payments, or in-person payments at branch offices.
Setting up automatic payments ensures you never miss a due date, protecting your credit while building it. Many lenders offer small interest rate discounts for borrowers who authorize automatic payments.
Strategic Use of Credit Builder Loans
Maximizing what is a credit builder loan's effectiveness requires strategic planning beyond simply making payments. Timing your application appropriately can accelerate your credit-building goals and prepare you for larger financial moves.
Optimal Timing Considerations
Consider opening a credit builder loan:
- 12-24 months before major purchases – Allow sufficient time to establish payment history before applying for mortgages or auto loans
- After addressing derogatory marks – Resolve collections, charge-offs, or other negative items first when possible
- When income is stable – Ensure consistent ability to make payments without financial strain
- Before needing traditional credit – Start building early rather than scrambling when you need credit urgently
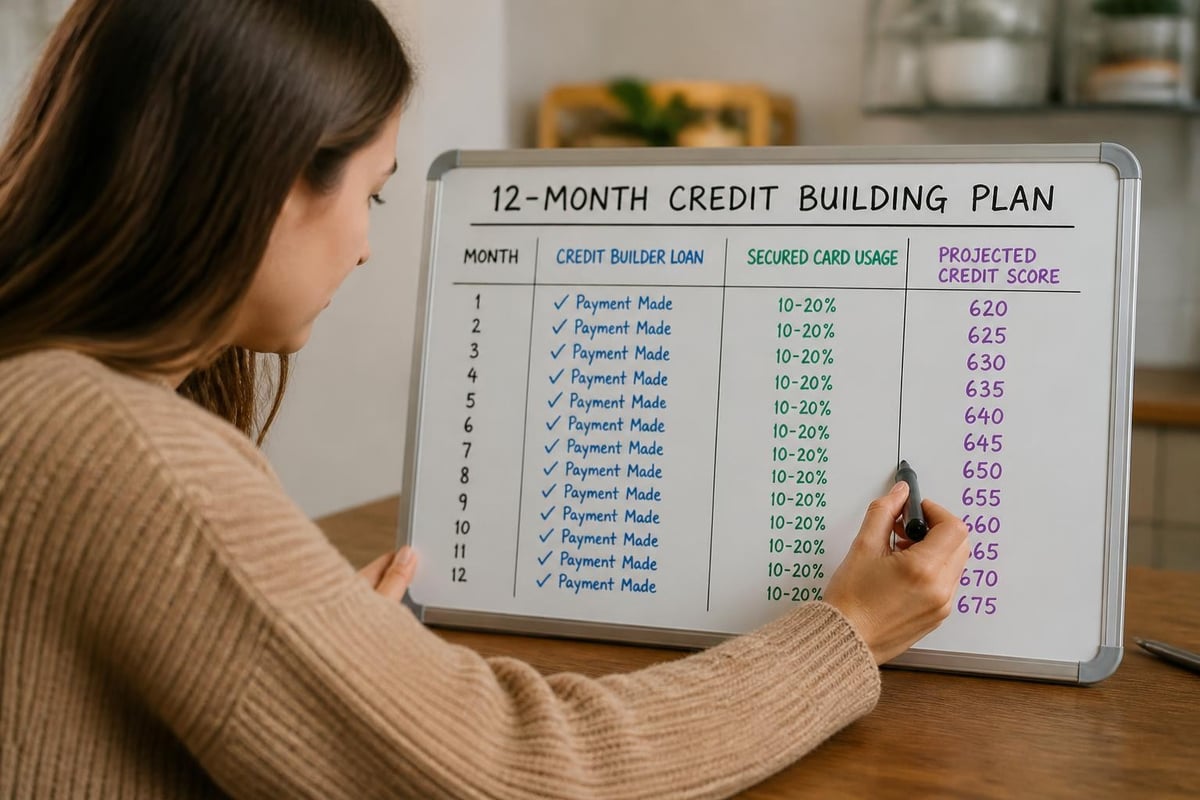
Research from the Consumer Financial Protection Bureau on credit builder programs shows that borrowers who complete their loans successfully see measurable credit score improvements, with many gaining 30 to 60 points within the first year.
Combining with Other Credit-Building Strategies
Credit builder loans work best as part of a comprehensive credit-building strategy. Complement your loan with:
- Becoming an authorized user on a responsible person's credit card
- Using a secured credit card with low utilization
- Ensuring all bills report to credit bureaus when possible
- Monitoring your credit reports for errors and disputing inaccuracies
- Maintaining low balances on any existing revolving accounts
The CFPB provides detailed guidance on multiple strategies that work together to establish strong credit profiles more quickly than relying on any single approach.
Alternatives to Credit Builder Loans
While understanding what is a credit builder loan helps you make informed decisions, comparing alternatives ensures you select the best option for your circumstances. Several other products and strategies can build credit, each with distinct advantages and drawbacks.
| Option | Upfront Cost | Time to Impact | Risk Level | Best For |
|---|---|---|---|---|
| Credit Builder Loan | Interest + fees | 3-6 months | Low | Forced savings + credit |
| Secured Credit Card | Deposit amount | 1-3 months | Medium | Building revolving credit |
| Authorized User | $0 | Immediate | Low | Piggybacking good history |
| Traditional Personal Loan | None (receive funds) | 1-3 months | High | Existing good credit |
| Rent Reporting Services | $0-$100/year | 1-2 months | Very Low | Renters with payment history |
Secured credit cards require refundable security deposits (typically $200-$500) and function like regular credit cards. They report to credit bureaus monthly, and responsible use can build credit quickly. However, they require discipline to avoid overspending and carrying balances.
Authorized user status costs nothing and can provide immediate credit history benefits if added to an account with excellent payment history and low utilization. The primary account holder bears all financial responsibility, but any negative activity also affects your credit.
Rent reporting services add your rental payment history to credit reports. Some property management companies report automatically, while services like Rental Kharma and RentTrack charge fees to report payments. This strategy works particularly well when combined with credit builder loans.
According to Bankrate’s analysis of credit builder options, the ideal approach often involves using multiple strategies simultaneously to establish diverse positive payment patterns across different account types.
Common Mistakes to Avoid
Even with clear understanding of what is a credit builder loan, borrowers sometimes make preventable errors that undermine their credit-building efforts. Awareness of these pitfalls helps you navigate the process successfully.
Critical Errors and Solutions
Choosing unaffordable payment amounts – Many borrowers overestimate their budget, selecting loan amounts with monthly payments they struggle to maintain. Calculate your actual discretionary income after all essential expenses and choose a payment you can comfortably afford even during financial setbacks.
Ignoring total cost calculations – Focusing solely on building credit without considering interest and fees can make credit builder loans unnecessarily expensive. Compare multiple lenders and calculate total costs before committing. A loan with 8% APR and no fees beats one with 15% APR and a $50 setup fee.
Missing payment due dates – The entire purpose of credit builder loans is establishing positive payment history. Missing even one payment defeats that purpose and damages your credit. Set up automatic payments or calendar reminders to ensure consistent on-time payments.
Failing to monitor credit reports – Lenders occasionally fail to report payments correctly, or errors appear on your credit reports. Monitor your credit through free services like AnnualCreditReport.com or your lender's credit monitoring tools to verify accurate reporting.
Closing the account immediately after payoff – While you receive your money back after completing payments, the account continues contributing to your credit history. Leave it on your credit report where it benefits your credit age and payment history.
Choosing the Right Lender
The lender you select significantly impacts your credit builder loan experience and outcomes. Understanding what is a credit builder loan includes recognizing that not all lenders offer equivalent terms, customer service, or reporting practices.
Evaluation Criteria
Consider these factors when selecting a lender:
- Credit bureau reporting – Verify the lender reports to all three major bureaus (Experian, Equifax, and TransUnion)
- Interest rates and fees – Compare APRs and all associated costs across multiple institutions
- Loan terms – Evaluate available repayment periods and loan amounts
- Payment flexibility – Assess payment methods, due date options, and policies for financial hardship
- Customer reviews – Research experiences from current and former customers
- Regulatory standing – Confirm the lender's licensing and compliance with federal and state regulations
Credit unions in the Southeast, particularly those serving Louisiana, Mississippi, Tennessee, and Georgia, often provide excellent credit builder loan options with member-focused terms. Community banks and CDFIs similarly prioritize helping local residents build financial stability rather than maximizing profits.
National online lenders offer convenience and quick processing but may charge higher rates or fees. Carefully weigh accessibility against cost when making your decision.
Measuring Your Progress
After securing a credit builder loan, tracking your progress helps you stay motivated and identify any reporting issues early. Most lenders provide online portals where you can view payment history, remaining balance, and upcoming due dates.
Monitoring Milestones
Track these key indicators:
- Payment streak – Number of consecutive on-time payments made
- Credit score changes – Monthly or quarterly score updates showing improvement trends
- Credit report updates – Verification that payments appear on all three bureau reports
- Savings accumulation – Growing balance in your secured account
- Remaining term – Time until loan completion and fund release
Many people see initial credit score improvements after three to six months of perfect payments, with continued increases as their payment history lengthens. Those starting with very thin files or no credit history often experience more dramatic improvements than those recovering from past credit issues.
Research on consumer credit behavior programs demonstrates that borrowers who actively monitor their progress maintain better payment consistency and achieve stronger credit outcomes than those who set up automatic payments and ignore their accounts.
Regional Considerations for Southeastern Borrowers
Residents of Louisiana, Mississippi, Tennessee, and Georgia face unique financial landscapes that influence what is a credit builder loan's value proposition. Economic conditions, state regulations, and regional lender availability all affect your options and outcomes.
The Southeast includes robust community banking networks and credit unions specifically focused on helping underserved communities build financial stability. These institutions often provide personalized service and financial education alongside credit builder loans, creating comprehensive support systems for borrowers.
State-Specific Advantages
Louisiana credit unions often feature particularly low interest rates and may waive fees for first-time borrowers or members facing financial hardship. Many institutions offer financial counseling as a complementary service.
Mississippi has seen growth in community development financial institutions providing credit builder products specifically designed for rural residents and those recovering from past credit challenges.
Tennessee credit unions frequently bundle credit builder loans with financial education courses, helping borrowers understand broader money management principles while building credit.
Georgia offers diverse options through both traditional credit unions and innovative fintech companies serving the Atlanta metropolitan area and beyond.
Understanding your local landscape helps you identify the most advantageous lending partners and support resources as you work to establish or rebuild your credit profile.
Credit builder loans offer a structured, low-risk path to establishing positive credit history while simultaneously building savings for residents throughout the Southeast. Whether you're starting from scratch or recovering from past financial setbacks, these specialized products provide proven results when used consistently and strategically. Standard Financial understands the challenges facing borrowers with past credit issues and offers flexible financing solutions across Louisiana, Mississippi, Tennessee, and Georgia-contact us today to explore options tailored to your unique situation and financial goals.

No comment yet, add your voice below!