
Auto title loans are short-term loans secured by a vehicle you own outright, and they usually carry much higher costs than other borrowing options because the lender can repossess your car if you miss payments. This guide compares the title lenders most borrowers encounter, explains the rules that shape what they can charge, and shows where a personal loan may be a safer fit for residents of Louisiana, Mississippi, Tennessee and Georgia.
Only two of the lenders below are covered with specific figures drawn from current research. Where a lender's details are limited, the entry stays short rather than guessing. All prices and limits are approximate and current as of November 2026.
1. Loan Mart
Loan Mart is a title lender that offers loans starting at $2,000 and operates in a number of states. Its higher minimum sets it apart from lenders that advertise loans of a few hundred dollars. That floor means the product is built for larger, planned expenses rather than a small cash gap, and a borrower who needs only $500 would have to look elsewhere. A quote is not a loan offer, so any valuation should be confirmed with the lender.
- Loan amounts: from $2,000 and up
- Service area: multiple states
- BBB rating: A+
- Sample quote: varies by vehicle
- Approximate price: varies by vehicle value and state rules
Best for: borrowers who need at least $2,000 and want a lender with a reported A+ Better Business Bureau rating. A higher minimum means a larger balance accruing fees, so the total repayment deserves close scrutiny before signing. A larger loan carries more cost in absolute dollars than a smaller one at the same rate, so ask for the full repayment figure in writing.
Verdict: A reasonable option if your need is large enough to clear its minimum, but borrow only what the budget can repay.
2. TitleMax
TitleMax is a title lender offering loans of up to $10,000, with both online and phone application options. The higher ceiling suits larger needs, though a larger loan against your vehicle puts more at stake. Starting the process online or by phone lets you gather questions and compare terms before visiting a location, which can reduce pressure at the counter. Its service area is limited, so availability should be the first thing you confirm.
- Loan amounts: up to $10,000
- Service area: limited states
- How to apply: online or by phone
- BBB rating: A+
Best for: borrowers inside its service area who need up to $10,000 and prefer to start the application without visiting a branch. Confirm that your state is covered, since availability is limited. A borrower with a newer vehicle of solid value is the most likely to approach the upper end of the range, but the amount offered still depends on the car and state rules.
Verdict: Convenient application options and a high ceiling, balanced against the risk of pledging a vehicle for a large balance.
3. ACE Cash Express
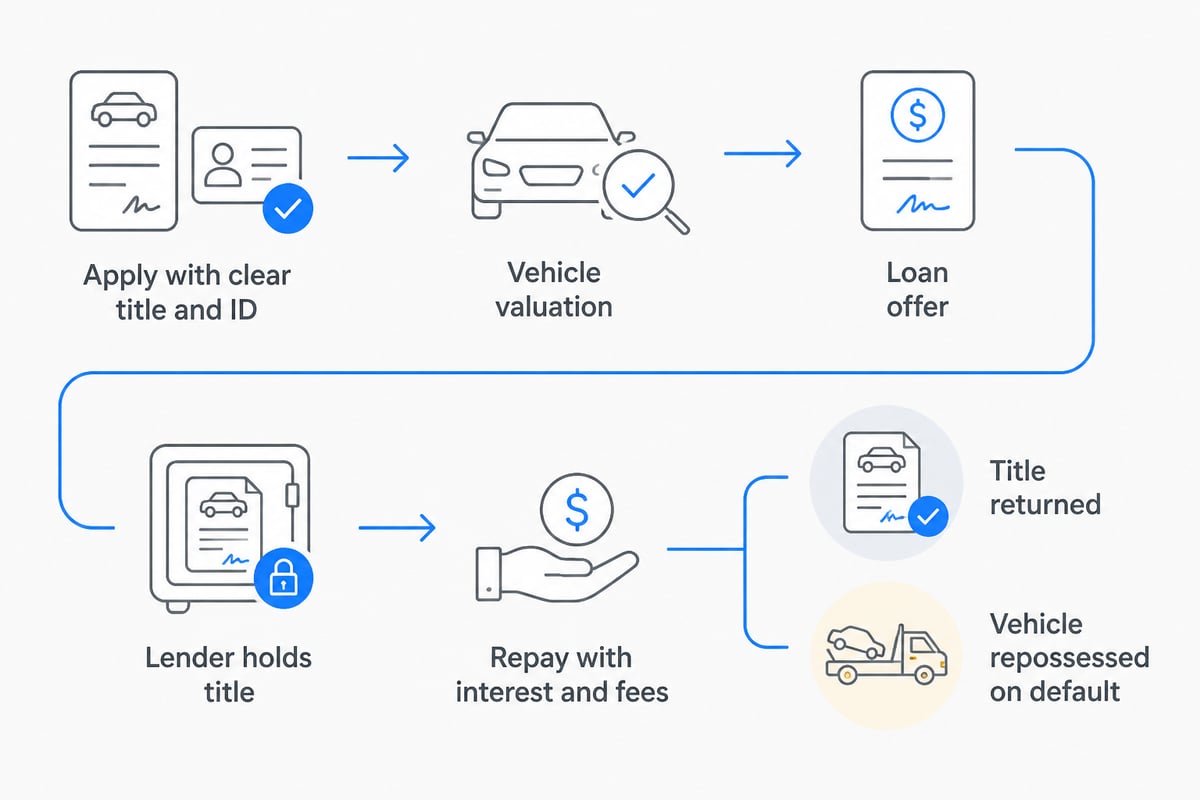
ACE Cash Express offers in-store title loans with amounts that vary widely by state. According to ACE Cash Express, title-loan amounts run $100 to $2,500 in Arizona, $100 to $300 in Oregon, and $100 to $5,000 in Texas, and Texas loans are unavailable in Austin, Dallas and Fort Worth. The spread is large: an Oregon borrower tops out at $300, while a Texas borrower outside those three cities can reach $5,000. ACE also lists an Arizona title-registration installment loan that may accept a valid vehicle registration instead of a paid-off title.
- Loan amounts: $100 to $5,000 depending on state
- Application: in store
- Requirements: a clear title in your name, government-issued photo ID and proof of recurring income; applicants must be at least 18, per ACE’s FAQ
- Vehicle condition: the vehicle must be paid off
Best for: borrowers who need a small amount, from $100 up, and prefer applying in person. Check local availability first, since its listed states may not include your area. Bringing your title, photo ID and a recent proof of income, such as a pay stub or benefit statement, helps the visit go faster.
Verdict: Flexible on small amounts, but the state list limits who can use it.
4. Standard Financial Title Loans
Standard Financial offers title loans in Baton Rouge, secured by a vehicle title. Standard Financial designs every product with the customer in mind and gives borrowers a chance to explain their credit situation so a tailor-made solution can be built. That conversation matters because title lending often turns on circumstances a credit score cannot show, such as a recent job change or a one-time medical bill. Since amounts and terms are not published here, a branch visit is the practical way to see an offer.
- Security: vehicle title
- Location: Baton Rouge
- Approach: works with people who have past credit problems or limited credit
- Rates, amounts and terms: see the product page or contact a branch
Best for: Baton Rouge residents who want to discuss a title-secured loan with a local branch and explain their credit history in person. Ask for the APR, the total repayment and the consequences of a missed payment before agreeing to anything. A local branch also makes it simpler to handle questions or payment issues face to face.
Verdict: A local option with a customer-focused approach; confirm all terms directly before committing.
5. Standard Financial Personal Loans
Standard Financial's personal loans are designed for people with limited or impaired credit, and refinancing options are available. Because they do not require you to pledge your vehicle, a missed payment does not put your car on the line in the same way. The loans can cover home improvements, medical expenses, education and more, so the money is not tied to a single purpose. For someone who already holds a title loan, refinancing into a personal loan may be a way to recover the title and spread payments over a more manageable schedule.
- Security: see Standard Financial for current terms
- Credit: works with people who have past credit problems or limited credit
- Flexibility: flexible financing plans and refinancing options
- Uses: home improvements, medical expenses, education and more
- Branches: Louisiana, Mississippi, Tennessee and Georgia
Best for: borrowers in those four states who want to avoid risking a vehicle and prefer an installment structure with refinancing available. It also suits people who need a larger or longer-term loan than a short title product typically allows. Compare the APR and total repayment against any title offer you have received.
Verdict: The lower-risk alternative on this list for anyone whose credit history has made borrowing harder.
Comparison table
| Option | Max or minimum amount | Service area | Application | Key point |
|---|---|---|---|---|
| Loan Mart | From $2,000 | Multiple states | Not listed | A+ BBB rating |
| TitleMax | Up to $10,000 | Limited states | Online or phone | A+ BBB rating |
| ACE Cash Express | $100 to $5,000 by state | Select states | In store | Clear title and income proof required |
| Standard Financial Title Loans | See product page | Baton Rouge | Branch | Credit situation discussed |
| Standard Financial Personal Loans | See Standard Financial | LA, MS, TN, GA | Branch or apply online | No vehicle pledged |
What state rules reveal about title loan costs
Regulated markets show how expensive title loans can be. Oregon's regulator provides a clear example, and the numbers illustrate what borrowers should expect to question anywhere.
- Oregon title loans must run at least 31 days and no more than 60 days; longer loans are treated as installment loans, per the Oregon Division of Financial Regulation.
- Lenders may charge interest up to 36% annually, plus a one-time origination fee capped at $10 per $100 borrowed or $30, whichever is less, under ORS 725A.062.
- The regulator lists the maximum APR, including interest and fees, as 153.77%.
Rules differ from state to state, so ask any lender for the full APR in writing. The APR, not the monthly payment, is the figure that allows a fair comparison.
How much can you borrow with auto title loans?
The most you can get from an auto title loan depends on the lender, your state and your vehicle's value, with advertised ceilings ranging from a few hundred dollars to $10,000 among the lenders above. A lender typically offers only a portion of the car's appraised worth.
Borrowing the maximum is rarely wise. A smaller loan means a smaller balance and less exposure if your income dips. Calculate the full repayment, including every fee, before accepting any amount. If your credit history makes borrowing harder, our guide to hardship loans explains the options for poor or limited credit and how to borrow safely.
What happens if you cannot repay a title loan?
If you cannot repay, the lender can repossess your vehicle, and some lenders offer rollovers that add fees and extend the balance. Contact the lender before a payment is missed, since many will discuss options early.
To get out of a title loan legally, work through these steps:
- Read your contract for early-payoff terms and rollover fees.
- Ask the lender about a payment plan or extension before defaulting.
- Consider refinancing into a lower-cost personal loan to pay off the title loan and recover your title.
- Contact your state attorney general or banking regulator if you believe the lender broke the rules.
Refinancing is where a lender like Standard Financial may help, since it offers refinancing options and works with borrowers who have limited or impaired credit. Contact a branch to see what is available.
Is a personal loan a better choice than auto title loans?
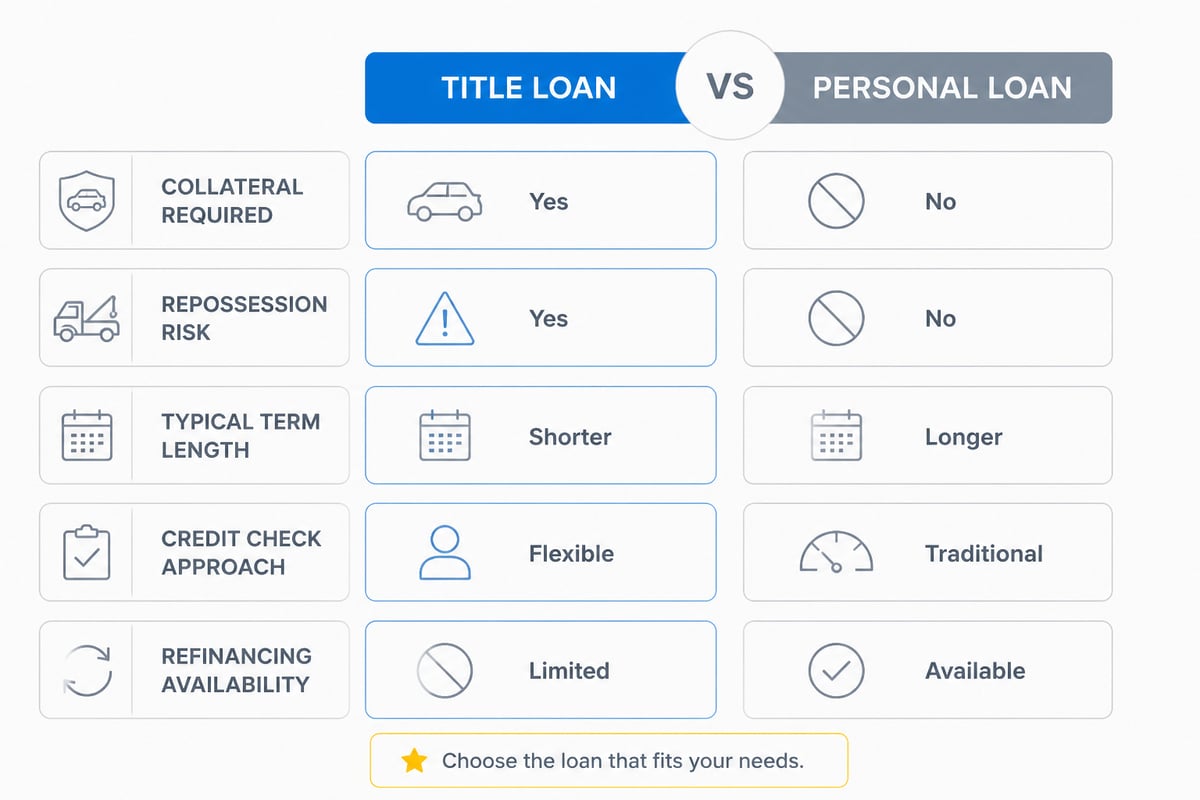
For many borrowers, a personal loan is the safer choice because it does not put your vehicle at risk. A title loan can feel faster, yet the combination of short terms, high APRs and repossession risk makes it costly when income is uncertain.
Weigh these factors before choosing:
- Collateral: a title loan pledges your car; an unsecured personal loan does not.
- Term length: title loans are often short, while installment loans spread payments out.
- Cost: compare APRs, not monthly payments.
- Credit history: some lenders, including Standard Financial, work with limited or impaired credit.
How to get the title for a financed vehicle
You generally cannot use a financed vehicle for a title loan because the lender holding your car loan keeps the title until you pay it off. ACE, for example, says the vehicle must be paid off, with a narrow exception for an Arizona registration-based loan.
Once the loan is paid, the lienholder releases the lien and your state motor vehicle agency issues a clear title. Request this release in writing and allow processing time. If you need money before then, a personal loan avoids the title requirement entirely.
FAQ
Do auto title loans require a credit check?
Many title lenders focus on the vehicle's value and your income rather than credit history, which is why they attract borrowers with past credit problems. Requirements vary, so confirm what a specific lender evaluates before applying.
Can I take out a title loan online?
Some lenders, such as TitleMax, offer online or phone application, though final steps may still require verifying the vehicle. Oregon's regulator reports no licensed online title lenders there, so availability depends on state law.
Will a title loan keep my car safe if I pay on time?
If you repay on schedule, the lender returns your title and you keep the vehicle. The risk comes from missed payments or rollovers that grow the balance, which can end in repossession.
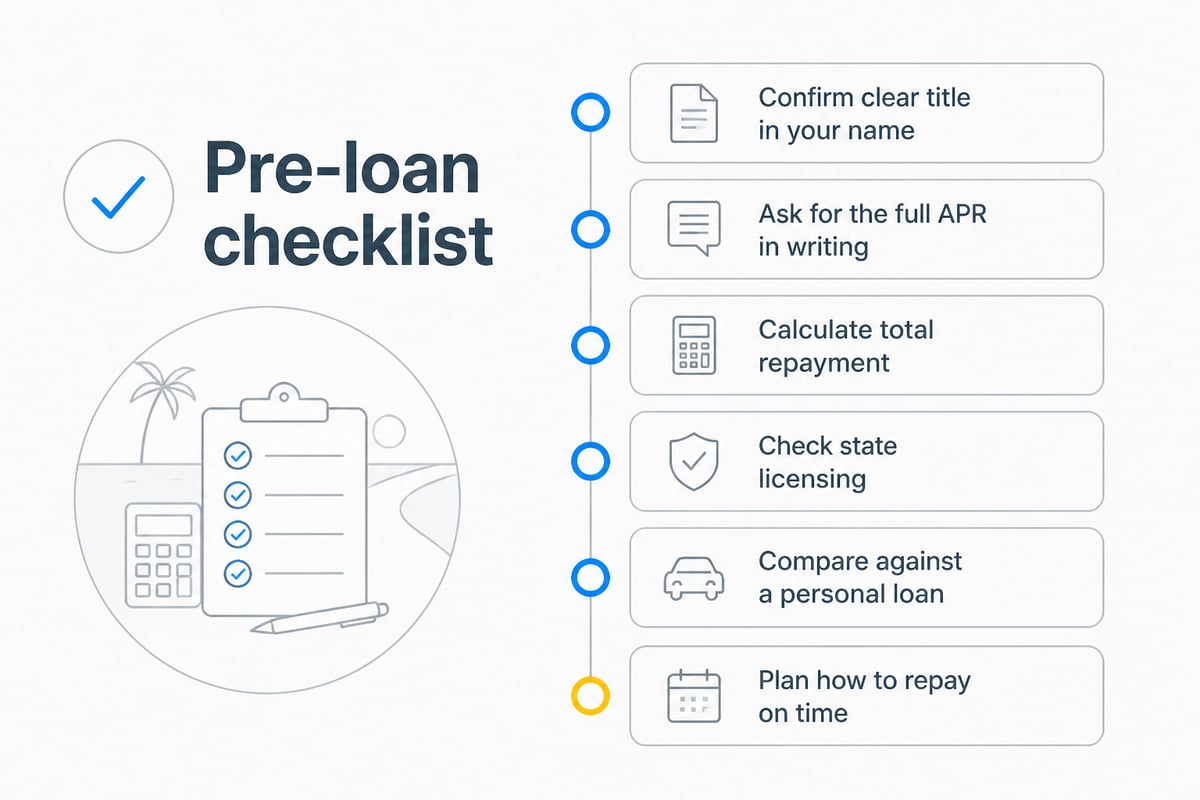
Before signing anything, ask each lender for the full APR and total repayment in writing, then compare it against a loan that does not require your vehicle. If you live in Louisiana, Mississippi, Tennessee or Georgia, Standard Financial's personal loans are built for people with past credit problems or limited credit, with flexible financing plans and refinancing options available through its branch offices. Standard Financial is a leader in consumer lending, offering loans for home improvements, medical expenses and education, so you can take the next step and apply for a loan with Standard Financial to find a solution built around your situation.

1 Comment
[…] borrowers in the Baton Rouge area who want to understand a vehicle-secured loan before committing, Standard Financial publishes information on its title loans in Baton Rouge. Standard Financial works with people who […]