
A personal loan for emergencies is a fixed-payment installment loan that can fund an urgent expense, usually within one to three business days after approval, and it generally costs far less than a payday loan or a credit-card cash advance. The right choice depends on how much you need, how quickly you need it and what your credit looks like today. This guide compares eight borrowing options, with their reported rates, terms and fees, so you can match the loan to the emergency.
How to Judge an Emergency Loan Before You Apply
Judge any emergency loan by its total cost, its repayment schedule and its funding speed, in that order. A fast approval means little if the payment strains your budget for the next five years.
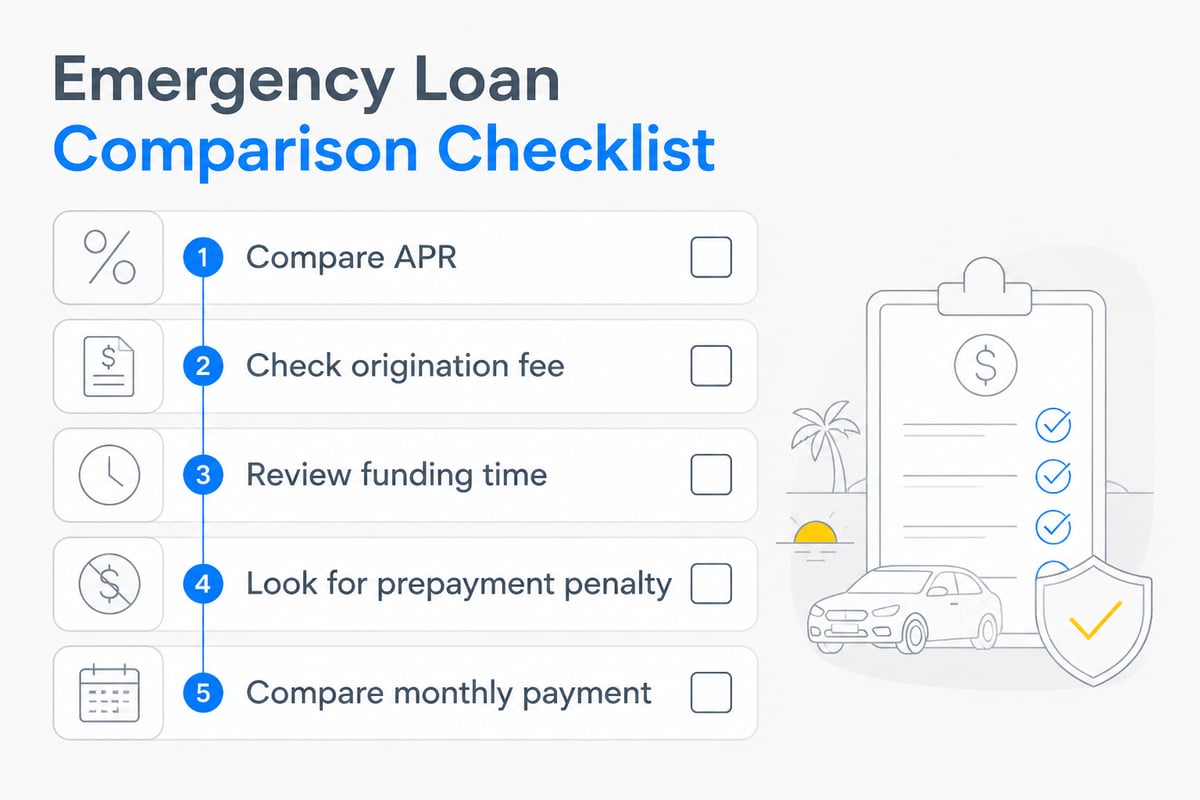
Check these points on every offer:
- APR, not just the interest rate. The annual percentage rate includes most lender fees and gives a fairer comparison.
- Origination fees. Experian reports origination or processing fees on its emergency-loan marketplace, and individual lenders can charge different amounts.
- Funding time. Most lenders fund within the same day to three business days after approval, according to the same Experian page. Timing depends on approval speed and how the money is delivered.
- Prepayment penalties. You want the freedom to pay the loan off early without a charge.
- Fixed or variable payment. A fixed installment makes budgeting easier during a stressful month.
1. LendingPoint Personal Loan
A LendingPoint personal loan is an online installment loan with a published range of amounts, rates and terms.
- Loan amounts: $1,000 to $36,500
- APR: 7.99% to 35.99%
- Terms: 24 to 72 months
- Fees: origination or other fees may apply, depending on state
LendingPoint lists these ranges on its online loans page, and the fee depends on your state of residence, so confirm what applies in Louisiana, Mississippi, Tennessee or Georgia before you sign. The wide APR band means a borrower with weaker credit should expect an offer toward the upper end.
Best suited to: a mid-sized emergency, such as a $3,000 to $10,000 repair bill, that you can repay over two to six years.
Verdict: A clear, structured online option, as long as you account for the possible origination fee.
2. Experian Personal-Loan Marketplace
The Experian marketplace is a comparison service that matches you with several lender offers rather than a single lender.
- APR range on the marketplace: 5.96% to 35.99%
- Terms: 6 to 84 months, according to the Experian marketplace
- Features that may appear: same-day funding, direct deposit and no prepayment fees
- Availability: rates and offers depend on the lender, your state and your application
Experian's broader guidance says marketplace offers can range widely in amount, APR and term, with availability varying, as described on its emergency loans page. The ranges differ between Experian pages, which is a reminder that your actual offer will depend on the lender and your profile. You can also review the Experian personal loan comparison page to see how the matching works.
Best suited to: comparing several offers at once when you are unsure how much you qualify for.
Verdict: Useful for rate shopping in one place, though final terms come from the lender.
3. Experian Cash Powered by Brigit
Experian Cash is a small cash advance product, not a traditional loan, available to eligible users.
- Advance size: $25 to $250, depending on eligibility
- Credit check: none
- Cost: no interest and no late fees, as described by Experian
- Membership: Experian Plus carries a monthly fee plus applicable sales tax, and an optional express-delivery fee may apply
Experian describes the product in its emergency money guide. The advance is small, so it fits a gap of a few days rather than a major bill. Factor in the monthly membership when you calculate what the advance really costs.
Best suited to: a short-term shortfall of under $250, such as a utility bill due before payday.
Verdict: A low-cost bridge for small amounts, but too limited for car or medical emergencies.
4. Unsecured Personal Loan
An unsecured personal loan is a fixed-payment loan that does not require collateral, as Experian explains.
- Collateral: none required
- Rates and terms: depend on the lender and your creditworthiness
- Funding: may take the same day to three business days after approval
- Payment: fixed installments over a set term
Because the lender cannot claim an asset if you default, pricing leans on your credit profile and income. Banks, credit unions, online lenders and branch-based consumer lenders all offer this type of loan, and terms vary widely between them.
Best suited to: a one-time emergency where you want predictable payments and do not want to pledge a vehicle or other property.
Verdict: The default choice for most emergencies when your credit and income support approval.
5. Standard Financial Personal Loans
Standard Financial personal loans are designed for people with limited or impaired credit, and refinancing options are available. Standard Financial operates branch offices in Louisiana, Mississippi, Tennessee and Georgia.
- Approach: gives customers a chance to explain their credit situation and builds a tailor-made solution
- Who it serves: people with past credit problems or limited credit
- Plans: flexible financing plans and refinancing options
- Amounts, rates and terms: confirm on the Standard Financial website or at a local branch
Because applications are reviewed with your circumstances in mind, a past late payment or a thin credit file does not automatically end the conversation. That matters when an online lender's automated score would rule you out.
Best suited to: a borrower in the four-state footprint whose credit history makes online approvals uncertain and who prefers working with a local branch.
Verdict: A practical fit when credit history is the main obstacle, with specific terms to be confirmed directly.
6. Standard Financial Title Loans
Title loans from Standard Financial are secured by a vehicle title and are offered in Baton Rouge.
- Security: the vehicle title
- Location: Baton Rouge
- Amounts, rates and terms: see the Standard Financial title loan page or contact a branch
A secured loan can open a path for borrowers who cannot qualify for an unsecured one, but it carries real risk, because the vehicle backs the debt. Only consider it if you are confident in your ability to repay on schedule and you have compared it against an unsecured personal loan first.
Best suited to: a Baton Rouge borrower with a vehicle they own outright who cannot get an unsecured loan approved.
Verdict: A narrower option, best treated as a second choice after unsecured loans.
7. Credit-Card Cash Advance
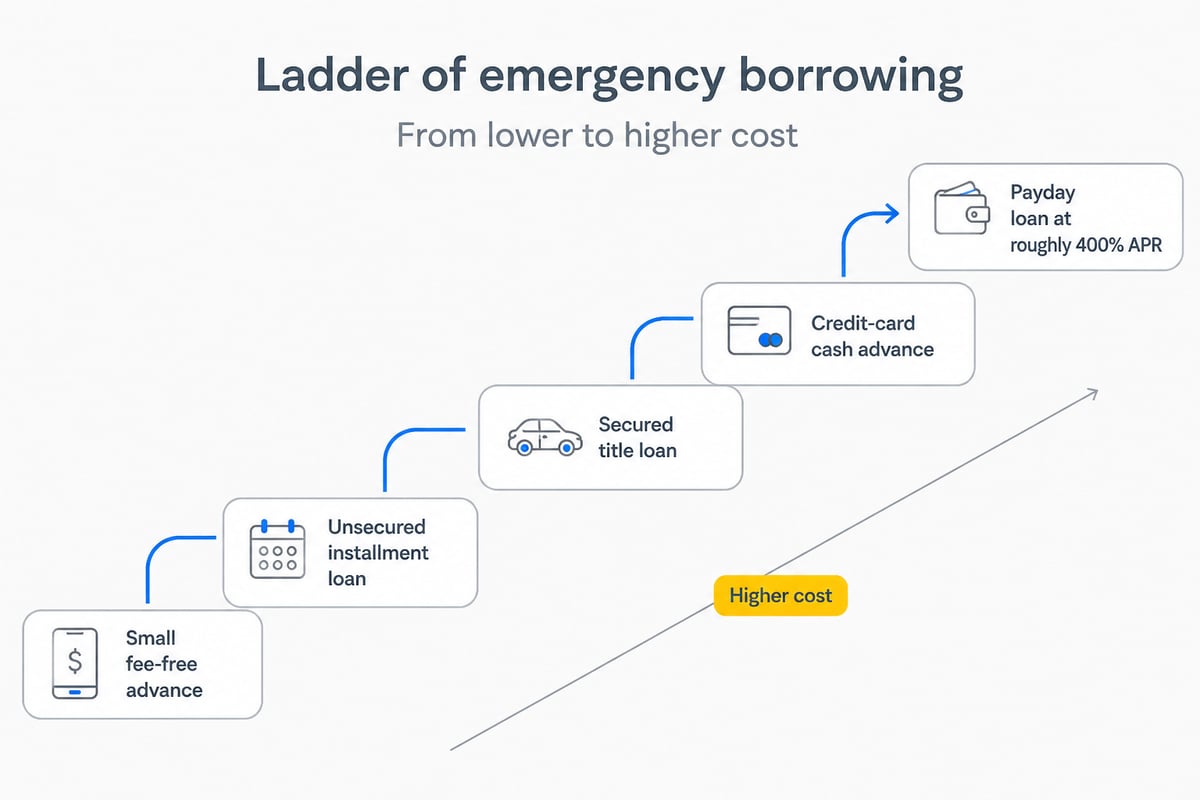
A credit-card cash advance lets you withdraw cash against your card's credit line, and it is one of the faster but costlier ways to borrow.
- Fee: commonly a percentage of the amount withdrawn
- APR: typically higher than the rate on purchases
- Interest: no grace period, so interest generally starts immediately
- Limit: often lower than your overall credit limit
Experian notes these cash advance costs in its emergency loan guidance. The fee is added to the amount you borrow before any interest accrues.
Best suited to: a short-notice cash need where a provider will not accept card payments, and only after you have compared the card's fee and APR.
Verdict: Acceptable for a small amount you can repay within weeks, not for anything longer.
8. Payday Loan
A payday loan is a short-term, high-cost loan that is not recommended for an emergency unless every other option has been exhausted.
- Typical size: often under $500
- Repayment term: around two weeks
- Cost: very high APRs, according to Experian
The combination of a short repayment window and a very high APR makes it easy to fall behind and roll the loan over, which can make it far more expensive than it first appears.
Best suited to: no recommended use. Compare the other seven items first.
Verdict: The highest-risk option on this list.
Side-by-Side Comparison
| Option | Reported amount | Reported APR | Term | Collateral |
|---|---|---|---|---|
| LendingPoint personal loan | $1,000 to $36,500 | 7.99% to 35.99% | 24 to 72 months | None stated |
| Experian marketplace | Varies by lender | 5.96% to 35.99% | 6 to 84 months | Varies |
| Experian Cash (Brigit) | $25 to $250 | No interest | Short term | None |
| Unsecured personal loan | Varies by lender | Varies by lender | Varies | None |
| Standard Financial Personal Loans | Confirm with Standard Financial | Confirm with Standard Financial | Confirm with Standard Financial | Confirm with Standard Financial |
| Standard Financial Title Loans | Confirm with Standard Financial | Confirm with Standard Financial | Confirm with Standard Financial | Vehicle title |
| Credit-card cash advance | Below card limit | Higher than purchases, plus 5% or more fee | Revolving | None |
| Payday loan | Often under $500 | Very high | About two weeks | None |
Which Personal Loan for Emergencies Fits Your Situation
Match the loan to the size and urgency of the expense, then confirm you can afford the monthly payment.
- Under $250 and due within days: a fee-free advance such as Experian Cash may cover it, depending on eligibility.
- $1,000 to $10,000 with fair or good credit: compare an unsecured personal loan across online lenders and the Experian marketplace.
- Credit history is the obstacle: speak with a lender that reviews your full situation, such as a local branch, rather than relying on an automated score alone.
- Cash needed from a card-only source: price the cash advance fee and APR first, and plan to repay quickly.
A personal loan for emergencies works best when the payment fits comfortably inside your monthly budget. Before accepting any offer, calculate the total repayment (monthly payment times number of months) and compare it with the amount you are borrowing.
Steps to Take Before You Apply
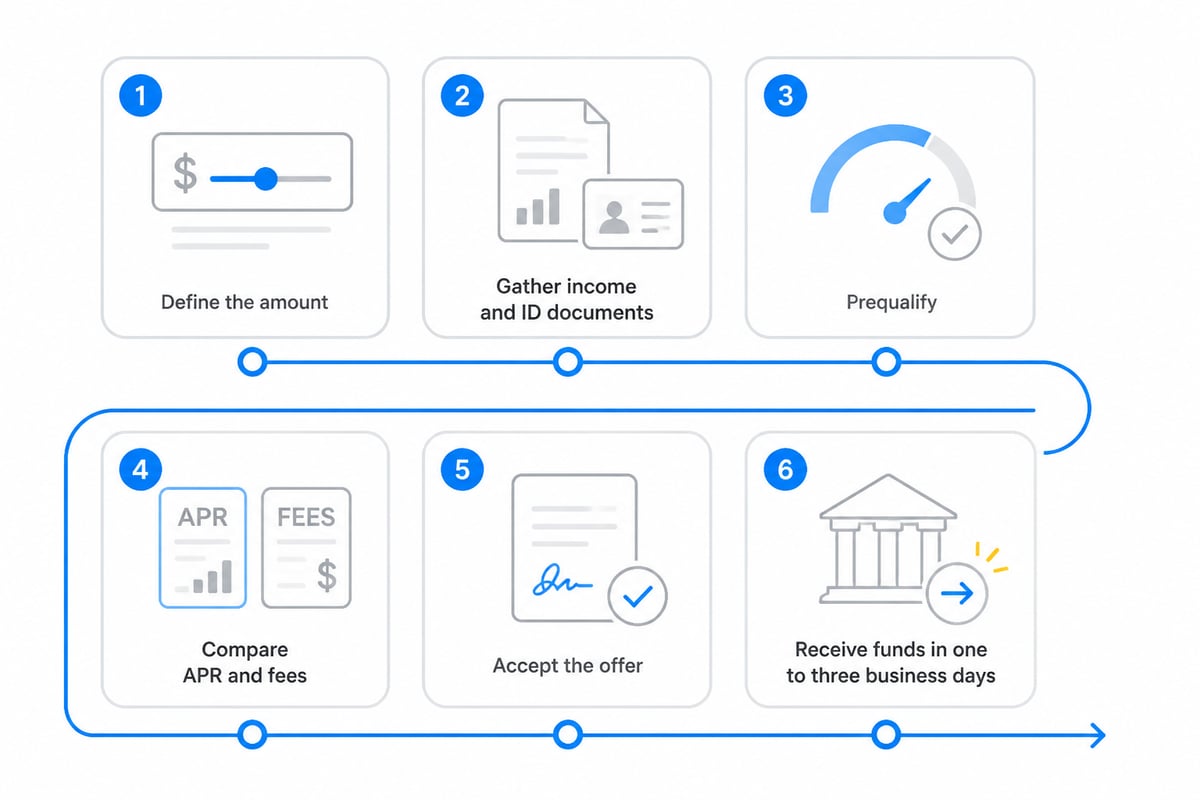
Preparing a few items in advance can shorten the time between approval and funding.
- Define the exact amount. Borrowing only what the emergency requires keeps interest costs down.
- Gather documents. Lenders commonly ask for identification, proof of income and bank account details.
- Check your credit reports. Look for errors that could be raising your rate.
- Prequalify where offered. Soft-pull prequalification lets you view estimated terms without a hard inquiry.
- Read the fee disclosure. Confirm the origination fee, any late fee and whether early payoff is penalty-free.
- Set up autopay. Missed payments on a new loan can compound an already stressful situation.
Frequently Asked Questions
Can I get a personal loan for emergencies with bad credit?
Yes, though your options narrow and costs rise. Lenders that review your whole situation, including branch-based consumer lenders, often work with past credit problems or limited credit. Expect a higher APR than a prime borrower would see.
How fast can emergency funds arrive?
Most lenders fund from the same day to three business days after approval, according to Experian. Delivery method and how quickly you return documents both affect timing.
Is a payday loan ever the best choice?
Rarely. With very high APRs and repayment due in about two weeks, nearly every alternative on this list costs less.
Your next step is to write down the exact amount you need and the monthly payment you can afford, then use those two numbers to compare offers. If your credit history has made approvals difficult, Standard Financial has branch offices across Louisiana, Mississippi, Tennessee and Georgia and works with people who have past credit issues or limited credit, so you can start an application to apply for a loan and have your situation heard in full. You can also review its personal loans, which include refinancing options and flexible financing plans for expenses such as home improvements, medical bills and education.

1 Comment
[…] off your personal loan Louisiana ahead of schedule saves significant interest and frees up monthly cash flow for other […]