
Relocating to a new home represents one of life's most significant transitions, yet the financial burden often catches people unprepared. Between security deposits, moving company fees, travel costs, and overlap in housing payments, the average American household faces expenses ranging from $2,000 to $8,000 for local moves and $5,000 to $15,000 for long-distance relocations. When savings fall short, a loan for moving expenses becomes a practical solution to bridge the gap and ensure a smooth transition to your new home.
Understanding Loan Options for Moving Expenses
Personal Unsecured Loans
Personal loans stand as the most common financing method for relocation costs. These unsecured loans provide a lump sum payment with fixed monthly installments over terms typically ranging from 12 to 60 months. Interest rates vary based on your credit profile, generally falling between 6% and 36%.
The primary advantage of using a loan for moving expenses through personal lending is flexibility. You receive funds directly into your account and can allocate them across multiple relocation needs without restriction. Unlike credit cards, personal loans offer predictable payment schedules and potentially lower interest rates for qualified borrowers.
Key benefits include:
- Fixed interest rates that won't increase during repayment
- Predictable monthly payments for easier budgeting
- No collateral requirements protecting your assets
- Quick approval and funding timelines (often 24-72 hours)
- Higher borrowing limits than credit cards
Home Equity Financing Options
Homeowners possess additional leverage through equity-based products. Home equity loans and lines of credit (HELOCs) tap into your property's value, typically offering lower interest rates than unsecured alternatives. However, these products require appraisals, involve longer approval processes, and use your home as collateral.
This option makes most sense for expensive relocations requiring $10,000 or more. The mortgage closing costs and timing considerations become important factors, especially when coordinating a simultaneous home purchase in your destination city.
| Loan Type | Typical APR | Approval Time | Collateral Required | Best For |
|---|---|---|---|---|
| Personal Loan | 6-36% | 1-3 days | No | Most relocations under $25,000 |
| Home Equity Loan | 5-12% | 2-4 weeks | Yes (home) | Large moves, home equity available |
| HELOC | 6-13% | 2-4 weeks | Yes (home) | Flexible draw periods |
| Credit Card | 15-29% | Instant | No | Emergency expenses only |
Calculating Your Moving Expense Budget
Essential Cost Categories
Understanding the complete scope of relocation expenses helps you determine the appropriate loan for moving expenses amount. Many people underestimate total costs by focusing only on the moving truck while overlooking numerous smaller expenses that accumulate quickly.
Professional moving services represent the largest single expense for most households. Interstate moves averaged $4,890 in 2026, while local relocations within the same state cost approximately $1,250. When researching movers, follow FTC guidance on avoiding moving scams by verifying registration numbers, obtaining written estimates, and avoiding companies demanding large cash deposits.
Housing transition costs include:
- Security deposits (typically one month's rent)
- First and last month's rent payments
- Utility connection fees and deposits
- Application and screening fees ($50-$100 per property)
- Temporary housing during transition periods
- Storage unit rentals for belongings
Travel expenses add another layer of costs. Whether driving or flying to your destination, factor in transportation, meals, lodging, and pet boarding or transport. A family of four relocating from Louisiana to Tennessee might spend $800-$1,500 on travel alone.
Hidden and Unexpected Costs
Beyond obvious expenses, several categories catch borrowers off guard. New furniture purchases often become necessary when existing pieces don't fit new floor plans. Vehicle registration and driver's license transfers in your new state involve fees ranging from $50 to $300. Professional cleaning services for your previous residence to secure deposit returns cost $200-$500 for thorough move-out cleaning.
Setting aside 15-20% of your estimated moving budget as a contingency buffer protects against unexpected expenses. This padding ensures your loan for moving expenses covers the full relocation without requiring additional borrowing at potentially unfavorable terms.
Eligibility Requirements and Application Process
Credit Score Considerations
Lenders evaluate several factors when reviewing loan for moving expenses applications, with credit scores playing the primary role. Most traditional lenders require minimum scores of 580-600 for approval, though rates improve significantly at higher tiers.
Credit score impact on loan terms:
- Excellent (720+): Qualify for rates between 6-12%, highest approval amounts
- Good (680-719): Expect rates of 10-18%, strong approval odds
- Fair (620-679): Rates typically 15-25%, may require additional documentation
- Poor (580-619): Higher rates of 20-36%, lower maximum amounts
Credit-challenged borrowers still have options. Specialized lenders focus on income verification and employment stability rather than exclusively relying on credit scores. Adding a creditworthy cosigner dramatically improves approval chances and secures better rates.
Income Verification and Debt-to-Income Ratios
Lenders assess your ability to repay through income documentation and debt-to-income (DTI) ratio calculations. DTI compares your total monthly debt payments to gross monthly income. Most lenders prefer ratios below 43%, though some accept up to 50% for well-qualified applicants.
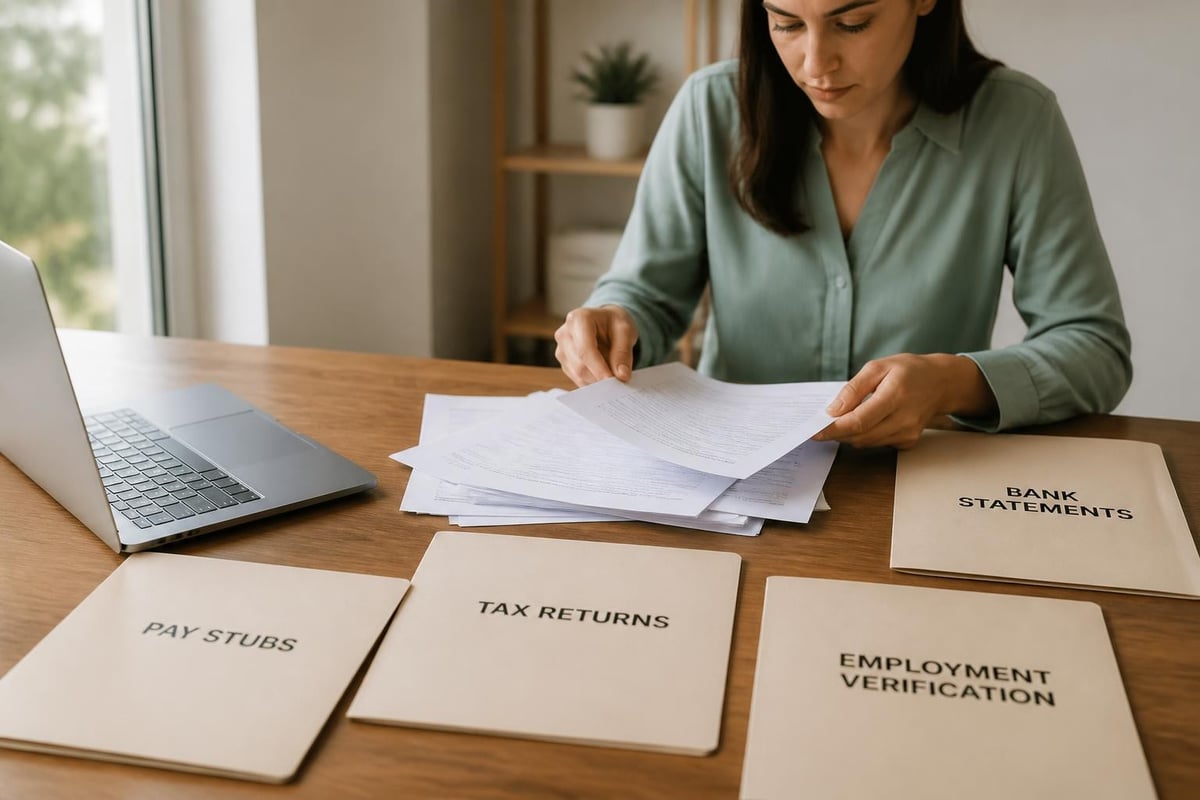
Required documentation typically includes recent pay stubs, tax returns from the previous two years, and bank statements covering 30-60 days. Self-employed borrowers need additional documentation such as profit and loss statements and business bank account records.
Employment stability matters considerably. Lenders prefer seeing at least two years with the same employer or in the same field. Recent job changes can raise concerns, though relocating for employment actually strengthens your application when you provide an offer letter confirming the new position.
Smart Borrowing Strategies for Relocation
Right-Sizing Your Loan Amount
Borrowing the minimum necessary amount saves substantially on interest costs. Create a detailed budget itemizing every relocation expense before applying. This prevents overborrowing and the temptation to use excess funds for non-moving purposes.
Consider timing strategically. If your employer provides relocation assistance or reimbursement, you might borrow less initially and use reimbursement payments to cover subsequent expenses or pay down the loan principal early. Many employers offer $5,000-$15,000 in relocation packages for professional positions.
Comparing Loan Offers Effectively
Never accept the first offer without comparison shopping. Request quotes from at least three lenders, examining the Annual Percentage Rate (APR) rather than just the interest rate. APR includes fees, providing a more accurate cost comparison.
Key comparison factors:
- Total interest paid over the loan term
- Monthly payment amount and affordability
- Prepayment penalties or fees for early payoff
- Origination fees (typically 1-8% of loan amount)
- Funding speed and disbursement method
Term length significantly impacts total cost. While longer terms reduce monthly payments, they increase total interest paid. A $7,000 loan for moving expenses at 15% APR costs $2,739 in interest over 60 months but only $1,504 over 36 months, despite higher monthly payments.
| Loan Amount | Term | Monthly Payment | Total Interest | Total Repayment |
|---|---|---|---|---|
| $7,000 | 24 months | $343 | $1,023 | $8,023 |
| $7,000 | 36 months | $243 | $1,504 | $8,504 |
| $7,000 | 48 months | $194 | $2,018 | $9,018 |
| $7,000 | 60 months | $167 | $2,739 | $9,739 |
Alternative Funding Sources to Consider
Employer Relocation Assistance Programs
Before pursuing a loan for moving expenses, thoroughly investigate employer-sponsored relocation benefits. Many companies offer assistance that covers some or all moving costs, particularly for positions requiring interstate or international relocation.
Relocation packages vary widely but commonly include direct payment to moving companies, mileage reimbursement, temporary housing allowances, and home sale assistance. Executive positions might offer $50,000 or more in comprehensive packages, while entry-level professional positions typically provide $3,000-$7,000.
Tax implications require attention. Unlike past years, most employer-paid moving expenses became taxable income starting in 2018, except for active-duty military members. Understanding IRS guidance on moving expense deductibility helps you plan for potential tax liabilities and adjust your borrowing needs accordingly.
Military-Specific Benefits
Service members relocating for permanent change of station (PCS) orders receive substantial government support. The military dislocation allowance and PCS benefits cover most relocation costs through direct reimbursement systems.
Dislocation Allowance (DLA) provides funds to offset expenses not otherwise covered, with amounts varying by rank and dependent status. The military also arranges and pays for household goods transportation, temporary lodging, and travel to the new duty station. Most military families don't require a loan for moving expenses when utilizing these benefits fully.
Active-duty members retain the ability to deduct unreimbursed moving expenses on their tax returns, making careful documentation of out-of-pocket costs essential. Reference IRS Form 3903 and instructions for specific guidance on calculating and claiming these deductions.
Community Resources and Non-Profit Assistance
Several organizations provide relocation assistance for specific populations. Non-profit credit counseling through the National Foundation for Credit Counseling offers budgeting guidance, financial planning for major expenses, and connections to local assistance programs.
Victims of domestic violence can access relocation grants through organizations like the National Domestic Violence Hotline and state-specific victim assistance programs. These funds help survivors establish safe housing in new locations without requiring repayment.
Low-income families qualifying for Section 8 housing vouchers sometimes receive relocation assistance when moving to opportunity areas. The portability features of housing choice vouchers enable families to relocate while maintaining rental assistance, though coordination between housing authorities requires advance planning.
Managing Loan Repayment Effectively
Building Repayment Into Your New Budget
Successfully managing a loan for moving expenses requires integration into your post-relocation budget. Housing costs typically increase with moves, especially when relocating to higher cost-of-living areas. Your loan payment represents an additional fixed expense for the repayment term.
Financial experts recommend maintaining housing costs below 30% of gross income and total debt payments under 36%. When your new rent or mortgage payment increases, the loan payment might push you above ideal ratios temporarily. Creating a detailed budget before relocating helps you confirm affordability.
Post-move budgeting priorities:
- Essential housing costs (rent/mortgage, utilities)
- Loan for moving expenses monthly payment
- Transportation in new location
- Food and household necessities
- Emergency fund rebuilding
Accelerated Repayment Strategies
Paying off your moving loan quickly minimizes total interest costs. Whenever possible, make extra payments toward principal. Even modest additional amounts create substantial savings over time.
A practical approach involves allocating any unexpected income directly to loan principal. Tax refunds, work bonuses, or gift money can dramatically shorten your repayment timeline. On a $7,000 loan at 15% APR with 36-month term, adding just $50 monthly to your $243 payment saves $308 in interest and eliminates the loan six months early.
Set up automatic payments to avoid late fees and potential credit score damage. Many lenders offer small interest rate reductions (typically 0.25-0.50%) for enrolling in autopay, creating immediate savings.
Regional Considerations for Southern Relocations
Moving Within Louisiana, Mississippi, Tennessee, and Georgia
Relocating within the Southeast presents unique opportunities and challenges. Housing costs remain moderate compared to coastal markets, potentially reducing the loan amount needed. The average apartment deposit in Louisiana costs $800-$1,200, significantly less than equivalent properties in high-cost states.
Interstate moves within the region face simpler logistics than cross-country relocations. Driving distances between major cities like New Orleans, Memphis, Atlanta, and Jackson remain manageable for self-move options. Renting a moving truck for an in-region move costs $500-$1,500 compared to $3,000-$6,000 for coast-to-coast relocations.
Climate considerations affect timing and costs. Summer months bring intense heat and humidity, making physical moving more challenging but typically reducing competition for movers and rental properties. Hurricane season (June through November) introduces weather risk for Gulf Coast moves, making insurance considerations more important.
Local Lending Relationships and Community Banking
Establishing relationships with regional lenders often produces better loan for moving expenses terms than national online lenders. Community banks and credit unions in Louisiana, Mississippi, Tennessee, and Georgia frequently offer competitive rates for existing customers and new residents establishing local banking relationships.
These institutions understand regional employment markets and cost-of-living factors. A Memphis-based lender recognizes that a $55,000 salary provides comfortable middle-class living, while national lenders might view the same income skeptically. This local knowledge can translate into better approval odds and terms.
Protecting Yourself From Predatory Lending
Identifying High-Risk Loan Products
Not all moving expense financing creates equal outcomes. Certain loan products carry excessive costs and risks that can trap borrowers in cycles of debt. Payday loans, title loans, and rent-to-own arrangements should be avoided for relocation financing despite their accessibility.
Payday loans charge effective APRs exceeding 400%, turning a $2,000 moving expense into thousands in fees over just months. Title loans risk vehicle repossession, leaving you without transportation in your new location. These products target financially vulnerable consumers with urgent needs.
Red flags indicating predatory lending:
- APRs exceeding 36% for unsecured personal loans
- Loan amounts significantly larger than requested
- Pressure to borrow more than needed
- Requests for upfront fees before approval
- Lack of clear written terms and conditions
- Reluctance to explain total costs and repayment schedule
Reading the Fine Print
Carefully review all loan documents before signing. Pay particular attention to prepayment penalties, which some lenders charge if you pay off the loan early. These fees undermine your ability to save on interest through accelerated repayment.
Origination fees deserve scrutiny. While 1-2% represents reasonable loan processing costs, fees exceeding 5% signal potential overpricing. Some lenders deduct origination fees from disbursement, meaning a $7,000 loan with 8% origination only provides $6,440 in usable funds while requiring repayment of the full $7,000 plus interest.
Understand default consequences thoroughly. While you never plan to default, knowing the penalties and processes protects you if financial emergencies arise. Some lenders charge substantial late fees, report after a single missed payment, or immediately accelerate the entire balance due.
Special Circumstances Requiring Additional Consideration
Relocating During Credit Rebuilding
Consumers actively rebuilding credit face additional challenges when seeking a loan for moving expenses. Recent bankruptcies, foreclosures, or patterns of delinquencies limit options and increase costs. However, relocation sometimes becomes necessary despite credit challenges.
Specialized lenders focus on current income and employment rather than exclusively emphasizing credit history. These lenders accept higher risk in exchange for higher interest rates, typically 24-36% for credit-challenged borrowers. While expensive, these loans provide access when traditional lenders decline applications.
Secured loan options expand possibilities. Using a vehicle title (not a predatory title loan, but a legitimate secured installment loan) or savings account as collateral reduces lender risk, improving approval odds and potentially reducing rates by several percentage points.
Coordinating Multiple Major Financial Events
Timing a move alongside other significant financial events complicates borrowing decisions. Purchasing a home while relocating involves careful coordination to avoid jeopardizing mortgage approval. Mortgage lenders scrutinize new debt carefully during the underwriting period.
If buying a home in your destination city, delay applying for a loan for moving expenses until after mortgage closing. New debt increases your DTI ratio and might disqualify you from the mortgage or reduce your approved amount. Most moving costs can be managed through savings, credit cards, or after-closing loans without risking the home purchase.
Career transitions require similar attention. Changing jobs and relocating simultaneously presents logical necessity but creates lender concern about income stability. Provide comprehensive documentation including your offer letter, first pay stub in the new position, and explanation of the career move to strengthen your application.
Maximizing Your Relocation Success
Creating a Comprehensive Moving Timeline
Successful relocations balance numerous tasks across compressed timeframes. Starting your loan application 4-6 weeks before your move date ensures funds arrive when needed. This timeline accommodates potential delays in approval or funding while leaving room for comparison shopping.
8-week moving timeline with financing:
- Week 8: Research lenders and obtain pre-qualification quotes
- Week 7: Finalize moving budget and required loan amount
- Week 6: Submit formal applications to top 2-3 lenders
- Week 5: Compare offers and select best loan terms
- Week 4: Complete loan and receive funding
- Week 3: Book moving company and begin packing
- Week 2: Confirm housing arrangements at destination
- Week 1: Execute move and settle into new home
Leveraging Professional Financial Guidance
Complex relocations benefit from professional financial planning assistance. Credit counselors help you assess whether borrowing makes sense given your complete financial picture or if delaying the move to build savings represents a better choice.
Financial advisors can model different scenarios showing long-term impacts of various borrowing decisions. Comparing a $7,000 loan paid over three years versus delaying your move six months to save might reveal surprising outcomes when factoring in opportunity costs, interest expenses, and career advancement timing.
Research from the Urban Institute on responsible relocation demonstrates that well-planned, adequately funded moves produce better long-term outcomes than crisis-driven relocations executed without sufficient resources. Taking time to secure appropriate financing through a loan for moving expenses contributes to relocation success.
Understanding your financing options transforms moving from an overwhelming financial burden into a manageable transition. Whether you're relocating for career advancement, family needs, or a fresh start, having the right funding in place ensures you can focus on settling into your new community rather than worrying about expenses. If you're planning a move within Louisiana, Mississippi, Tennessee, or Georgia and need flexible financing to cover relocation costs, Standard Financial offers personal loans designed to help you successfully transition to your new home, even if past credit challenges have limited your options elsewhere.

No comment yet, add your voice below!