
Personal installment loans give you a lump sum up front and a fixed monthly payment over a set period, which makes them one of the easiest forms of borrowing to plan around. The right option depends on your credit profile, how much you need and how long you want to repay, so the comparison below covers six choices, from online lenders to a branch lender serving Louisiana, Mississippi, Tennessee and Georgia.
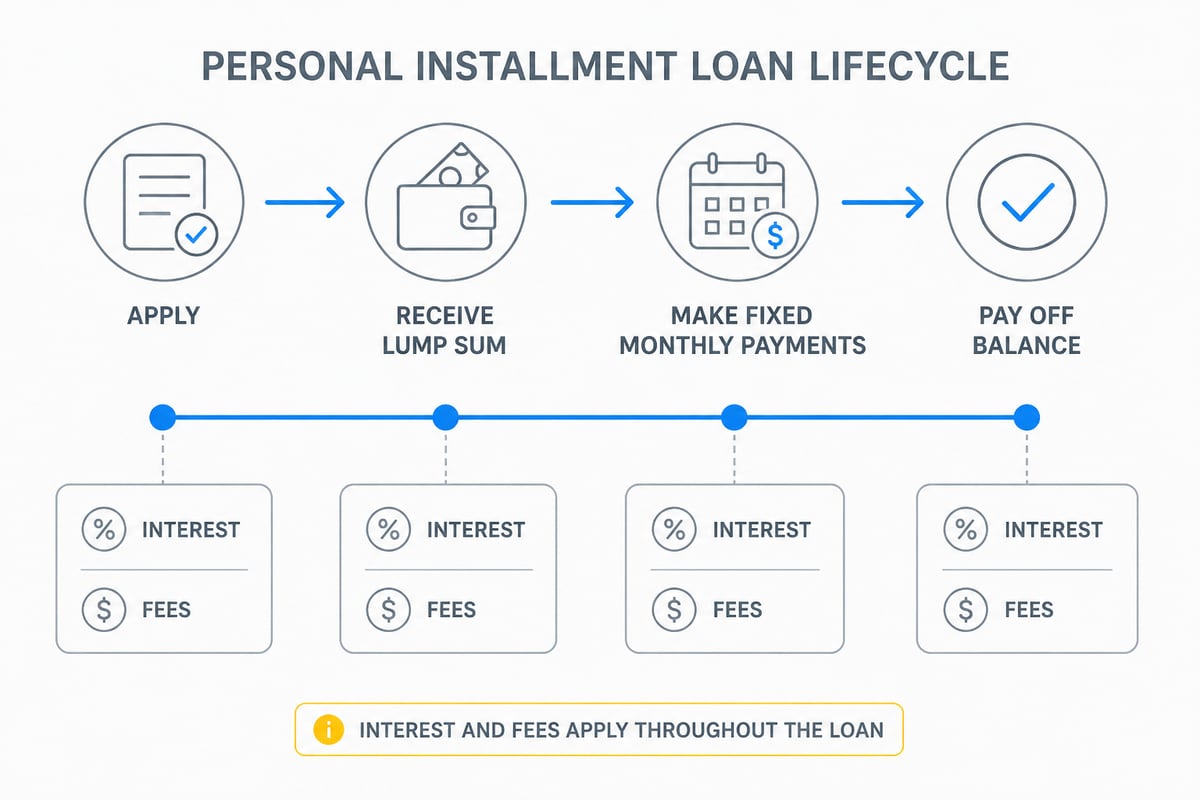
Most personal loans are unsecured, paid out as a lump sum and repaid in fixed monthly installments, with terms that typically run one to five years, according to the Citi Learning Center. Terms vary by lender, and the lender you choose matters most if your credit history is thin or damaged.
How personal installment loans work and what they cost
A personal installment loan costs you the interest rate plus any fees, spread across equal monthly payments until the balance reaches zero.
Three numbers drive the total cost:
- APR: the yearly rate including interest and most fees.
- Origination fee: a one-time charge, often deducted from your proceeds before you receive funds.
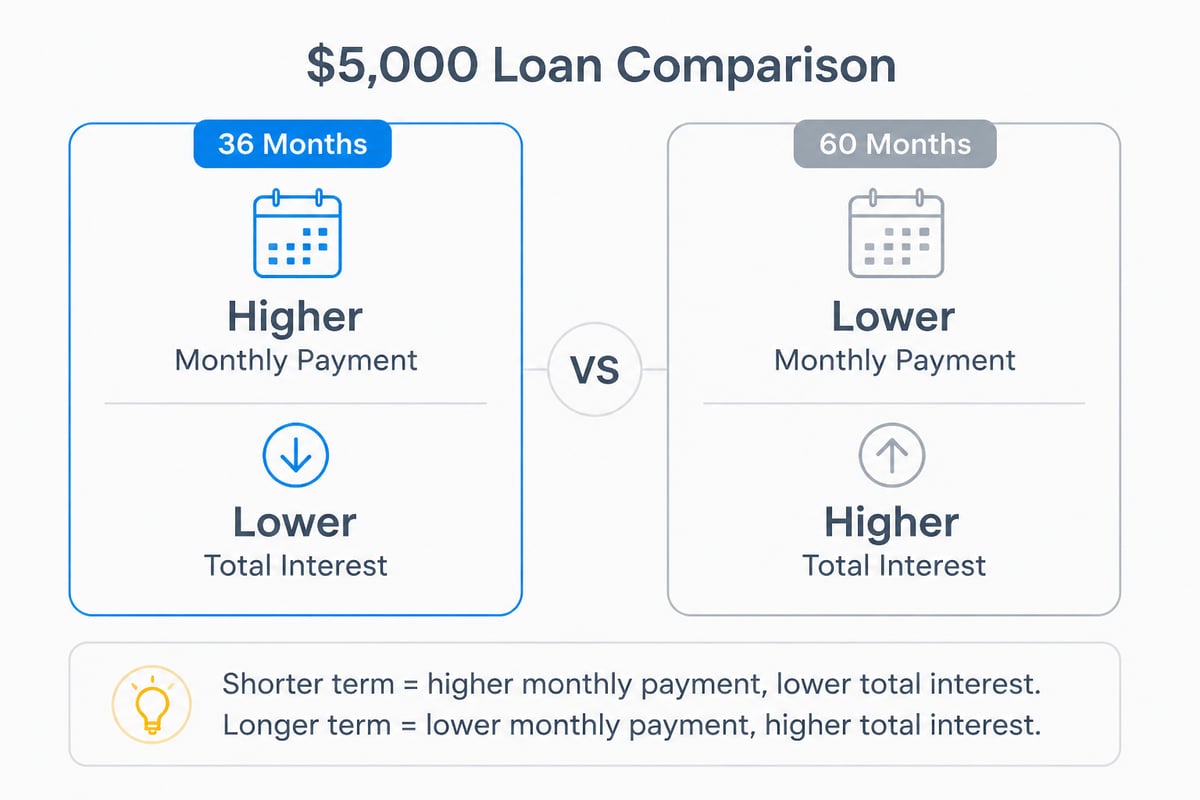
- Term: a longer term lowers the monthly payment but increases total interest paid.
For a sense of scale, Citi's learning center estimates that a $5,000 loan repaid over 36 months at 10% interest carries a monthly payment of about $161.34. Stretching the same balance to 60 months would lower the payment but add months of interest. Set a monthly ceiling first, then work backward to a term you can sustain.
1. SoFi Personal Loan
SoFi Personal Loan is a fixed-rate personal installment loan for larger borrowing needs, with amounts from $5,000 to $100,000.
- Repayment terms: 2 to 7 years
- Fees: no origination, prepayment or late fees
- Rate type: fixed
This loan suits borrowers with strong credit who want to finance a large expense over a longer period. The absence of origination and late fees keeps the cost to the interest rate alone. The $5,000 minimum is high for smaller needs, and the profile favors strong credit.
Verdict: A strong choice for large loans if your credit is excellent; a poor fit for small amounts or damaged credit.
2. Upgrade Personal Loan
Upgrade Personal Loan accepts credit scores as low as 580 and lets you apply with a co-signer or co-borrower, which widens access for imperfect credit.
- Loan amounts: $1,000 to $75,000
- Credit: scores as low as 580 accepted
- Origination fee: 1.85% to 9.99%
The origination fee range is wide, so check the exact figure before accepting an offer. The gap between the low and high end of that fee range is large, so the upfront cost can vary widely depending on your offer. This option suits borrowers rebuilding credit who can bring in a co-borrower with a stronger profile to improve their terms.
Verdict: Useful for fair credit with a co-borrower, provided you compare the fee against the rate.
3. Upstart Personal Loan
Upstart Personal Loan uses nontraditional underwriting and sets a minimum credit score of 300 in most states, so people with limited credit history can qualify.
- Loan amounts: $1,000 to $75,000
- Repayment terms: 36 or 60 months
- Minimum credit score: 300 in most states
The 36-month and 60-month choices are simple to compare: the shorter term costs less in total interest, while the longer term lowers the monthly payment. This loan suits borrowers with low scores or little credit history, including those consolidating higher-interest debt into one payment.
Verdict: A good entry point for thin or low credit files; confirm availability and final terms in your state.
4. LendingPoint Personal Loan
LendingPoint Personal Loan offers repayment terms of 24 to 60 months, and funding may arrive as soon as the next business day after approval.
- Repayment terms: 24 to 60 months
- Funding speed: as soon as the next business day after approval
Speed is the draw here. This loan suits borrowers facing a time-sensitive expense, such as an urgent car repair or medical bill, who also want a repayment period long enough to keep payments manageable. Loan amounts and rates are not listed here, so request a quote before committing.
Verdict: Best when timing is tight and you want a mid-length term.
5. Standard Financial Personal Loans
Standard Financial Personal Loans are personal loans for people with limited or impaired credit, and they include refinancing options.
Standard Financial operates branch offices across Louisiana, Mississippi, Tennessee and Georgia. Its approach gives customers a chance to explain their credit situation and builds a tailor-made solution, rather than relying only on an automated score. It works with people who have past credit problems or limited credit, and it offers flexible financing plans.
This option suits borrowers who want to discuss their circumstances with a lender in person and who may want to refinance an existing balance. For loan sizes, rates and terms, check Standard Financial's product pages or contact a branch directly.
Verdict: A practical fit for borrowers whose credit history is the main obstacle with online lenders.
6. Standard Financial Title Loans
Standard Financial Title Loans are loans secured by a vehicle title, offered in Baton Rouge.
Because the loan is secured, the lender can take the vehicle if you default, so the risk is higher than with an unsecured installment loan. This option suits borrowers in the Baton Rouge area who own a vehicle outright and cannot qualify for an unsecured loan. Ask about terms, costs and what happens if you miss a payment before signing. Compare it against the unsecured options above first.
Verdict: A last-resort choice for Baton Rouge vehicle owners; weigh it against unsecured alternatives first.
Comparing personal installment loans side by side
This table summarizes the six options on the attributes listed for each.
| Loan | Amounts | Terms | Credit focus | Notable feature |
|---|---|---|---|---|
| SoFi Personal Loan | $5,000 to $100,000 | 2 to 7 years | Excellent credit | No origination, prepayment or late fees |
| Upgrade Personal Loan | $1,000 to $75,000 | Not listed | Scores as low as 580 | Co-borrower allowed; 1.85% to 9.99% origination fee |
| Upstart Personal Loan | $1,000 to $75,000 | 36 or 60 months | Minimum score of 300 in most states | Nontraditional underwriting |
| LendingPoint Personal Loan | Not listed | 24 to 60 months | Not listed | Funding as soon as next business day |
| Standard Financial Personal Loans | See product pages | See product pages | Limited or impaired credit | Refinancing options; branches in LA, MS, TN, GA |
| Standard Financial Title Loans | See product pages | See product pages | Vehicle title as security | Offered in Baton Rouge |
A large national bank as a benchmark
A bank loan shows what a prime-credit borrower might be offered, which helps you judge whether other quotes are reasonable. Citi personal loans range from $2,000 to $30,000 with terms of 12 to 60 months, and advertised APRs were 10.24% to 18.49% as of September 29, 2026, per Citi. Citi says approved borrowers may receive funds in as little as two business days, and it offers a 0.25 percentage-point APR discount for enrolling in automatic payments at origination.
Those rates assume strong credit. If your score is lower, expect higher pricing, and use these figures only as a yardstick. When an online lender quotes you an APR, place it against the 10.24% to 18.49% range. A quote near the bottom of that band suggests you are being priced like a prime borrower, while one well above the top may reflect your credit profile or a heavy fee load. Also compare ceilings: Citi's $30,000 maximum is lower than the maximums offered by SoFi, Upgrade and Upstart, so larger needs point toward those lenders.
How to choose the right loan for your budget
Choosing well comes down to a short sequence of checks you can complete in an afternoon.
- Set your payment ceiling. Decide the most you can pay each month without strain, using your take-home income minus fixed bills. Include rent or mortgage, utilities, insurance and existing debt payments, then leave a cushion for months when expenses run high. If the loan payment would consume that cushion, the amount or term needs to change.
- Pick the shortest term that fits. A shorter term means less total interest. Using the Citi learning center figure, a $5,000 loan over 36 months at 10% carries an estimated payment of about $161.34 a month. If that payment fits your ceiling, a 36-month term beats stretching to 60 months, because every extra month adds interest.
- Check the full cost. Compare APR and origination fees, not just the monthly figure. A fee deducted from your proceeds also means you receive less than you borrow, so you may need to request a slightly larger amount to cover the full expense.
- Look for prepayment penalties. You should be able to pay early without a charge. SoFi, for example, lists no prepayment fee, which lets you clear the balance sooner if your income improves.
- Prefer unsecured over secured. Putting a vehicle at risk raises the stakes.
What to do if your credit is limited or damaged
Past credit problems narrow your choices but do not close them. Online lenders that accept lower scores often charge higher origination fees, so read the fee line carefully. A co-borrower can improve your offer where a lender allows one.
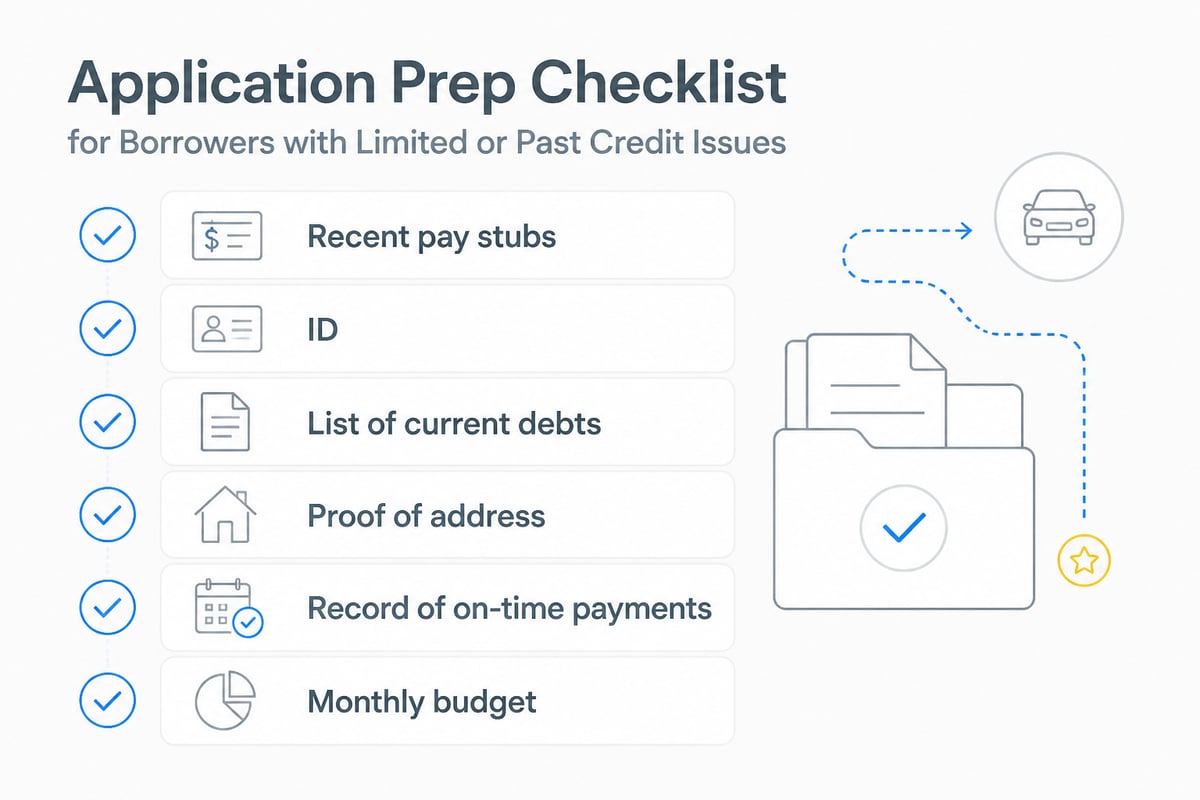
A lender that reviews your situation personally can sometimes offer more than a score-only decision. If you already carry a high-cost loan, ask about refinancing it into a fixed, lower payment. Before you apply, gather recent pay stubs, a list of current debts and a record of your on-time payments, since that context helps a loan officer see beyond a three-digit number.
Frequently asked questions
Are personal installment loans secured or unsecured?
Most are unsecured, meaning no collateral is required. A title loan is secured by a vehicle title and carries the added risk of losing the vehicle if you default.
Can I get a loan with a low credit score?
Yes, some lenders accept scores as low as 580, and one lists a minimum of 300 in most states. Expect higher fees or rates, and compare offers carefully.
How fast can I receive funds?
It varies by lender. LendingPoint says funding may arrive as soon as the next business day after approval, and Citi says approved borrowers may receive funds in as little as two business days.
Should I choose a longer term to lower my payment?
A longer term reduces the monthly payment but increases total interest. Choose the shortest term whose payment still fits comfortably in your budget.
Your next step is to calculate the monthly payment you can afford and write down your current debts so you can compare real offers. If you live in Louisiana, Mississippi, Tennessee or Georgia, Standard Financial, a consumer lender with multiple branch offices, can build a tailor-made plan around your credit history, with flexible financing plans, refinancing options and personal loans for home improvements, medical expenses and education. Read about its Personal Loans, then apply for a loan with Standard Financial to talk through your situation with a lender.

No comment yet, add your voice below!