

Building or rebuilding credit can feel overwhelming, especially when past financial challenges have limited your options. A secured credit card offers a practical pathway for establishing creditworthiness when traditional credit cards remain out of reach. Unlike conventional credit cards that extend credit based solely on your credit history, secured cards require an upfront deposit that serves as collateral. This fundamental difference makes secured cards accessible to individuals with limited credit history or those recovering from financial setbacks, providing a stepping stone toward improved financial health and expanded borrowing opportunities.
Understanding the Basic Mechanics of Secured Credit Cards
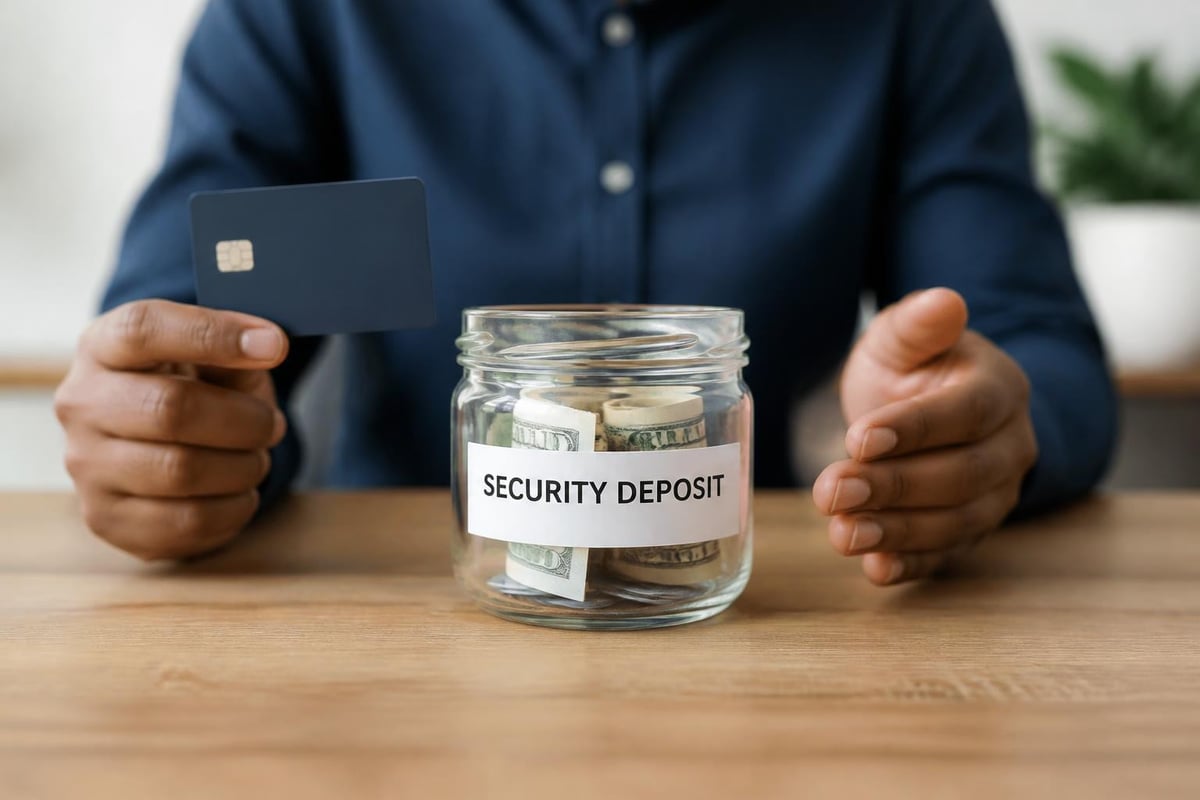
Understanding how a secured credit card works begins with grasping the relationship between your security deposit and your credit limit. When you open a secured credit card account, you provide a refundable cash deposit to the card issuer. This deposit typically ranges from $200 to $2,500, depending on the issuer's requirements and your financial capacity.
The deposit amount directly determines your credit limit in most cases. If you deposit $500, you receive a $500 credit limit. Some issuers may offer slightly higher limits than your deposit, but this practice varies significantly across providers. The deposit remains in a separate account held by the card issuer, serving as protection against potential default.
Key components of secured card functionality include:
- Initial security deposit that establishes your credit limit
- Monthly billing cycles identical to traditional credit cards
- Interest charges on carried balances at specified APR rates
- Minimum payment requirements due each billing period
- Credit bureau reporting that builds your credit history
Your security deposit does not pay your monthly bill. This represents a common misconception among first-time secured card users. You must make regular payments from your income or other funds, just as you would with an unsecured credit card. The deposit simply provides the issuer with financial security.
The Application and Approval Process
The application process for secured cards differs substantially from traditional credit card applications, primarily regarding qualification criteria. Most secured card issuers maintain less stringent credit requirements because the security deposit minimizes their financial risk. Individuals with credit scores below 580, those with no credit history, or people recovering from bankruptcy often qualify when they might face rejection for unsecured cards.
Required Documentation and Initial Steps
Applicants typically need to provide basic personal information, including Social Security number, current address, employment details, and income verification. Some issuers conduct soft credit checks that do not impact your credit score, while others perform hard inquiries. The approval timeline usually ranges from immediate to several business days.
Once approved, you must fund your security deposit before the card becomes active. Payment methods vary by issuer but commonly include:
- Bank account transfers (ACH)
- Debit card payments
- Wire transfers
- Money orders or cashier's checks
After the issuer receives and processes your deposit, they activate your card and establish your credit limit. The entire process from application to card activation typically takes seven to fourteen business days, though some digital-first issuers offer faster timelines.
How Credit Reporting Builds Your Financial Profile
The primary value of understanding how a secured credit card works lies in recognizing its credit-building potential. Secured cards function identically to unsecured cards regarding credit bureau reporting. Your payment history, credit utilization, account age, and overall account management appear on your credit reports from Experian, Equifax, and TransUnion.
Payment history constitutes approximately 35% of your FICO credit score calculation, making it the most influential factor. Each on-time payment strengthens your credit profile, while late payments inflict significant damage. Credit utilization, representing 30% of your score, measures how much available credit you use relative to your total limit.
| Credit Score Factor | Percentage Impact | Secured Card Influence |
|---|---|---|
| Payment History | 35% | Direct through monthly payments |
| Credit Utilization | 30% | Controlled by spending habits |
| Credit History Length | 15% | Grows with account age |
| Credit Mix | 10% | Adds installment diversity |
| New Credit | 10% | Initial inquiry impact only |
Maintaining utilization below 30% optimizes your credit score, though staying under 10% produces even better results. With a $500 credit limit, this means keeping balances below $150 for optimal scoring, or ideally below $50.
Strategic Usage for Maximum Credit Building
Knowing how a secured credit card works mechanically represents only half the equation. Strategic usage amplifies the credit-building benefits while minimizing costs. The most effective approach involves treating your secured card as a financial tool rather than free money.
Monthly Spending and Payment Strategies
Charge small, manageable purchases that you can pay in full each billing cycle. This approach accomplishes multiple objectives simultaneously: it demonstrates responsible credit usage to bureaus, avoids interest charges, and prevents debt accumulation. Many successful secured card users designate their card for specific recurring expenses like gas, groceries, or subscription services.
Optimal payment practices include:
- Paying the full statement balance before the due date
- Setting up automatic payments to prevent missed deadlines
- Making payments twice monthly to maintain low reported utilization
- Monitoring statements for unauthorized charges or errors
- Keeping physical receipts until charges appear on statements
The timing of your payment relative to your statement closing date affects your reported utilization. Card issuers typically report your balance to credit bureaus on your statement closing date, not your payment due date. Paying before the statement closes results in lower reported utilization, potentially boosting your score more effectively.
Fees, Interest Rates, and Cost Considerations
Understanding the financial obligations associated with secured cards helps you evaluate whether a particular card serves your needs. While secured cards provide access to credit building, they often carry higher fees and interest rates than prime unsecured cards due to the issuer's target market.
Common fees associated with secured credit cards include:
- Annual fees ranging from $0 to $99
- Application fees charged by some issuers (typically $20-$50)
- Monthly maintenance fees assessed by certain providers
- Foreign transaction fees for international purchases
- Late payment penalties for missed due dates
- Over-limit fees if you exceed your credit line
Annual Percentage Rates (APRs) on secured cards typically range from 18% to 28% in 2026, significantly higher than rates available to prime borrowers. However, these rates become irrelevant when you pay your full balance each month, eliminating interest charges entirely.
Comparing multiple secured card offers reveals substantial variation in fee structures. Some issuers specialize in low-fee secured cards to attract credit builders, while others impose multiple charges that can undermine your financial progress. Calculate the total annual cost of ownership before committing to any particular card.
Graduation to Unsecured Status and Deposit Return
One of the most satisfying aspects of learning how a secured credit card works involves understanding the transition to unsecured status. Many secured card issuers periodically review accounts for potential upgrade to unsecured cards. This graduation process returns your security deposit while maintaining or potentially increasing your credit limit.
Timeline and Qualification Criteria
Review periods vary by issuer, with most conducting evaluations between six and eighteen months after account opening. The qualification criteria typically include:
- Consistent on-time payment history with no late payments
- Demonstrated responsible credit utilization patterns
- Improved credit score since account opening
- Stable income verification
- Absence of derogatory marks on other credit accounts
Some issuers automatically graduate qualifying accounts, while others require cardholders to request reviews. Proactive communication with your card issuer about graduation timelines and requirements helps you plan your credit-building journey effectively.
| Issuer Practice | Typical Timeline | Cardholder Action Required |
|---|---|---|
| Automatic Review | 6-12 months | None |
| Request-Based | 12-18 months | Contact customer service |
| Score-Triggered | Variable | Maintain threshold score |
| Hybrid Model | 8-15 months | Opt-in for consideration |
Upon graduation, your deposit returns either as a check, statement credit, or direct deposit to your linked bank account. The timeline for receiving your deposit typically ranges from one to three billing cycles after approval for graduation.
Common Mistakes That Undermine Credit Building
Even when you understand how a secured credit card works theoretically, practical execution challenges can derail your credit-building efforts. Recognizing common pitfalls helps you avoid setbacks that delay your financial progress.
Missing payment deadlines represents the most damaging mistake secured cardholders make. A single payment more than 30 days late can decrease your credit score by 60 to 110 points, depending on your starting score. This damage persists on your credit report for seven years, though its impact diminishes over time.
Additional mistakes to avoid:
- Maxing out your credit limit regularly
- Making only minimum payments and carrying balances
- Closing the account immediately after graduation
- Applying for multiple credit products simultaneously
- Ignoring statement errors or fraudulent charges
- Using the card for cash advances when available
The temptation to view your credit limit as available spending money particularly affects individuals new to credit management. Your credit limit represents the maximum you can borrow, not a spending target. Maintaining substantial available credit demonstrates financial restraint that scoring models reward.
Selecting the Right Secured Card for Your Situation
The secured credit card market offers diverse options with varying features, fees, and benefits. Selecting the optimal card for your circumstances requires evaluating multiple factors beyond the security deposit requirement. Your choice should align with your credit-building goals, financial capacity, and long-term plans.
Key Evaluation Criteria
When comparing secured card options, prioritize cards that report to all three major credit bureaus. Some secured cards only report to one or two bureaus, limiting your credit-building impact. Verify reporting practices directly with the issuer before submitting your application.
Consider the graduation policy and timeline explicitly. Cards offering clear paths to unsecured status with reasonable timelines provide better value than those requiring indefinite secured status. Some issuers never graduate secured cardholders, instead requiring you to apply for a separate unsecured product.
Minimum and maximum deposit requirements affect accessibility. While some cards accept deposits as low as $200, others require $500 or more to open an account. Higher deposit options benefit individuals ready to establish larger credit limits, as higher limits provide more flexibility while maintaining low utilization ratios.
Additional features that distinguish quality secured cards include:
- Credit score monitoring and educational resources
- Rewards programs offering cash back or points
- Mobile app functionality for convenient management
- Fraud protection and zero liability policies
- Options to increase credit limit with additional deposits
For residents throughout Louisiana, Mississippi, Tennessee, and Georgia facing credit challenges, secured cards offer accessible entry points for rebuilding financial standing. Whether recovering from medical debt, managing past credit issues, or establishing credit for the first time, the right secured card provides measurable progress toward your financial goals.
Impact on Future Borrowing Opportunities
Understanding how a secured credit card works extends to recognizing its long-term effects on your borrowing capacity. The credit history you establish with responsible secured card usage influences future loan approvals, interest rates, and credit limits across all credit products.
Lenders evaluating applications for auto loans, mortgages, personal loans, or unsecured credit cards examine your payment patterns, account age, and credit utilization. A well-managed secured card demonstrates creditworthiness even when your credit score remains below prime thresholds. This documented responsibility can differentiate you from applicants with similar scores but limited positive payment history.
The relationship between secured card usage and loan approval manifests in several ways:
- Payment history validation proves you meet financial obligations consistently
- Credit mix diversification shows experience managing revolving credit
- Utilization discipline indicates responsible debt management capabilities
- Account longevity establishes a track record over time
- Score improvement trajectory demonstrates upward financial momentum
Auto lenders, mortgage providers, and personal loan issuers typically prefer applicants with at least twelve months of positive credit history. Your secured card can provide this foundation when other credit products remain unavailable. The combination of on-time payments and low utilization creates a compelling narrative of financial responsibility.
Managing Multiple Financial Products Simultaneously
As your credit improves through secured card usage, you may gain access to additional credit products or existing loan obligations. Understanding how a secured credit card works within a broader financial portfolio helps you maintain progress across all accounts.
Juggling multiple credit obligations requires organizational systems that prevent missed payments or confusion. Consider these coordination strategies:
- Centralize due dates by requesting adjustments from creditors
- Utilize budgeting apps that track all financial obligations
- Maintain separate savings for each payment category
- Schedule automatic payments where feasible and appropriate
- Review all statements monthly for accuracy and unauthorized activity
Your secured card should complement rather than complicate your existing financial responsibilities. If you currently repay personal loans, auto financing, or other obligations, ensure your secured card payments fit comfortably within your monthly budget without creating strain.
The credit utilization calculation considers your total available credit across all revolving accounts, not individual cards in isolation. Adding a secured card with responsible usage can actually improve your overall utilization ratio by increasing total available credit. If you maintain $500 in balances across $2,000 in total limits, your utilization sits at 25%, within the optimal range.
Monitoring Progress and Adjusting Strategy
Successful credit building requires ongoing assessment and strategy refinement. How a secured credit card works to build your credit depends partially on your monitoring practices and willingness to adjust approaches based on results.
Credit Monitoring Resources
Most secured card issuers now provide free credit score tracking through their mobile apps or online portals. These scores, typically FICO or VantageScore models, update monthly and help you gauge your progress. While these scores may differ from those lenders use for qualification decisions, they provide directional guidance for your credit-building journey.
Free annual credit reports from AnnualCreditReport.com allow you to review your complete credit files from all three bureaus. Examining these reports helps you identify errors requiring dispute, verify that your secured card appears correctly, and understand how different factors influence your overall credit profile.
Metrics to track monthly include:
- Credit score changes and trending direction
- Payment history accuracy across all accounts
- Credit utilization percentages on revolving accounts
- New inquiries or accounts appearing on reports
- Derogatory marks and their scheduled removal dates
Significant score increases typically appear after three to six months of responsible secured card usage. Expect gradual improvement rather than dramatic jumps, particularly if you're recovering from serious derogatory marks like bankruptcies or charge-offs. Consistency produces results over time, with most users seeing 20 to 60 point improvements within the first year.
Alternatives and Complementary Strategies
While secured credit cards provide powerful credit-building tools, they work most effectively as part of comprehensive financial improvement strategies. Understanding how a secured credit card works alongside alternative approaches maximizes your progress toward financial goals.
Credit-builder loans offer parallel pathways for establishing positive payment history. These specialized products hold your borrowed funds in a savings account while you make monthly payments. Upon completing the payment schedule, you receive the accumulated funds, having built payment history throughout the term. The combination of a secured card and credit-builder loan diversifies your credit mix while accelerating score improvements.
Becoming an authorized user on someone else's established credit card account can supplement your secured card efforts. When the primary cardholder maintains excellent payment history and low utilization, these positive factors may appear on your credit reports. However, this strategy carries risks if the primary cardholder's habits deteriorate or if they remove you as an authorized user unexpectedly.
| Strategy | Credit Building Speed | Risk Level | Cost Considerations |
|---|---|---|---|
| Secured Credit Card | Moderate | Low | Deposit + fees |
| Credit-Builder Loan | Moderate | Low | Interest charges |
| Authorized User | Fast | Moderate | Relationship dependent |
| Rent Reporting | Slow | Very Low | Service fees |
Rent reporting services that add your rental payment history to credit reports provide another complementary approach. While not all scoring models incorporate rental data, those that do can benefit from your consistent housing payments. These services typically charge monthly fees ranging from $5 to $25.
Building or rebuilding credit through secured cards requires patience, discipline, and strategic management, but the results create lasting financial opportunities. Whether you're establishing credit for the first time or recovering from past challenges, responsible secured card usage demonstrates creditworthiness that opens doors to better financial products. If you're ready to take the next step in your financial journey, Standard Financial offers flexible lending solutions throughout Louisiana, Mississippi, Tennessee, and Georgia, including options designed specifically for clients rebuilding their credit profiles. Our experienced team can help you navigate your options and find financing solutions that fit your current situation and future goals.

No comment yet, add your voice below!